Ross Stores Faces A Higher Bar As The Whisper Sits Above Its Own Third-Quarter Guidance
Ross Stores heads into its third-quarter report with a well-documented habit of underpromising and then raising the bar. Management lifted its full-year earnings outlook on each of the last three calls, and the comp trend has run at double digits for two straight quarters. The question now is whether the off-price chain can keep outrunning its own deliberately cautious guidance as it moves into much tougher comparisons, or whether this is the quarter when the expected deceleration finally shows up in the numbers.
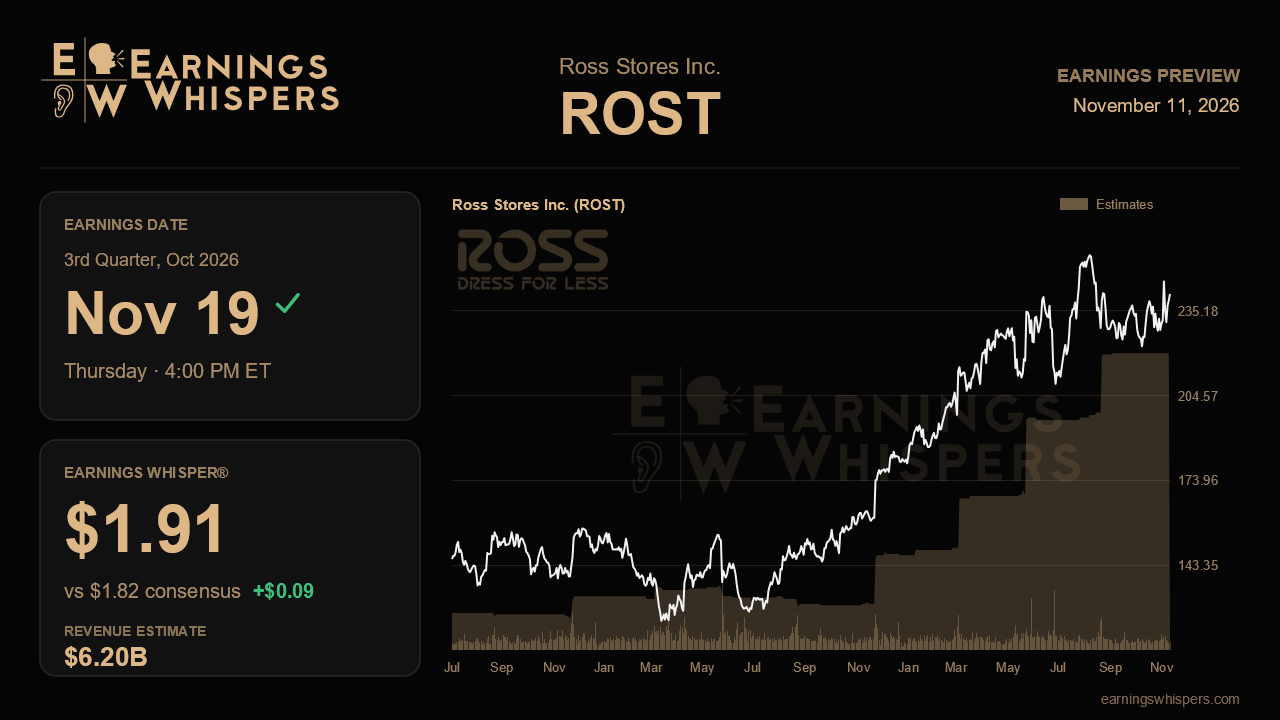
Wall Street expects earnings of $1.82 per share on revenue of about $6.20 billion when Ross reports after the close on November 19. That would be roughly 15% EPS growth and nearly 11% revenue growth from a year ago, which is a strong result for a mature discount retailer. Management guided to $1.75 to $1.83 for the quarter, so consensus already sits at the very top of the range, having climbed from about $1.74 when the guidance was issued. The Earnings Whisper of $1.91 goes further, landing well above the high end of company guidance. In other words, the market is not simply expecting Ross to hit its plan; it is expecting another meaningful beat. For the full year, the company now guides to $8.01 to $8.17 excluding a one-time tariff refund worth about $0.60 per share.
The core of the story remains traffic. Comps went from 7% to 9% to 17% to 10% over the last four quarters, all driven by more transactions rather than bigger baskets, and management credited new customers across demographics, including younger shoppers, plus measurable reactivation of lapsed ones. For the third quarter, Ross raised its comp outlook to a 6% to 7% gain. A result comfortably above that range would validate the idea that customer acquisition is durable rather than a temporary trade-down effect. A comp at or below the low end would suggest the first-half surge borrowed from later quarters. Home, which inflected to mid-teens growth last quarter, is another useful tell on whether the merchandise breadth story is broadening.
Margins will matter as much as sales. Merchandise margin improved steadily from a slight decline a year ago to a 110 basis point gain last quarter, while operating margin expanded about 205 basis points excluding the tariff refund. Offsetting that, freight and domestic fuel costs are unhedged and were flagged as an ongoing headwind, incentive compensation pushed SG&A slightly higher, and management also raised the possibility that competitors may plow their own tariff refunds into lower prices. Inventory is the swing factor to scrutinize closely. Consolidated inventory was up 18% at the end of the second quarter, faster than the 12% rise in the first. If sales held up, that was well-timed buying; if not, it sets up markdown risk heading into the holiday quarter. Progress on the expanded 115-store opening plan and continued strong productivity in the Northeast and other new markets would further support the growth case.
The mood around the stock has cooled despite the raised guidance. Sentiment has slipped to modestly bullish from a noticeably warmer reading before the last report, and shares are down about 1% since then, roughly in line with a softer S&P 500. Still, the stock trades comfortably above its 200-day moving average and sits in the upper part of its post-earnings range, a few percent below the high of about $249.
Ultimately, this report hinges on whether Ross can deliver a comp at or above its raised 6% to 7% target without eroding margins or leaving excess inventory behind. If it does, a fourth consecutive guidance increase becomes plausible and the early-innings narrative holds. If comps land in range but merely meet a bar the whisper has already moved higher, the stock may need more than a beat of its own guidance to be rewarded.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-05 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-22 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-05 |
