Intuit's First Test After Its Growth Reset Hinges On QuickBooks Customer Momentum
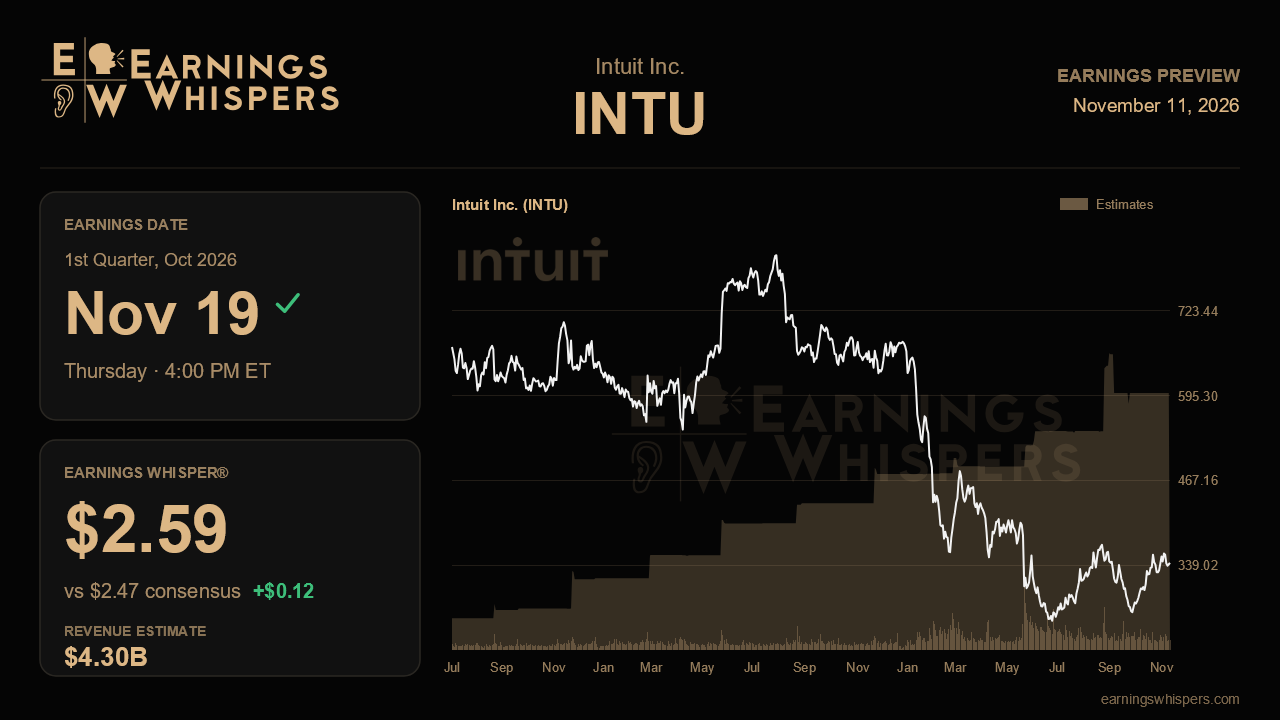
Three months ago Intuit told shareholders it would deliberately trade some near-term revenue growth for a wider funnel of new customers, cutting its fiscal 2027 sales outlook to 9% to 10% after delivering 13% to 14% the year before. The stock has since risen 5.9% while the S&P 500 slipped, a sign the market has largely accepted the reset as a choice rather than a symptom of trouble. The fiscal first-quarter report, due after the close on November 19, is the first chance to see whether that bet is paying off, and because this quarter falls well outside tax season, the evidence will come almost entirely from the small business franchise.
The numbers themselves look well anchored. Analysts expect GAAP earnings of $2.47 a share on revenue of $4.30 billion, squarely inside management's reaffirmed guidance of $2.44 to $2.48 and $4.294 billion to $4.313 billion. Revenue growth of roughly 10.7% would sit right on the new full-year trajectory, while earnings would be up sharply from $1.88 a year ago, reflecting the margin expansion and workforce savings behind management's call for 22% to 24% GAAP EPS growth this year. The whisper number of $2.59 sits a meaningful 12 cents above consensus, suggesting more aggressive investors expect Intuit to clear its own range on cost discipline. There is a wrinkle on the full year, however: the Street's $23.49 EPS estimate already sits above management's $22.88 to $23.12 outlook, even as revenue forecasts hug the low end of guidance. In other words, analysts are betting on profit upside rather than a sales rebound, which raises the stakes for any commentary on expenses.
The most important operating question is whether the front door is actually widening. Online paying customers grew just 3% last quarter, and the launches of QuickBooks Free and QuickBooks Lite, which had passed 20,000 active or converted customers, were pitched as the remedy. A visible uptick in customer additions, or credible early conversion data showing free users moving to paid plans, would validate the strategy. Flat customer growth paired with softer pricing would instead suggest Intuit gave up revenue without getting the volume it wanted. Online ecosystem ARPC accelerated to 15% last year, so the trade-off between customer growth and monetization deserves close attention.
The bright spots also need to hold their pace. Mid-market revenue rose 39% last year, Intuit Enterprise Suite annualized revenue topped $145 million at four times the prior-year level, and online payment volume has grown near 30% every quarter. Management noted that a new payments partnership delivered a one-time launch benefit in the fourth quarter, so a modest deceleration in money growth would be understandable, but a sharp slowdown would undercut the case that the big bets can offset a slower consumer business. Desktop, guided to a low-single-digit decline, and Credit Karma, expected to grow 11% to 13% after roughly 20% last year, are the likeliest sources of drag. Reporting changes, including stock compensation moving into non-GAAP figures and Mailchimp becoming its own segment, will add noise to comparisons.
Sentiment has edged more bearish, with the reading slipping to -0.29 from -0.256 ahead of the last report, even as the shares outperformed. The stock, at $342.64, trades below its 200-day moving average of $353.51 and about 6% beneath its post-earnings high of $366.47, recovering from a low near $262 but not yet threatening a breakout.
Ultimately, this report will be judged less on whether Intuit lands inside a narrow guidance range and more on whether customer acquisition shows early signs of reaccelerating. If new QuickBooks tiers are filling the funnel while margins keep expanding, the reset looks like a deliberate reinvestment from strength. If customer growth stays stuck near 3%, the market may start to wonder whether slower growth is a strategy or simply the new reality.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-02 | |
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-25 | |
| Oct-23 | |
| Oct-23 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 |
