Nebius Beats On A One-Off-Boosted Quarter And Trims 2026 Guidance, But Better Contract Economics And A $12-13B 2027 Outlook Shift The Debate To Execution
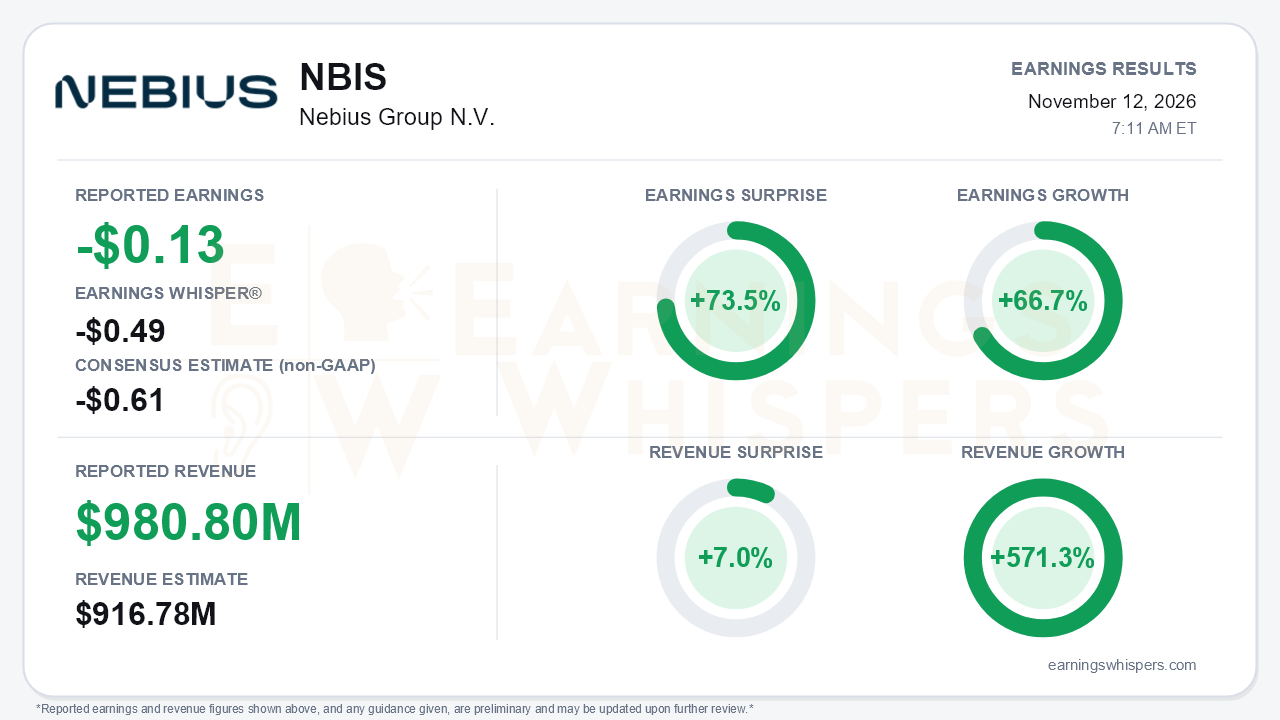
Nebius Group delivered a large headline beat for the September quarter. It reported a loss of $0.13 per share against a consensus estimate of -$0.61 and an Earnings Whisper of -$0.49, a 73.5% surprise. Revenue of $980.8 million topped the $916.78 million consensus by 7.0% and grew 571.3% year over year. Earnings improved 66.7% from a year ago. The central tension is that the quarter looked better than the underlying run rate, and management trimmed 2026 revenue guidance to the low end of its prior range. At the same time, it outlined a 2027 plan that rests on much stronger contract economics. Investors are being asked to look past near-term slippage toward a far larger, far more capital-hungry future.
The quality of the beat deserves scrutiny. Revenue rose 68% sequentially, an acceleration from Q2's 46% gain, but roughly $325 million came from non-recurring asset-light revenue. Without that contribution, sequential growth was far more modest. The one-off also inflated group adjusted EBITDA, which reached $465.8 million for a 47.5% margin, up from about 41% in Q2 and 32% in Q1. Even so, operating leverage is real. The core AI Cloud margin climbed to 53.2% from 50%. GAAP operating income turned positive at $50.4 million versus a $130.2 million loss a year ago, and adjusted net income swung to a $90.9 million profit. Financing is now the main drag on GAAP results. Interest expense jumped to $112.5 million from $14.7 million, and a $49.5 million induced conversion charge kept the GAAP bottom line in the red.
The call preserved a credible growth story built on better unit economics:
- **Pricing:** Q3 agreements priced above $25 million per megawatt, up from $20-25 million in Q2.
- **Prepayments:** These now cover more than 100% of capex on new contracts, up from 50-60%, and were attached to over 90% of Q3 contract value.
- **Payback:** Management said payback shortened to 1 year 7 months from 1 year 10 months.
- **Bookings:** More than $12 billion of total contract value has been committed since the start of Q3.
- **Customers:** Nebius signed its first multi-year enterprise-platform agreements with Databricks, Datadog, Snowflake and Palantir, with Palantir naming Nebius its preferred AI cloud.
The initial 2027 outlook calls for roughly 4x revenue growth to $12-13 billion, $17-20 billion of customer prepayments, and pre-tax break-even in Q4 2027 on five-year depreciation.
Bears have legitimate ammunition, however. Full-year 2026 revenue guidance was cut to $3.0-3.2 billion from $3.0-3.4 billion, a range management had reaffirmed for three straight quarters. Co-location delays drove the cut, including Vineland, New Jersey, after DataOne withdrew temporary generation. That shifts some capacity into Q2 2027 and reverses Q2's assurance of no significant timeline impact. Other forward signals also weakened:
- **ARR visibility:** The $7-9 billion year-end ARR target became more than $7 billion by February 2027, after which ARR guidance will be discontinued.
- **Margins:** The roughly 40% full-year margin guide implies Q4 EBITDA margin falls to the mid-30s.
- **Backlog:** RPO grew only 3% despite the TCV haul.
- **Concentration:** AI natives account for the large majority of new commitments.
The balance sheet shows the strain of this buildout. 2026 capex was raised again to about $27 billion, up from $16-20 billion at the start of the year. Q3 purchases of property and equipment alone totaled $7.3 billion. Operating cash flow was -$273 million as receivables ballooned by $3.8 billion, roughly offset by deferred revenue growth. Cash fell to $7.4 billion from $8 billion. Non-current debt reached $14.0 billion versus $4.1 billion at year-end, funded in part by a $5.75 billion convertible and about $1 billion of at-the-money share sales. With $40-45 billion of 2027 capex planned and 75-85% expected to be funded by prepayments plus asset-backed financing, dilution and leverage remain live concerns.
The market setup reflects that skepticism. Shares closed at $154.69 the day before the report, down 31.6% from the open after the August release. That leaves the stock 13.4% below its 200-day moving average of $178.70 and 44.9% below the inter-earnings high of $280.83 set in mid-August. The stock had rebounded 36.5% from its November 5 low of $113.30 heading into the print, so some recovery was already underway. Investor sentiment remained negative but improved modestly, rising from -0.36 to -0.30. The Earnings Whispers trend readings are mixed, with momentum positive while price and AVWAP trends remain negative.
The bottom line is that Nebius posted a strong beat that was materially flattered by one-time revenue, paired with a guidance trim rooted in physical deployment delays rather than weak demand. Pricing, prepayment coverage, payback and enterprise wins all improved, and the 2027 outlook is enormous. Delivering it will require flawless execution on capacity and tens of billions in additional capital. For a stock that has already given back much of its summer surge, the report shifts the debate from whether demand exists to whether Nebius can build and finance capacity fast enough to capture it.
Read our earnings preview for Nebius Group N.V.: https://www.earningswhispers.com/article/NBIS/22887
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 20 min | |
| 51 min | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 3 hours |
Nebius Lowers Outlook, Addresses Worries Over Financing AI Buildout
NBIS -17.71%
The Wall Street Journal
|
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours |
Nebius Earnings, Revenue Top Estimates. But Neoclouds Sell Off Again.
NBIS -17.71%
Investor's Business Daily
|
| 4 hours | |
| 4 hours |
