Cisco's Record Quarter And Higher AI Targets Collide With Sharply Slower Orders
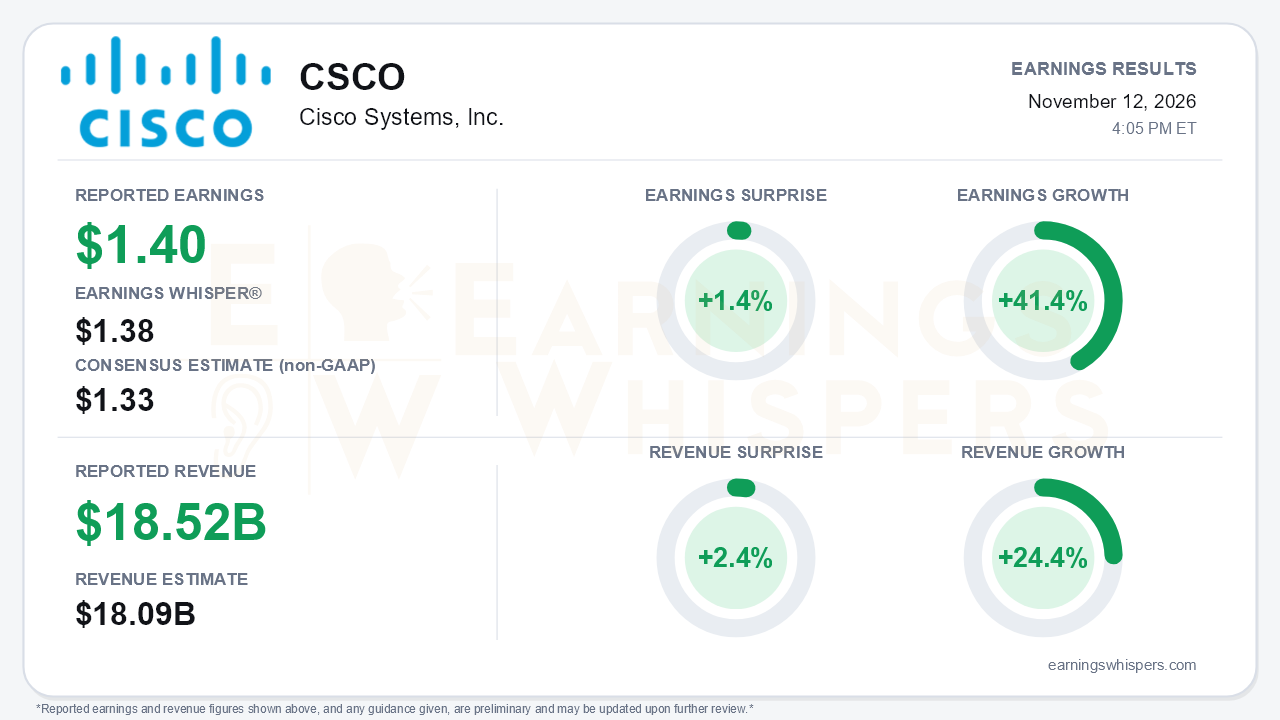
Cisco delivered the kind of quarter that usually ends a debate. Fiscal first-quarter non-GAAP earnings of $1.40 per share topped the $1.38 Earnings Whisper number and the $1.33 consensus, a 1.4% surprise. Revenue of $18.517 billion beat the $18.09 billion consensus by 2.4%. Earnings grew 41.4% and revenue grew 24.4%, which management called Cisco's fastest growth in more than 15 years. The acceleration is real. Revenue growth stepped up from 18% in the fourth quarter and 12% the quarter before, and full-year guidance moved materially higher. The central tension is that the forward indicators are cooling just as the reported numbers peak. Product order growth fell to 21% from 35% in each of the prior two quarters, and the second-quarter revenue outlook implies a sequential decline.
Beneath the headline, the quarter was driven overwhelmingly by Networking. Networking revenue rose 43%, up from 28% in the fourth quarter, and accounted for more than $11 billion of the $14.7 billion product line. Security improved to 7% growth against a low-single-digit plan, while Collaboration grew 8%, Observability 2% and services 1%. The quality of the beat deserves some scrutiny on margins:
- **Gross margin compressed.** Non-GAAP gross margin fell to 65.6% from 68.1% a year earlier, and product gross margin slid 350 basis points to 63.7% on hardware mix and memory costs.
- **Expense discipline did the heavy lifting.** Non-GAAP operating expenses rose just 2%, which lifted operating margin to a record 37.8%, up from 34.4% a year ago and 35.9% last quarter.
- **GAAP results were stronger still.** GAAP EPS of $1.14 rose 58%, helped by lower restructuring and amortization charges.
Operating cash flow rose 36% to $4.4 billion. Inventory climbed to $6.4 billion from $5.7 billion, consistent with a company building for AI demand amid tight optics and memory supply.
The call preserved a credible growth story while giving bears legitimate ammunition. Management raised its fiscal 2027 outlook to the following:
- **Revenue:** $74.8 billion to $75.8 billion, up from $72.2 billion to $73.4 billion.
- **Non-GAAP EPS:** $5.47 to $5.53, up from $5.05 to $5.11.
- **Operating margin:** about 36%, up from roughly 35%.
- **Hyperscaler AI infrastructure revenue:** $9 billion, up from $7.5 billion last quarter and roughly $6 billion two quarters ago.
The order data, however, slowed across most of the business. Service provider and cloud orders rose 47% against 95% in the fourth quarter. Enterprise orders grew 15% against 21%, public sector 13% against 30%, and orders excluding hyperscalers 14% against 25%. Management described hyperscaler ordering as lumpy and nonlinear, and roughly five points of fiscal 2027 growth is expected to come from price increases rather than units. ARR growth of just 4% and RPO growth of 8% show the recurring base is not moving at anything like the product line's pace.
The catalyst list is long and concrete. Cisco reported three new AI design wins, including its first client-side 1.6T optics win at a hyperscaler, bringing the total to 18 over five quarters. G300 is now shipping into hyperscaler labs. The company also cited AMD/Humain infrastructure in production in Saudi Arabia, an expanded sovereign infrastructure push, a new multi-year memory supply agreement, and core security orders up 15%, the best in about three years. The principal risks are supply and margin. Optics are the tightest component, and management expects full-year gross margin near 65%, which leaves operating leverage, not product profitability, as the earnings engine.
Investors were clearly bracing for the deceleration rather than the beat. Earnings Whispers sentiment fell from 0.50 at the prior report to 0.10 heading into this one. That reading remains positive but has weakened substantially. Shares ended the pre-report period at $100.76, down 11.6% from the open after the August report, and 1.2% below the 200-day moving average. The stock is 15.1% below its October 9 inter-earnings high of $118.65 and 7.9% above its November 6 low. Cisco repurchased $2.0 billion of stock at an average of $112.38, well above where shares entered the report. The trend readings are mixed: sequential growth and momentum are positive, while AVWAP remains negative.
The bottom line is that Cisco's reported results and raised guidance are unambiguously strong, but the market setup is more complicated than the surprise implies. Orders have rolled off peak growth rates, product margins are under pressure, and part of the growth is price-driven. Sentiment had already cooled sharply and the stock was sitting near its 200-day average. The next leg depends on whether hyperscaler orders reaccelerate from their lumpy pattern and whether the $9 billion AI target holds as comparisons stiffen in the second half.
Read our earnings preview for Cisco Systems, Inc.: https://www.earningswhispers.com/article/CSCO/22915
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 22 min | |
| Nov-12 |
Dow Jones Futures Rise After Market Weathers Nvidia CEO Huang's Exit, Surging Yields
CSCO
Investor's Business Daily
|
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 |
Jensen Huang Resigns as Nvidia CEO Over Affairs Scandals. His Interim Replacement Has Been Announced.
CSCO
International Business Times
|
| Nov-12 |
