XPeng's Q3 Beat Its Own Revenue Guidance And Guided Q4 Sharply Higher, But Margin Mix And 2027 Cost Headwinds Weigh On The Shares
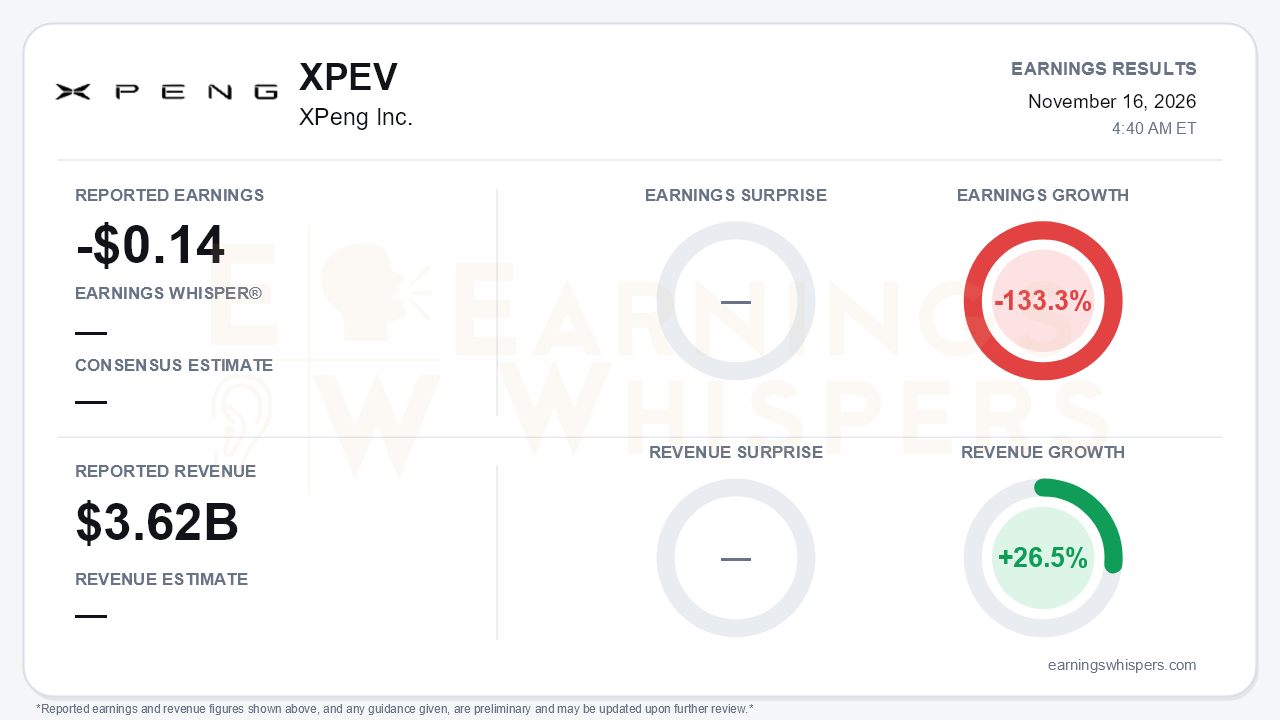
XPeng's third quarter delivered what the bull case needed on volume and what the bear case needed on margins. The company reported a loss of $0.14 per share on revenue of $3.621 billion. Earnings Whispers puts revenue growth at 26.5% year over year in dollar terms and records a 133.3% year-over-year decline in earnings. In local currency, XPeng reported revenue of RMB24.28 billion, up 19.1% year over year. That figure topped the company's own RMB21.7–23.4 billion guidance and rose 23.0% from the second quarter. Fourth-quarter guidance was stronger still: 169,000–174,000 deliveries and RMB30.40–31.80 billion in revenue, implying 36.6%–42.9% revenue growth. Our data indicates that outlook sits above estimates. Here is the central tension: growth is clearly accelerating, but XPeng still loses more money than it did a year ago, and new cost pressures are already visible for 2027.
The quality of the quarter deserves scrutiny. Vehicle margin improved to 13.1% from 12.1% in the second quarter, helped by GX and export mix. Operating loss narrowed to RMB0.75 billion from RMB1.14 billion in Q2 and RMB1.87 billion in Q1. Group gross margin, however, fell to 18.9% from 20.7% sequentially and 20.1% a year ago. The cause was the roll-off of Volkswagen R&D milestone revenue. Services margin dropped to 67.1% from 75.1%, and services revenue slipped 1.9% sequentially. GAAP net loss of RMB0.87 billion was helped by a RMB162 million non-cash gain on the DiDi contingent consideration. As a result, the non-GAAP loss of RMB0.89 billion was actually slightly larger than the GAAP loss. On a year-over-year basis, the non-GAAP loss widened sharply from RMB0.15 billion. Selling, general and administrative expenses rose 11.2% sequentially on marketing spend and franchise commissions. Operating leverage is improving, but it is not yet showing up in year-over-year earnings.
The call preserved a credible growth story, and management's tone was noticeably more confident. October deliveries topped 50,000 for the first time, and November is expected to exceed 60,000. That delivers on the Q2-call target of more than 60,000 per month in Q4. The Mona L05 launched in late October with more than 10,000 first-month deliveries expected. Overseas momentum was the clearest positive:
- October set an overseas record of 13,000 units, up 166% year over year.
- Full-year 2026 overseas volume should exceed 100,000.
- Exports now account for more than 20% of volume.
- Management said export gross margin runs at more than twice the domestic level.
- The 2027 plan calls for overseas volume to more than double, with more than 1,000 stores.
The balance sheet also strengthened. Operating cash flow exceeded RMB2 billion, and cash rose to RMB45.41 billion. Inventory, however, swelled to RMB16.86 billion from RMB10.38 billion at year-end as the company built ahead of the Q4 ramp. Short-term borrowings also more than doubled over the same period.
Bears have legitimate ammunition for 2027. Management guided Q4 average selling prices slightly lower as the L05 mix rises, and framed full-year gross margin only as "high teens." Several new headwinds surfaced on the call:
- China's export VAT rebate on fully built vehicles will phase out over 2027–2028, which directly pressures the highest-margin part of the business.
- Memory chip and AI-component costs are inflating.
- A new battery consumption tax is pending, with supplier negotiations ongoing.
- Management described the 2027 domestic market as only slightly better than 2026.
- No 2027 financial guidance was offered.
On the technology side, the newer initiatives add optionality but come with softer timelines. These include the AI Engineering unit selling chips, models and ADAS technology to third parties, Guangzhou L4 robotaxi demonstration approval, and a humanoid production line targeting external sales in Q2 2027. EU ADAS approval slipped from "first half of 2027" to simply "2027," and robotaxi scaling is now pushed to 2028.
The market setup is more complicated than the guidance implies. Shares closed at $9.37 heading into the report, down 20.8% since the open following the August release. That leaves the stock 33.1% below its 200-day moving average of $14.01 and just 4.8% above the $8.94 52-week low set on October 30. Investors were clearly selling the stock even as monthly deliveries climbed. Investor sentiment remained positive but weakened meaningfully, falling from 0.50 to 0.31 before the report. The internal trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that XPeng's operating engine is accelerating. The Q3 revenue beat, record October deliveries, rising vehicle margins and a powerful Q4 guide all point in that direction. Even so, the stock has been priced for disappointment. The beat came alongside a lower gross margin, a year-over-year earnings decline, and a growing list of 2027 cost and tax headwinds that management chose not to quantify. Q4 execution will likely look strong. The harder question is whether vehicle margin gains and overseas mix can offset the loss of the export rebate and rising component costs next year.
Read our earnings preview for XPeng Inc.: https://www.earningswhispers.com/article/XPEV/23063
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 6 hours | |
| 12 hours | |
| 12 hours | |
| 13 hours | |
| 15 hours | |
| 15 hours | |
| 16 hours | |
| 17 hours | |
| 19 hours | |
| Nov-13 | |
| Nov-13 | |
| Nov-09 | |
| Nov-05 | |
| Nov-04 |
