Best Buy's First Report Under New CEO Tests Whether TV Revival Can Offset Computing Slowdown
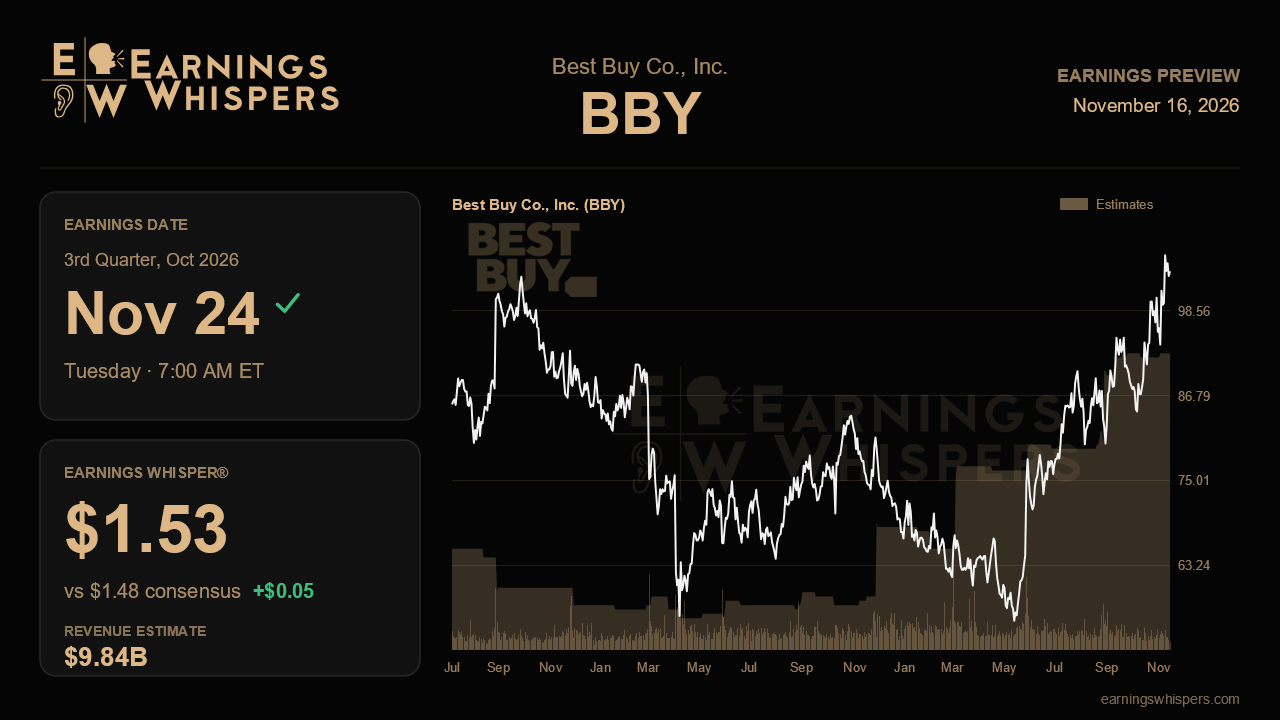
Best Buy enters its fiscal third-quarter report with something it has not had in years: genuine momentum, and a stock price that has already paid for much of it. Last quarter's 4.1% comparable sales gain crushed the company's own expectation of roughly 1%, and management raised every major line of its full-year outlook. Since then the shares have climbed about 29% while the S&P 500 slipped nearly 2%. That leaves Jason Bonfig, who took over as chief executive on November 1, presenting his first quarter with a much higher bar than his predecessor faced just a few months ago.
The Street is looking for earnings of $1.48 a share on revenue of $9.84 billion, up 5.7% and 1.7% from a year ago. That is modest growth, and a noticeable step down from the 15% EPS gain posted last quarter. The Earnings Whisper sits at $1.53, a few cents above consensus, signaling that the more aggressive crowd expects another beat. The math behind the full-year guide matters here. Management now sees fiscal 2027 EPS of $6.70 to $6.90, up from $6.30 to $6.60, and the first half already delivered $2.75. A $1.48 third quarter would require a holiday quarter of roughly $2.47 to $2.67 to land in the range, so the November print and any update to the outlook will shape how believable the upper end looks.
The most important tension is the handoff between growth engines. Computing has been Best Buy's workhorse for ten straight quarters, but this quarter laps last year's Windows 10 end-of-support surge, which made the year-ago third quarter its strongest. Management already warned that computing would slow in the back half, and memory cost inflation complicates the picture: average selling prices rose in the mid-teens last quarter while units fell high single digits. Higher prices can flatter revenue, but shrinking unit volume is the real signal of demand, and further unit erosion would suggest consumers are balking at pricier laptops.
The offsets need to show up clearly. Home theater swung from a persistent drag to the second-largest driver of comparable sales, with TV sales up 10% after Best Buy began its one-year exclusive on RGB televisions in mid-June. This quarter is the first full period of that exclusivity, so continued double-digit TV growth would validate it as a durable catalyst rather than a launch-month spike. Major appliances, which only returned to slight growth last quarter, need to hold that line. Emerging categories such as AI glasses and trading cards, which more than doubled and contributed about a point of comp, along with Best Buy Business at a 21% growth clip, are smaller pieces that help prove the story is broader than one product cycle.
Margins carry their own test. The raised gross profit outlook rests heavily on Best Buy Ads and the Marketplace, whose full-year gross merchandise value target rose to $1.3 billion. With roughly $550 million booked across the first half, the back half needs a meaningful acceleration, so third-quarter Marketplace progress is worth tracking. Against that, incentive compensation is now running about $130 million above last year, versus $30 million originally planned, which will weigh on SG&A. International, which fell 4.2% last quarter after a 7% gain, is another soft spot.
Sentiment has warmed modestly, and the stock trades near $104, far above its 200-day average near $77 and within about 3% of its post-earnings high of $106.83, putting it close to a breakout. That positioning cuts both ways. The central question is whether TVs, appliances and higher-margin services can absorb the computing comparison while leaving the full-year guide intact under new leadership. A reaffirmed or nudged-higher outlook keeps the turnaround narrative alive; anything that looks like management leaning on first-half gains to protect the range would test a stock priced for continued acceleration.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-12 | |
| Nov-12 | |
| Nov-07 | |
| Nov-03 | |
| Oct-29 | |
| Oct-23 | |
| Oct-20 | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-10 | |
| Oct-07 | |
| Oct-02 | |
| Oct-02 |
