Dollar Tree Must Prove Its $210 Million Reinvestment Is Buying Traffic, Not Just Goodwill
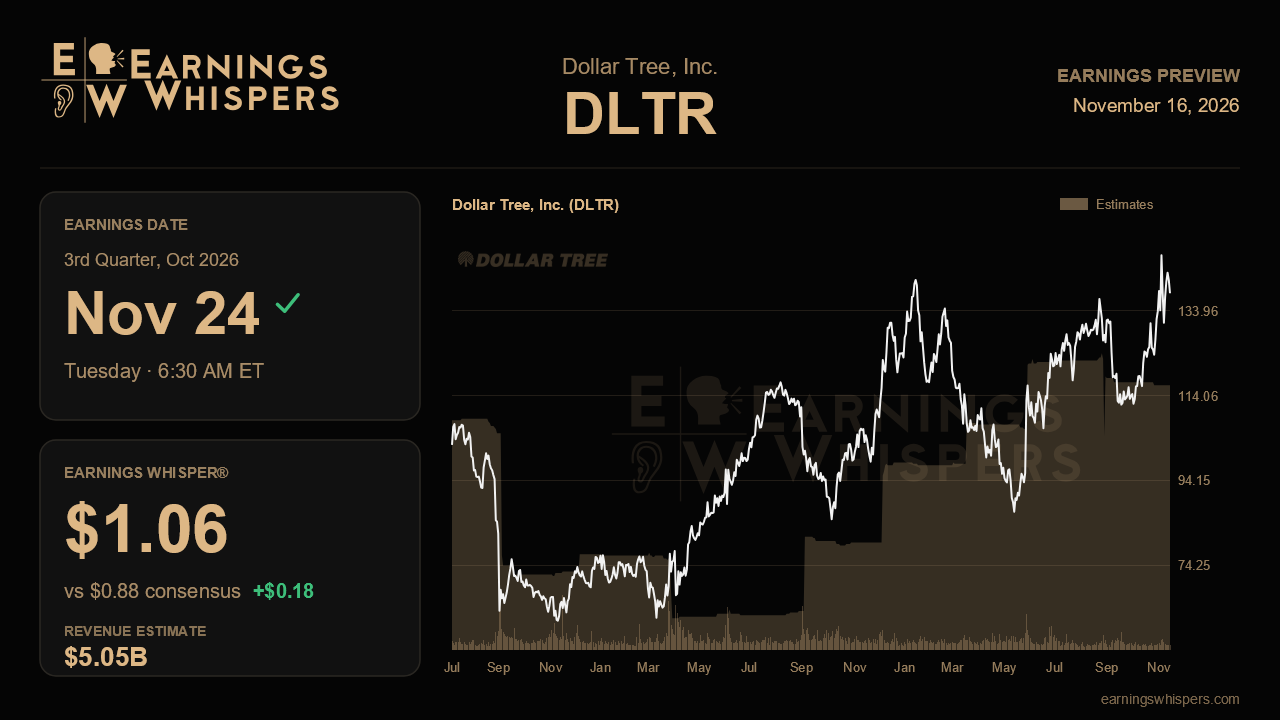
Dollar Tree heads into its third-quarter report with a headline number that will look ugly and an underlying story that management insists is getting better. Earnings are expected to fall sharply from a year ago, yet the decline is largely deliberate. After pocketing a $383 million tariff refund last quarter, the company chose to plow roughly $210 million back into prices, marketing and store conditions, and it told investors that spending would cost about $0.50 a share in this quarter alone. The question for this report is whether that money is buying the kind of customer traffic that justifies giving up near-term profit.
The Street is anchored squarely on management's outlook. Consensus calls for $0.88 a share, just above the midpoint of the company's $0.80 to $0.95 guidance, on revenue of $5.05 billion, the exact midpoint of its $5.00 billion to $5.10 billion range. That works out to a 27.3% drop in earnings against $1.21 a year ago, alongside healthy 6.3% sales growth. Strip out the reinvestment cost, though, and guidance implies underlying earnings of roughly $1.30 to $1.45, comfortably ahead of last year. The whisper number of $1.06 sits well above both consensus and the top of management's range, a sign that the more aggressive crowd expects Dollar Tree to keep clearing its own bar, as it did last quarter when underlying earnings of about $1.39 blew past a $1.00 to $1.15 outlook.
That pattern of beating and raising is central to the setup. Full-year earnings guidance has climbed from $6.50 to $6.90 earlier in the year, to $6.70 to $7.10, and now to $7.70 to $8.05, including about $0.60 of net tariff benefit. The most important proof point behind that progression was traffic, which turned positive at 0.4% in the second quarter after several quarters of declines, arriving about a quarter ahead of plan. A comparable-store sales gain of 3.7% topped guidance on top of a demanding 6.5% comparison. Validation this time would mean traffic staying positive or improving as the reinvestment hits shelves, comps holding comfortably within the reaffirmed 3% to 4% full-year range, and further progress in fixing the roughly one third of stores still below standard. A slide back into negative traffic, despite all that spending, would undercut the argument that the investment is working.
The softer spots deserve equal attention. Discretionary comps slowed to 1.6% from 3.9% in the prior quarter, partly because a helium shortage cost about $15 million in sales, and management assumed no recovery. Meanwhile consumables, up 5.8%, carry lower margins. Management also turned more cautious on gross margin, citing fuel-driven freight surcharges and broad merchandise inflation it is choosing to absorb rather than pass on, with fourth-quarter gross margin guided down year over year. Any sign that this pressure is arriving early, or that discretionary demand is weakening beyond the helium effect, would challenge the story. Lean inventory, which fell 9% on 7% sales growth last quarter, and continued buybacks would help offset some of that strain.
The market has already bought into the turnaround. Shares have gained 15.1% since the last report while the S&P 500 slipped 1.8%, and sentiment has edged up to 27.3% bullish from 22.4%. At $138.08, the stock trades well above its 200-day moving average of $117.22 but about 7% below its post-earnings high of $148.54, so it is not pressing a breakout. That leaves room for a positive reaction, but also signals that a merely in-line quarter may not satisfy holders who have watched three straight raises.
Ultimately, this report hinges on whether Dollar Tree can show that the traffic inflection was durable rather than a one-quarter blip, and that it can defend gross margin well enough to keep the raised full-year range intact. If traffic holds and margins bend without breaking, the reinvestment thesis gains real credibility heading into the holiday quarter.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-16 | |
| Nov-16 | |
| Nov-15 | |
| Nov-05 |
These Were the Stocks That Won and Lost the Most as Dow Jumped More Than 3% after the Midterms
DLTR -6.16%
International Business Times
|
| Nov-03 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-15 | |
| Oct-14 | |
| Oct-06 | |
| Oct-05 | |
| Sep-27 |
