DICK'S Faces Margin Trough Test As Foot Locker Drag Tests Core Strength
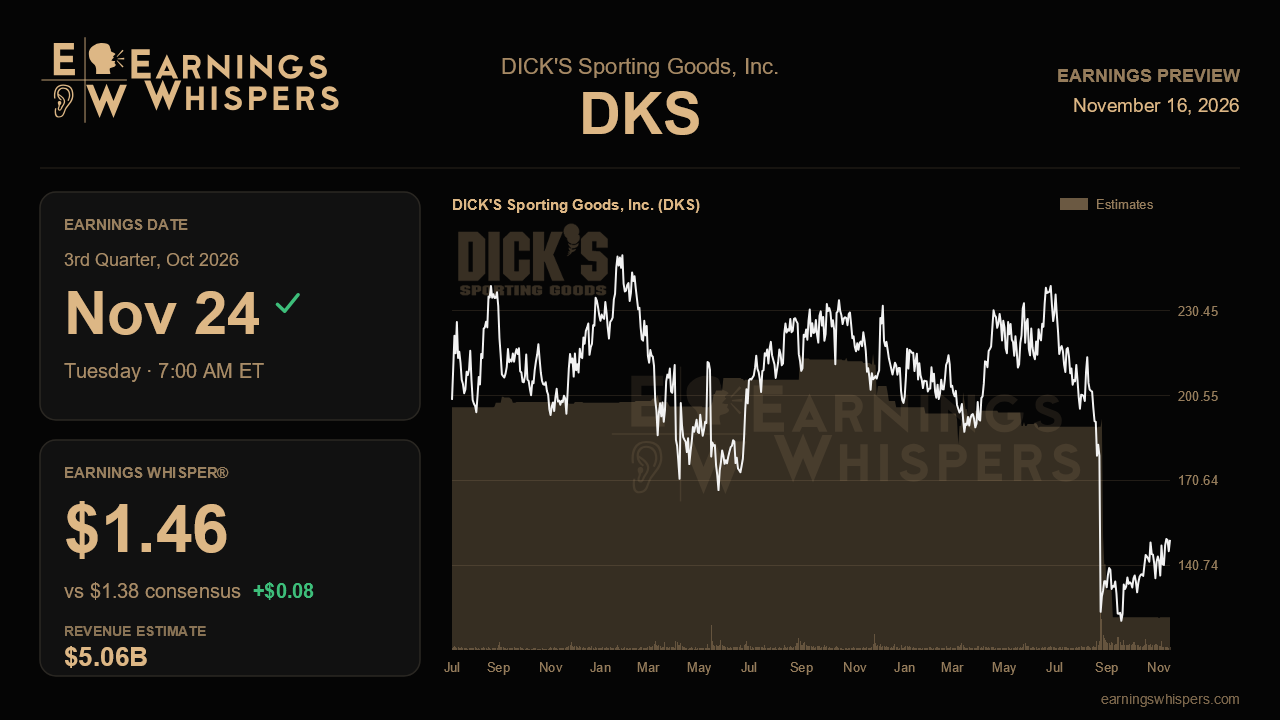
DICK'S Sporting Goods heads into its third-quarter report with a split personality. The namesake chain is still taking share and growing comparable sales at a healthy clip. Foot Locker, the business it bought to extend its reach in athletic footwear, has turned into a drag on profits. Last quarter management cut its full-year outlook after two straight raises and told investors this quarter would be the low point for margins. That makes the November 24 release, due before the open, a check on whether the bottom is really here.
The quarterly numbers show the problem plainly. Analysts expect earnings of $1.38 per share, about half the $2.78 earned a year ago, on revenue of $5.06 billion, up 21.4%. That gap is the story in one line. Revenue is rising because Foot Locker now sits inside the consolidated results. Earnings are falling because Foot Locker is losing money and an industry-wide wave of footwear and apparel discounting is squeezing gross margin. The Earnings Whisper of $1.46 sits modestly above consensus, which suggests some investors think the bar has been set low enough to clear.
Full-year guidance deserves close attention. Management now calls for $11 to $12 per share for the fiscal year ending January 2027, down from $13.50 to $14.50, and trimmed revenue guidance to $21.9 billion to $22.2 billion. The published consensus of $14.24 per share and $22.37 billion is still above both ranges, which likely reflects estimates that were never updated rather than real disagreement with the company. Even so, if management simply holds its range, it would confirm that the reset was big enough. Another cut would suggest the promotional pressure is lasting longer than the company admitted.
The previous call points to three things that matter most. First is the core DICK'S business. Its comps rose 4.9% in the second quarter, about 200 basis points ahead of the industry, with gains in both average ticket and transaction count. Management kept its 2.5% to 4% comp target for the year while cutting the margin outlook to 10.6% to 10.9%. Steady comps here, supported by House of Sport openings, the GameChanger app, trading cards and the new $99 Scorecard Plus paid loyalty tier, would back up the claim that the core business is fine. Second is Foot Locker. Its comps swung from up 0.6% to down 3.6%, and the full-year operating outlook flipped from a profit of $110 million to $150 million to a loss of $40 million to $80 million. The company is counting on Fast Break store remodels, which beat their back-to-school target, and its first major brand campaign in over a decade. Better trends there, especially in Europe, the Middle East and Africa, would be the clearest sign of a turnaround. Third is inventory. Management said the discounting came from an industry glut of older shoe styles and apparel lines. Clean inventory on DICK'S own balance sheet would suggest it is absorbing the problem rather than adding to it.
The market's reaction has been mixed. Sentiment has moved from 22.3% bullish before the last report to 14.4% bearish now. Yet the shares are up 5.2% since that report, beating the S&P 500 by 6.7 percentage points. At $149.70, the stock sits just under its post-earnings high of $150.35, well above the $120.15 low. That puts it close to breaking out of its recent range, though it remains far below the 200-day moving average of $189.56 and the prior quarter's trading range of roughly $176 to $244. In other words, the stock has recovered from the selloff, but it has not won back investors' confidence.
In the end, this report turns on whether the third quarter is truly the margin bottom management described. If DICK'S keeps outgrowing the industry while Foot Locker's losses stay within the reduced guidance, the bad quarter starts to look temporary and contained. If Foot Locker slips again or the core business's margins erode further, the guidance cut could look like the start of a longer slide rather than a one-time reset.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-11 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-30 | |
| Oct-29 | |
| Oct-27 | |
| Oct-20 |
