Medtronic's First Clean Quarter Since Its Extra Week Tests Whether Acceleration Is Real
Medtronic's last report was the kind medical-device investors rarely see from a company this size: the strongest organic growth in roughly eight years outside of COVID distortions, a mid-year guidance raise, and a management team suddenly talking about doubling down. The catch was that a 53rd selling week added about $570 million, or roughly 670 basis points, to that headline figure. The fiscal second-quarter report, due before the open on November 24, is the first quarter without that cushion. It will show whether the underlying pace of about 7% organic growth is a durable new run rate or a high-water mark.
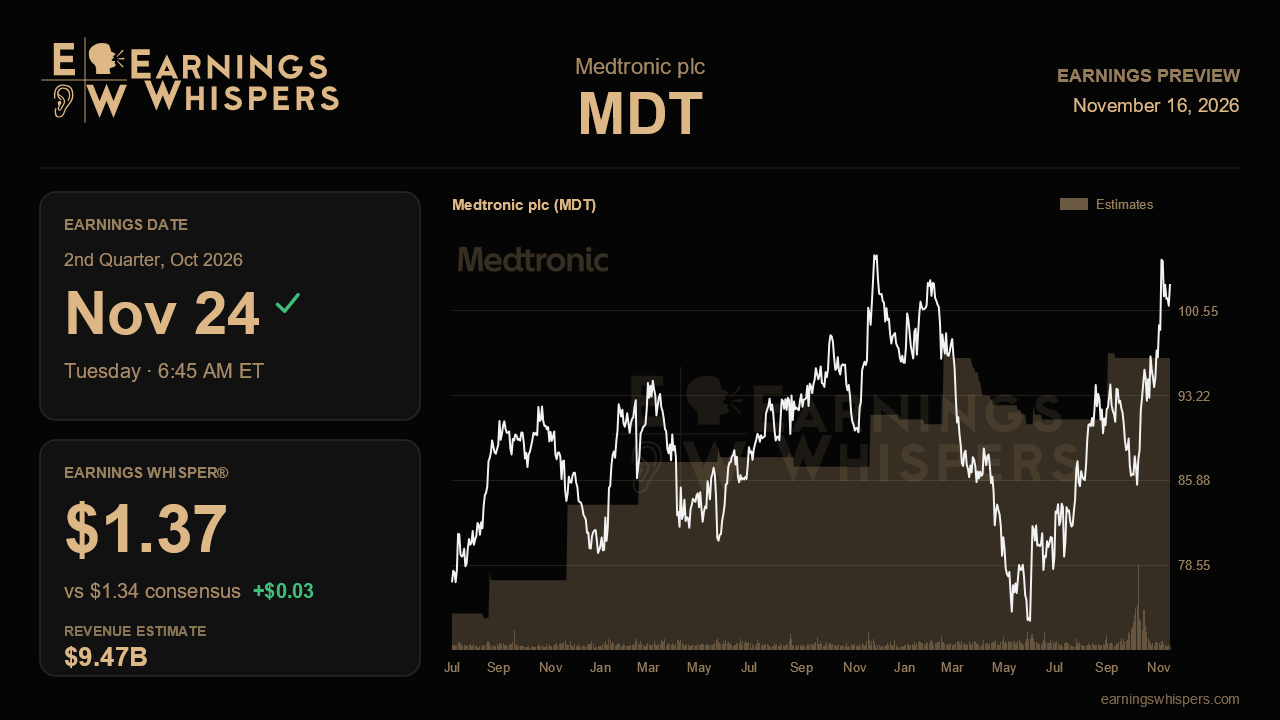
Wall Street expects earnings of $1.34 per share on revenue of $9.47 billion. That implies sales growth of 5.7% from a year ago but a 1.5% decline in per-share profit from $1.36. The Earnings Whisper of $1.37 sits a few cents above consensus. That is a modestly higher bar rather than a dramatic one, and it suggests the more engaged crowd expects Medtronic to clear the published estimate. The full-year picture matters more. Management now guides to fiscal 2027 EPS of $5.94 to $6.00 and revenue of $39.00 billion to $39.18 billion. The $5.94 consensus sits at the very bottom of that earnings range, and the $38.64 billion revenue estimate falls below the guided range entirely. In other words, analysts have not fully bought the raise, which leaves room for upside if the second quarter confirms management's math.
The operating story centers on breadth. Last quarter, cardiac rhythm, cranial and spinal, and surgical all accelerated sharply from low- to mid-single-digit growth. Management lifted its cardiac ablation outlook to more than 2.5 times market growth for the year and specifically called for more than 3 times market in the second quarter. That makes ablation the cleanest scorecard item. With the U.S. Afera installed base expanding 35% sequentially after 40% the quarter before, catheter pull-through should keep revenue climbing even as comparisons toughen. Hugo tracking toward more than 50,000 procedures by year-end, pelvic health procedures doubling, and early reimbursement progress for the Ardian renal denervation program are the newer threads that would show the growth is not resting on one franchise.
The risks were flagged openly. Growth in the cardiac pacing leadless and McGrath-type franchises that ran hot last quarter is expected to normalize. Neuromodulation was soft at 3% on spinal cord stimulation weakness, and structural heart managed only low-single-digit growth. A stall in either would undercut the breadth argument. Margins deserve equal attention. Management trimmed expected operating-margin expansion to about 50 basis points from 60, partly because of foregone interest on the $700 million Cornerstone Robotics investment. Consensus already embeds a year-over-year EPS dip, so a quarter that shows revenue upside without leakage into spending would be well received.
The market has front-run some of this. Shares are up 9.4% since the last report while the S&P 500 slipped 1%, and at $102.86 the stock trades well above its 200-day average of $88.32 and about 3% below its post-earnings high of $106.20. The entire trading range has shifted higher from the prior quarter. Sentiment has cooled, though, falling to 18.5% bullish from 26.2%. That points to some caution about the extra-week hangover even as the stock climbs. An investor day on December 10 and 11 also gives management a reason to hold back big-picture targets.
The central question is simple. If organic growth holds near 7% without the extra week, ablation delivers the promised acceleration, and margin guidance stops slipping, the improving narrative stays intact and the Street's below-guidance revenue estimates look too cautious. If growth fades toward the 5% to 6% pace of last year, the prior quarter will look like a calendar gift rather than an inflection.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 42 min | |
| 1 hour | |
| 2 hours | |
| 6 hours | |
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-10 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 |
