Kohl's Faces A Holiday-Quarter Test Of Whether Its Comeback Can Outlast The Tariff Windfall
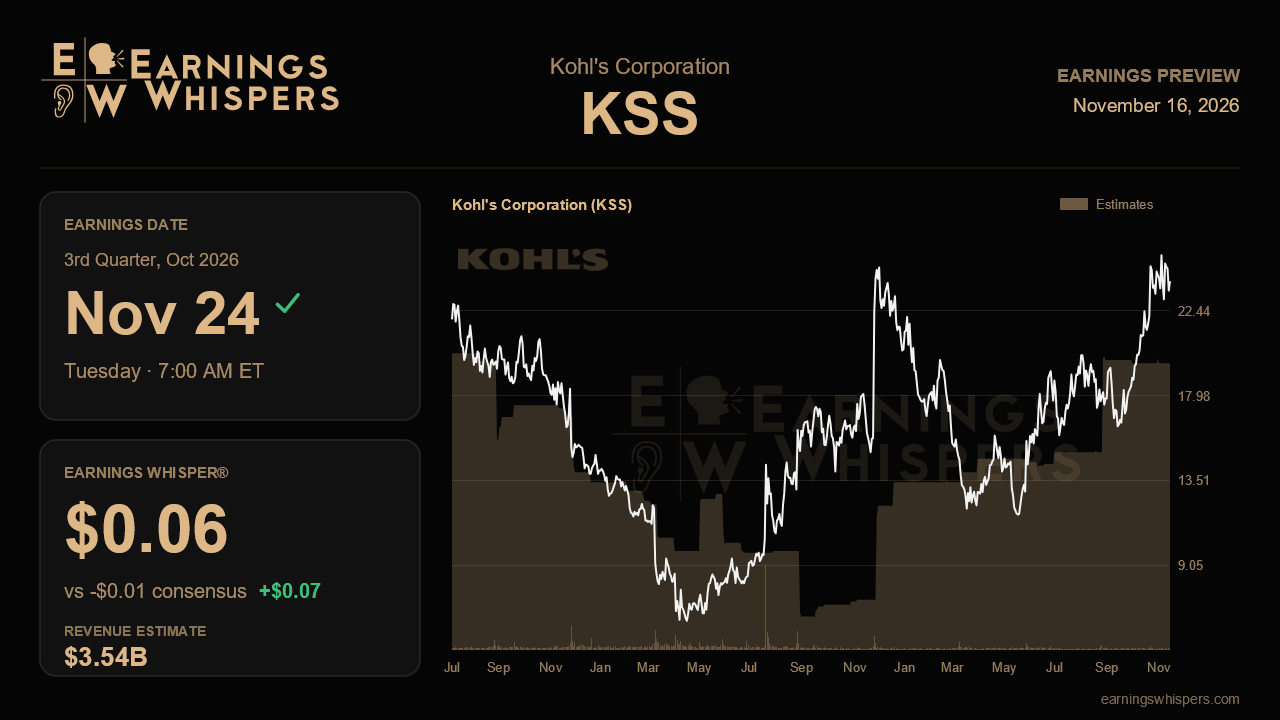
Kohl's heads into its third-quarter report with a stock that has gained about 44% since its last update, while the S&P 500 slipped over the same stretch. The rally followed a genuinely upbeat summer quarter. Comparable sales improved for a fourth straight period, the Kohl's card customer turned positive, and management raised full-year guidance on comps, operating margin and earnings. The catch is that much of that earnings lift came from a one-time tariff refund, and management has already said it plans to spend that money on promotions in the back half. This report is the first real look at whether the underlying business can stand on its own once the windfall is being reinvested rather than banked.
The Street is braced for roughly breakeven results: a loss of a penny per share on revenue of about $3.54 billion, compared with a $0.10 profit and $3.58 billion in sales a year ago. That implies a modest 1% revenue decline and a sharply lower bottom line, which is consistent with management's warning that second-half gross margin will fall as refund dollars fund holiday value. The whisper number of $0.06 sits slightly above consensus. The gap is small in dollar terms, but because consensus rounds to zero, it signals that the more informed crowd expects Kohl's to stay profitable rather than slip into the red.
The full-year picture is more puzzling. Management now guides to adjusted EPS of $1.80 to $2.40, up from $1.00 to $1.60, on revenue of $15.29 billion to $15.53 billion. Consensus of $1.38 sits well below the low end of that range, while the $15.38 billion revenue estimate sits comfortably inside it. One plausible reading is that analysts are discounting the roughly 65 cents of tariff benefit embedded in the outlook. Either way, the Street is skeptical, which means Kohl's does not need a heroic quarter to look good relative to the range it has set for itself. Reaffirming the guidance would carry more weight than usual.
Operationally, the comp trajectory is the key thread. Comps moved from a 2.8% decline two quarters before last to a 0.9% decline in the second quarter, and the raised range of down 1.5% to flat leaves room for further improvement. Another step toward flat would validate the recovery story; a reversal would suggest last quarter's traffic, the best since about 2019, was borrowed rather than earned. The card customer is a crucial tell because it represents Kohl's most loyal shoppers, and holding that positive inflection through a promotional season would be meaningful. Women's apparel is worth watching closely too. Management blamed its slip to a 1.5% decline on inventory shortages after strong sell-through and promised larger fall receipts. If women's and proprietary brands rebound now that shelves are stocked, the explanation holds. If not, demand was the problem. Sephora, down 4% and facing wider distribution of key brands, is expected to remain a drag, so the question is whether it stabilizes or worsens.
Margin discipline is the other swing factor. Excluding tariffs, gross margin was essentially flat last quarter. Investors should want evidence that promotional reinvestment is driving traffic and share rather than simply giving away profit to a strained low-to-middle income shopper. Faster marketplace growth, the new DoorDash partnership and the restored buyback offer upside, but they are supporting acts.
Sentiment has softened from about 15% bearish to 10% bearish, and the shares at $24 sit far above the 200-day average of $17.29, though still about 6% below the post-earnings high of $25.60. The rally has raised the bar for tone even as the numerical bar remains low. Ultimately, the report hinges on one question: can Kohl's keep comps improving and the card customer engaged while it spends its tariff windfall on discounts, without sacrificing the margin credibility that underpins its raised outlook?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-16 | |
| Nov-10 | |
| Oct-30 | |
| Oct-30 | |
| Oct-29 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Oct-09 | |
| Oct-05 | |
| Oct-02 |
