Dell Must Prove Its $95 Billion AI Backlog Can Convert Despite Memory Constraints
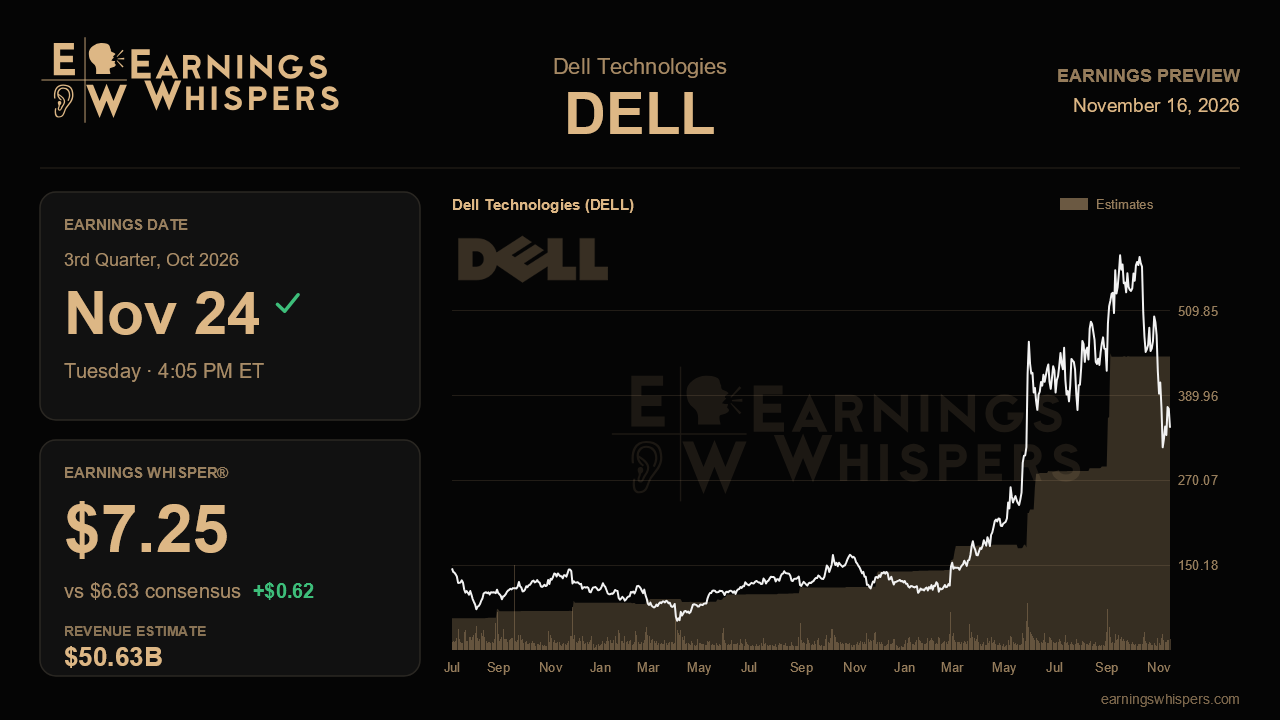
Dell heads into its fiscal third-quarter report with an odd mismatch between business and stock. Three months ago the company delivered record revenue of nearly $47 billion, booked $60.9 billion in AI server orders in one quarter, and raised its full-year outlook for the third straight time. Since then the shares have fallen about 25%, trailing the S&P 500 by more than 24 percentage points. The coming report has to show whether that selloff reflects doubt about the durability of the boom or simply a market that ran ahead of itself.
The Street is asking for non-GAAP earnings of $6.63 a share on revenue of $50.63 billion, an 87.5% jump from the $27.01 billion Dell posted a year ago, when it earned $2.35 a share. Those figures already sit above management's own guidance of roughly $6.50 and $49.0 billion, so analysts are effectively pricing in another beat. The whisper number of $7.25 raises the bar further, implying that a result merely in line with consensus could feel like a letdown. For the full year, Dell guides to about $25.50 a share on $192 billion in revenue, up sharply from $17.90 and a range of $165 billion to $169 billion just one quarter earlier. After a sequence like that, investors have grown accustomed to raises, and holding the outlook steady may not be enough.
The central operating question is conversion. AI backlog swelled to a record $95 billion from $51.3 billion in a single quarter, and management lifted its fiscal 2027 AI server revenue target to $74 billion. Turning that backlog into shipments depends on component availability, and memory supply has been the limiting factor on every recent call. Strong AI shipments alongside continued healthy orders would validate the story that demand still outruns supply. A big shipment quarter paired with a sharp drop in new orders would invite questions about whether the record bookings were a one-time surge, and any sign that neocloud customers are struggling with financing would revive a demand-quality concern that has so far stayed dormant.
Margins are the second test. Infrastructure segment operating margin hit 15% last quarter, up 620 basis points from a year earlier, but management warned that some favorable mix and rate benefits will not repeat every quarter. A modest pullback would be consistent with that caution. A steep one would undercut the argument that Dell's profitability has structurally reset. The broadening of demand matters here too: traditional servers grew 122% with share gains of more than 10 points, and storage rebounded 26%. Those higher-margin businesses help offset thinner AI server economics, so continued strength there would support the earnings trajectory. On the PC side, Dell guided client margins down to around 6% as it prioritizes share, so the focus should be on whether 20% growth holds rather than on profitability.
Sentiment has cooled slightly, sliding from mildly bullish before the last report to marginally bearish now. That shift is small, but it fits a stock that has given back much of its post-earnings run, falling from a high near $596 to about $345. Shares now sit just above the 200-day moving average and closer to the bottom of the range, which suggests a good deal of skepticism is already priced in.
Ultimately, this report turns on whether Dell can show that its enormous backlog is converting at healthy margins while orders keep flowing. Another raise to full-year guidance backed by steady infrastructure profitability would reinforce the acceleration narrative. Signs that supply, margin mix, or order momentum are fading would give the recent selloff a fundamental justification.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-14 | |
| Nov-13 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-10 |
