Ambarella's Physical AI Pitch Meets A Margin, Inventory And Memory Test
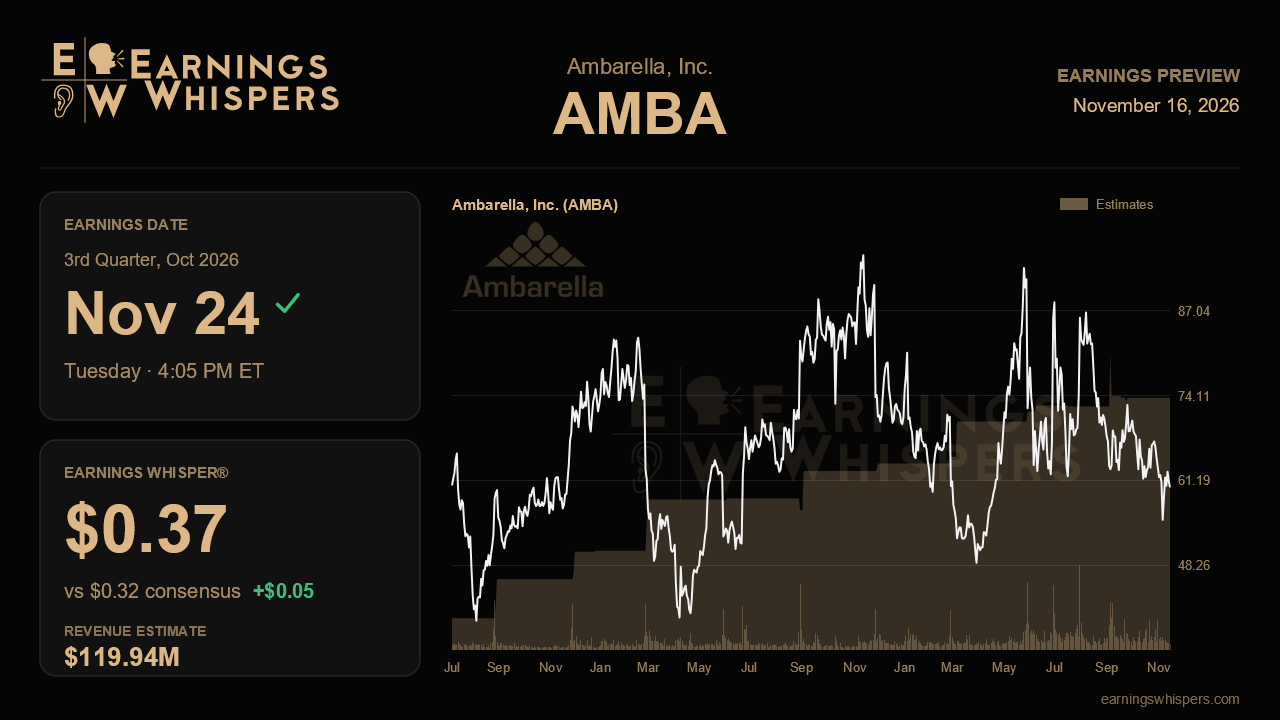
Ambarella spent its last earnings call describing a much bigger future, and the stock has spent the weeks since refusing to believe it. Management more than doubled its view of the five-year addressable market, announced two distribution and integration partnerships each sized at roughly half a billion dollars, and previewed a standalone AI accelerator that pushes the company beyond camera chips. Yet the shares are lower and sentiment has soured. The fiscal third-quarter report, due after the close on November 24, is less about whether the long-range story sounds exciting and more about whether the near-term plumbing of margins, inventory and cash flow can support it.
The headline numbers look manageable. Analysts expect non-GAAP earnings of $0.32 per share on revenue of $119.9 million, which would mark growth of about 10.6% from a year earlier and a solid sequential step up from the $108.1 million reported last quarter. Management guided to $115 million to $124 million, citing favorable seasonality, so the Street sits just a hair above the $119.5 million midpoint and comfortably inside the range. The earnings whisper of $0.37 is meaningfully above consensus, suggesting the more engaged crowd expects operating leverage from the revenue jump to show up on the bottom line. A revenue print near the top of guidance would likely be needed to justify that higher bar.
Gross margin is the first place the bull case could crack. Last quarter's non-GAAP gross margin of 59.3% landed below the midpoint of guidance and continued a slide from 59.9% the prior quarter and 60.9% a year before that. Management said it intends to pass rising supply-chain costs through to customers to defend its 59% to 62% target. This quarter offers the first real evidence of whether that pricing power exists. Stabilization or a modest uptick would validate the claim; another slip toward the bottom of the target band would suggest Ambarella is absorbing costs it cannot fully push onto customers.
The balance sheet deserves equal scrutiny. Free cash flow was negative in each of the past two quarters, driven by IP license payments and an inventory build, and days of inventory climbed to 157 from just 76 a year earlier. Bulls can frame that build as preparation for seasonal strength and new ramps, but the argument only holds if revenue actually consumes it. A decline in inventory days alongside a return to positive cash flow would go a long way toward easing concerns. Continued accumulation, particularly paired with soft fourth-quarter guidance, would look less like confidence and more like a demand miscalculation.
That fourth-quarter outlook may matter most of all. Management flagged the memory shortage as a source of uncertainty because rising DRAM prices could squeeze customers' end-product costs and volumes, even though Ambarella does not buy memory itself. Any clarity on whether customers are cutting builds will shape how the market reads the year-end setup. Investors will also want progress markers on the newer catalysts: early engagement on the X7 accelerator, traction through the Capgemini and Macnica channels, further robotics wins, and continued strength in automotive after last quarter's record driven by commercial-vehicle AI.
The market has already registered its skepticism. Sentiment swung from moderately bullish ahead of the last report to moderately bearish now, and the stock's 4.8% decline since that report trails the S&P 500 by about 2.6 percentage points. At roughly $60, shares sit well below the 200-day moving average near $67 and in the lower part of the post-earnings range between about $54 and $75, a far cry from the prior quarter's $94 peak. That lowered bar creates room for relief if execution is clean. The central question is whether Ambarella can show that its expanding physical AI ambitions are not coming at the expense of margin discipline and cash generation, because without that proof, the $22.9 billion opportunity will remain a slide rather than a valuation driver.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-05 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-04 | |
| Sep-04 | |
| Sep-03 | |
| Sep-03 | |
| Sep-03 | |
| Sep-03 | |
| Sep-03 | |
| Aug-20 | |
| Aug-11 |
