Workday's Promised Second-Half AI Bookings Surge Faces Its First Real Test
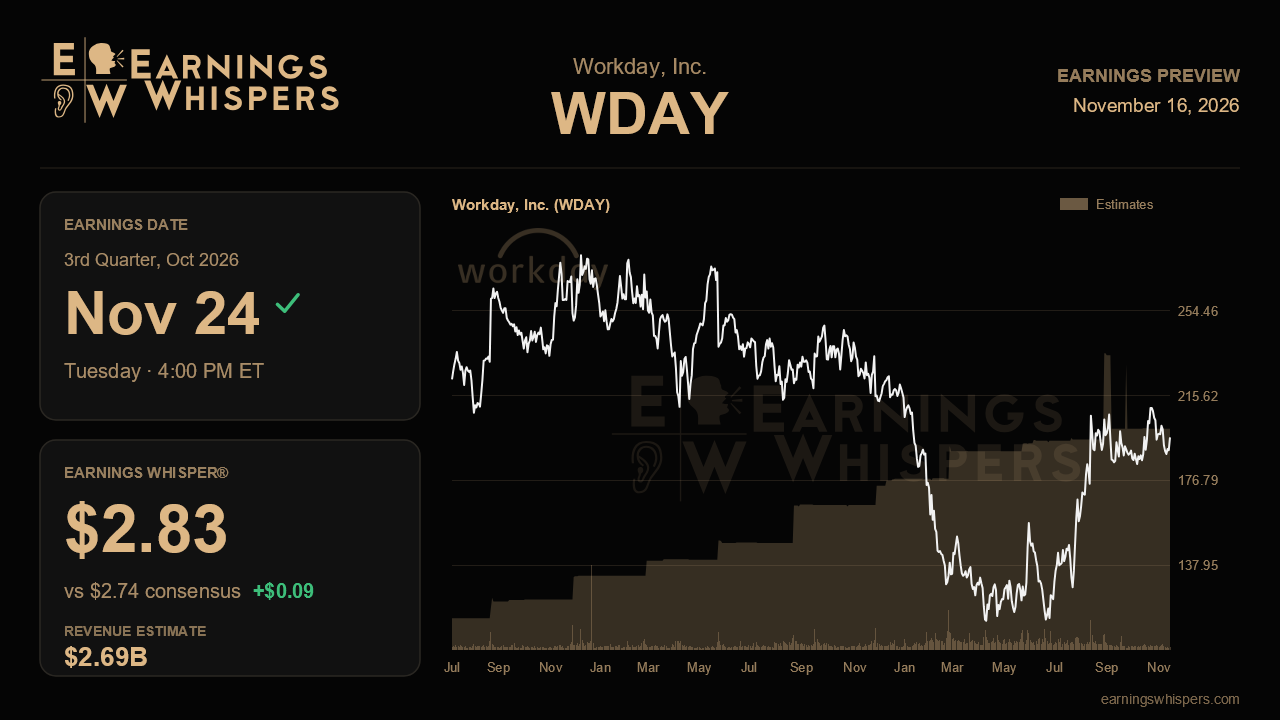
Workday spent the first half of its fiscal year asking investors for patience. Management argued that its agentic AI products, the Sana interface and a new consumption-based pricing model would drive a bookings lift weighted toward the back half of the year, with the revenue payoff largely landing in fiscal 2028. The fiscal third-quarter report, due after the close on November 24, is the first one where that second-half promise should start to show up in the numbers rather than in the narrative.
The Street is looking for non-GAAP earnings of $2.74 a share on revenue of about $2.69 billion, which would be roughly 10.6% growth from the $2.43 billion reported a year earlier. That is respectable but hardly a re-acceleration on the top line, and it sits only modestly above last quarter's $2.65 billion. The Earnings Whisper of $2.83 runs about 3% above consensus, a gap that suggests the market expects Workday to clear the published bar with some room to spare, as profitability has been the more reliable lever. Management has already raised its full-year non-GAAP operating margin target to 30.5% and talked about holding headcount roughly flat by leaning on internal AI productivity, so a beat on earnings would confirm a story investors largely accept.
Revenue guidance is where the tension lies. Workday most recently narrowed its fiscal-year subscription revenue outlook to $9.94 billion to $9.95 billion, lifting the bottom of the prior $9.925 billion to $9.95 billion range while leaving the top untouched. That is a vote of confidence in visibility, not a call for upside. The full-year consensus of $10.66 billion includes professional services, so it is not a clean comparison, but the message is clear: management has repeatedly declined to raise the headline subscription outlook even as it talked up AI momentum. Until that changes, the AI story remains more about future bookings than current revenue.
That makes the leading indicators the real report card. Earlier this year Workday described its best first quarter of new annual contract value growth in five years, agentic AI annual recurring revenue approaching $500 million, and new contract value from agentic products roughly tripling from a year earlier. Customers using its homegrown agents jumped from more than 400 to over 4,000 in a single quarter. Validation this time would look like continued acceleration in those figures, evidence that FlexCredits consumption deals are converting into larger bookings as promised, and early traction for newer offerings such as the Sana Travel Agent and Sana for IT service management, which management pitched as expanding its addressable market. Strength in subscription backlog would help show that bookings momentum is real even if revenue recognition lags.
The risks are also familiar. Seat counts at existing customers have been roughly flat as technology companies trim staff, meaning Workday has needed module and AI upsell just to offset a stagnant employee base. Any sign that headcount pressure is spreading beyond tech, or that large public sector and healthcare deals are again slipping, would undercut the idea that AI is additive rather than merely compensating. A cautious fourth-quarter outlook would also raise questions about how back-half the bookings ramp really is.
Sentiment remains bearish but has softened from the prior quarter, and the stock has risen 3% since the last report while the S&P 500 fell 2.3%. At about $196, shares sit well above the 200-day moving average and in the middle of a $181 to $213 post-earnings range, a far calmer band than the previous quarter's violent swing between roughly $112 and $227. Investors have warmed up, but not to the point of pricing in a breakout. The verdict hinges on whether AI-driven bookings visibly accelerate this quarter, giving management cover to finally push subscription guidance beyond the range it has defended all year.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Nov-16 | |
| Nov-13 | |
| Nov-12 | |
| Nov-12 | |
| Nov-09 | |
| Nov-05 | |
| Nov-02 | |
| Oct-21 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 |
