Urban Outfitters Faces A Margin Test As Fuel Costs And Anthropologie Markdowns Cloud Nuuly Strength
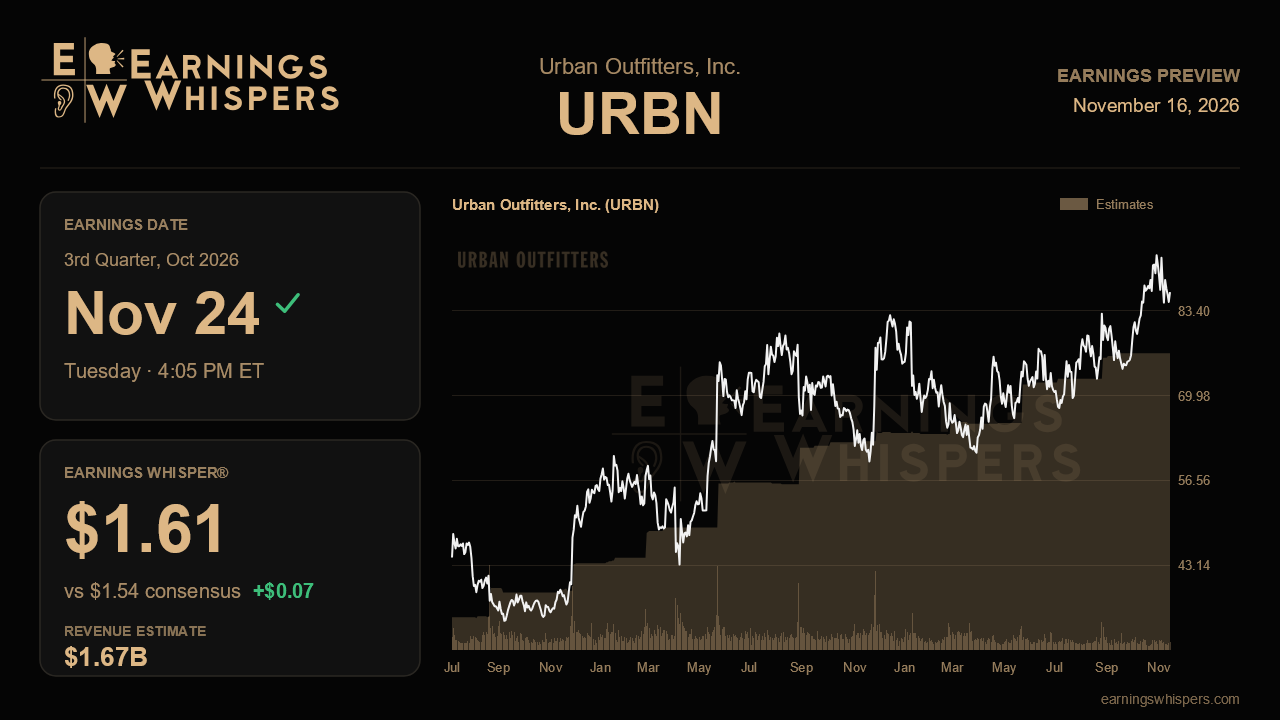
Urban Outfitters heads into its fiscal third-quarter report on November 24 with eight consecutive record quarters behind it and a narrative that has rarely looked healthier. Free People keeps compounding, the Urban Outfitters brand has turned profitable globally, and Nuuly just posted its first double-digit operating margin. The question now is less about demand and more about what reaches the bottom line. Fuel surcharges tied to the Middle East conflict and stubborn markdowns at Anthropologie are pressing on gross margin at the very moment the Street expects earnings to grow faster than sales.
Consensus calls for earnings of $1.54 per share on revenue of $1.67 billion, up roughly 20% and 9% from a year ago, respectively. That is strong growth for a specialty apparel retailer, and the gap between the two rates is the crux of the setup: the Street is counting on operating leverage. The Earnings Whisper sits at $1.61, a modest but meaningful step above consensus, suggesting the investors who follow the stock most closely expect another beat. The company did not provide a fresh quarterly EPS target, so the bar is set largely by its full-year framework, which called for gross margin expansion of about 25 basis points and an improvement in initial markups during the second half.
That margin framework is where the report could validate or wobble. Gross margin expansion shrank to just 4 basis points last quarter from more than 100 basis points a year earlier, and management flagged roughly 70 basis points of fuel-related pressure in each second-half quarter. Newly enacted Section 301 tariffs add another variable, though the company said its net effective rate remains favorable this year. If third-quarter gross margin holds flat or better despite those headwinds, it would confirm that the higher markups management described are real. A meaningful decline would suggest the full-year margin target is at risk and that the earnings beat streak depends more on expense control than pricing power.
Anthropologie is the other pressure point. Its comparable sales slowed to 3% last quarter, and management guided only to low-to-mid single digits for the third quarter while it works through slower-turning inventory. Clean inventory at the end of the period matters more than the comp number itself, since lingering markdowns would carry into the holiday quarter. Anthropologie's beauty expansion, roughly doubling its store footprint this fall, offers an early read on whether newness can reignite traffic. At Urban Outfitters, European comps were expected to moderate to mid-single digits on tough comparisons, so a soft European figure would be anticipated rather than alarming.
Nuuly carries the growth story. Management raised its third-quarter revenue outlook to high-20s growth and lifted the full-year target above $700 million with a high-single-digit operating margin. With growth already decelerating from 43% to 29% over three quarters, holding the high-20s and sustaining margin near 10% would show the business can scale profitably. Early commentary on subscriber response to the Nike and J.Crew additions will help gauge whether the new brands are widening the funnel. Wholesale, guided to low-teens growth after starting the year at mid-single digits, has less room left for upside surprises.
The market has rewarded the story. Shares have gained about 4% since the last report while the S&P 500 slipped, trade well above the 200-day moving average near $74, and sit above the prior quarter's high, though still about 8% below the post-earnings peak of $93.64. Sentiment has warmed to roughly 37% bullish from 30% a quarter ago. Expectations are therefore elevated but not extreme. The deciding issue is whether margins can absorb fuel costs and Anthropologie clearance while Nuuly keeps scaling profitably. If they can, the record streak and the raised outlook remain intact; if gross margin slips, the 20% earnings growth the Street expects will look harder to justify.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-06 | |
| Nov-05 | |
| Oct-30 | |
| Oct-23 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Sep-24 | |
| Sep-10 | |
| Sep-04 | |
| Aug-31 | |
| Aug-28 | |
| Aug-27 |
