Disney's 53rd-Week-Aided Beat Tops The Whisper As The Story Pivots From Streaming Margins To Reinvestment
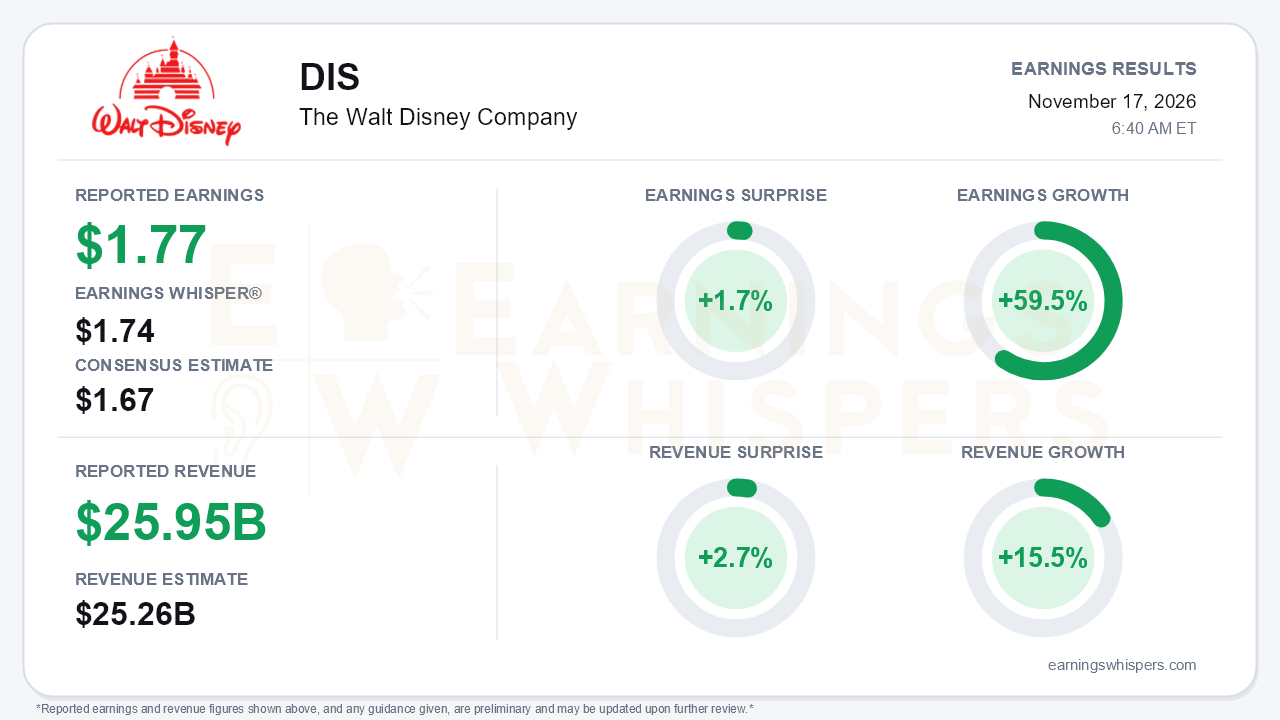
Disney (NYSE: DIS) closed fiscal 2026 with a fourth quarter that cleared every bar it faced. Adjusted EPS of $1.77 topped the $1.67 consensus and the $1.74 Earnings Whisper number, a 1.7% beat, and grew 59.5% from $1.11 a year ago. Revenue of $25.947 billion beat the $25.26 billion consensus by 2.7% and grew 15.5%, a sharp acceleration from the roughly 7% revenue growth reported in the third quarter. Total segment operating income rose 43% to $5.0 billion and exceeded management's own guidance for the second straight quarter. The headline is clean. The more important development is that management used the report to reframe the investment story. Disney is shifting from steady streaming margin expansion toward a heavier reinvestment cycle, and investors will get less visibility into streaming profitability.
The quality of the beat deserves scrutiny because the quarter included a 53rd week. Management estimates the extra week added about $0.17 to full-year adjusted EPS, and it flattered the year-over-year comparisons in Q4. On a cleaner basis, Disney says fiscal 2026 delivered roughly 10% segment operating income growth and 16% adjusted EPS growth, which is solid but well short of the quarter's 43% and 59.5% headlines. The GAAP-to-adjusted gap also matters. Q4 diluted EPS more than doubled to $1.51, yet full-year GAAP EPS fell 18% to $5.63 while adjusted EPS rose 18% to $7.02. Pretax income still rose 71% in the quarter and 18% for the year, so the underlying earnings power is real. Investors simply should not extrapolate the Q4 growth rates.
The operating trends beneath the numbers were constructive. Domestic parks held their third-quarter pace, with attendance up 3% and per-capita spending up 4% excluding the extra week. That is a meaningful improvement from the 1% attendance decline in Q2. Walt Disney World bookings for the first quarter of fiscal 2027 are pacing up. Experiences was newly guided to high-single-digit operating income growth in fiscal 2027, excluding the 53rd week, despite softness in Asia. Streaming subscription revenue grew double digits. Management also quantified its efficiency program for the first time, targeting roughly $3 billion in run-rate savings by fiscal 2029 after only qualitative references earlier in the year.
The tension is where those savings go. Most will be reinvested, and content spending is set to rise 9% to about $26 billion in fiscal 2027 from about $24 billion. Earlier in the year, management laid out an explicit streaming margin ramp: a 10% target in Q1, double digits reached in Q2, and 13% in Q3. That ramp has now softened into margin improvement "over time." Disney will also stop disclosing streaming operating income starting in Q1 of fiscal 2027, removing that visibility just as profitability had become a selling point. Bears have legitimate ammunition here. The company is also flagging consumer weakness in Shanghai and Hong Kong that should persist into next year, streaming ad pricing pressure from added supply, and cruise pre-opening costs amid uncertain Asian demand.
The catalyst slate is deep:
- the unified Disney+/Hulu app in December;
- Avengers: Doomsday on December 18, with strong early presales;
- TikTok creator content and a possible free, ad-supported tier on Disney+;
- expanded exclusive College Football Playoff rights (23 games versus 11);
- ESPN's first Super Bowl in February;
- 2027 park openings, including Monstropolis and Tropical Americas.
On guidance, the supplied sources conflict. The Earnings Whispers note characterizes the report as a raise, but the release and call show the double-digit fiscal 2027 adjusted EPS growth target was reiterated rather than lifted. The new element is the Experiences outlook.
The market setup is more demanding than the surprise implies. Investor sentiment moved from slightly negative (-0.05) to modestly positive (+0.17) ahead of the report, a meaningful shift toward optimism. Shares were at $118.70 on the eve of earnings, up 16.4% since the open after the August report. That left the stock 14.3% above its 200-day moving average and within 1.7% of the $120.80 52-week high set on November 5. Price, momentum, and AVWAP trend readings are positive, while sequential growth is only neutral. That split fits a stock that has rallied faster than the clean, ex-53rd-week growth rate.
The bottom line is that Disney delivered a genuine beat, healthier parks demand, and a credible path to double-digit earnings growth in fiscal 2027. However, the extra week inflated the quarter, the EPS outlook was held rather than raised, and the streaming story has moved from visible margin gains toward reinvestment with less disclosure. With the stock near its highs and sentiment improved, the bar has risen. Execution on the content cycle and the cost program now matters more than the headline beat.
Read our earnings preview for The Walt Disney Company: https://www.earningswhispers.com/article/DIS/23094
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours |
