Target's Sales Momentum Accelerates, But A Whisper Shortfall And Tariff-Refund Noise Complicate The Beat
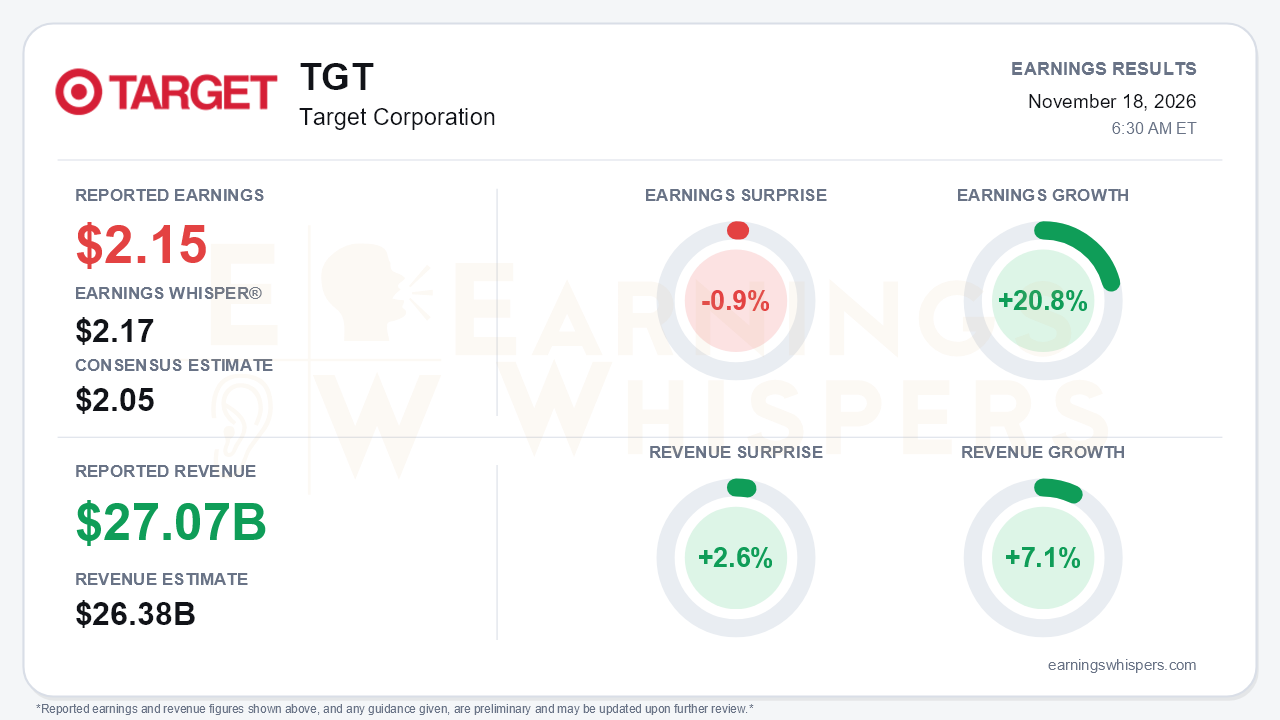
Target's (NYSE: TGT) fiscal third quarter was driven by sales, not earnings. On Earnings Whispers' normalized basis, which strips out $0.50 per share of tariff refunds, Target earned $2.15 per share. That cleared the $2.05 consensus but fell 0.9% short of the $2.17 Earnings Whisper number. Revenue of $27.07 billion beat the $26.38 billion consensus by 2.6% and grew 7.1% year over year, up from 5.3% growth in the second quarter. Normalized earnings grew 20.8%. Reported GAAP and adjusted EPS was $2.65, but that figure includes $301 million of pretax refunds under the International Emergency Economic Powers Act (IEEPA). Investors should anchor on the lower number. The central tension is that the top line is accelerating more convincingly than the bottom line, and the most optimistic investors wanted a bit more profit from it.
The quality of the revenue is hard to fault. Comparable sales rose 5.6%, and comparable traffic accounted for 5.0 points of that, up from 3.6% traffic growth in the second quarter. Store comps improved to 4.6% from 2.7%, and digital comps reached 9.8%. Non-merchandise sales jumped 19.3%, with Roundel advertising revenue up to $296 million from $241 million. That high-margin stream supported gross margin, which expanded roughly 120 basis points excluding refunds after a roughly 100-basis-point gain in Q2. The weak spot is expenses. Adjusted SG&A rose about 10%, faster than the roughly 7% pace in the first half, on higher incentive compensation, extra store labor hours, and store investments. As a result, the adjusted SG&A rate rose to 21.9% from 21.3%, even with strong sales leverage. Freight, fuel, price investment, and mix also offset part of the gross margin gains. That helps explain why a revenue beat of this size produced only a modest earnings surprise.
The conference call showed a business gaining breadth and a management team gaining confidence. Fun 101 grew nearly 27%, Beauty more than 9%, and Food and Beverage nearly 7%. Home turned to a positive comp, and an early bedding reset produced double-digit comps. Management's tone moved from first-quarter caution ('one quarter doesn't make a trend') to describing the strategy as working as designed. The full-year net sales outlook rose for a third straight time, to about 6%, from roughly 2% at the March financial community meeting. Target also resumed buybacks, repurchasing $251 million of stock with a similar amount planned for Q4. It guided 2027 capital spending to $5 to $6 billion, up from about $5 billion this year, citing strong returns on new stores and remodels.
Bears still have legitimate ammunition. The updated EPS range of $10.65 to $11.40 includes about $2.14 of refunds recognized to date. The prior range of $9.90 to $10.90 included $1.65 of refunds. Much of the guidance increase therefore reflects refund benefits rather than operating upside, which fits the framing that guidance was raised while earnings remain in line with estimates. The call summary says the range was not restated on the call itself, so the new figures came from the release. Refunds also inflate trailing return on invested capital by 3.0 points and muddy the 2027 earnings base. Other risks include:
- **Inventory:** up about 8% year over year to $16.1 billion, versus 3% growth in Q2, which raises markdown exposure if holiday demand disappoints.
- **Apparel:** sales fell to $3.69 billion from $3.84 billion, with women's fashion and shoes not expected to improve before spring 2027.
- **Trading cards:** they drove about 40% of Fun 101 growth year to date, setting up a difficult 2027 comparison.
- **Credit card income:** management attributed much of its strength to timing.
- **Holiday trends:** sales slowed in October. November is tracking in line with guidance and accelerating, but the holiday outcome remains open.
The market setup is more complicated than the revenue surprise implies. Shares closed at $159.53 the day before the report. That is up 7.9% from the open after the August release and 16.4% above the 200-day moving average. However, the stock sits 6.6% below the $170.75 52-week high set on August 24, shortly after the prior report, and had dropped to $145.32 in late October before recovering. Investor sentiment stayed positive but softened slightly, from 0.22 to 0.19, which suggests expectations were not euphoric. Momentum and AVWAP trend readings remain positive, while the price trend is neutral.
The bottom line is that Target delivered a credible acceleration story: traffic-led comps, broadening category strength, a third sales-guidance increase, and enough confidence to raise capital spending and resume buybacks. Earnings quality is the caveat. Excluding tariff refunds, profit fell slightly short of the whisper, expenses are growing faster, and inventory is building ahead of a holiday season management has not yet secured. The demand story has improved more clearly than the earnings story.
Read our earnings preview for Target Corporation: https://www.earningswhispers.com/article/TGT/23131
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 3 hours |
IBD Stock Of The Day Target Breaks Out As Sales Soar In Beat-And-Raise Quarter
TGT +4.03%
Investor's Business Daily
|
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours |
Target Gets $301 Million Tariff Refund Boost. Sales Jump 7.1%.
TGT +4.03%
International Business Times
|
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours |
