TJX Tops Consensus But Misses The Whisper As Freight Costs Undercut A Marmaxx Recovery
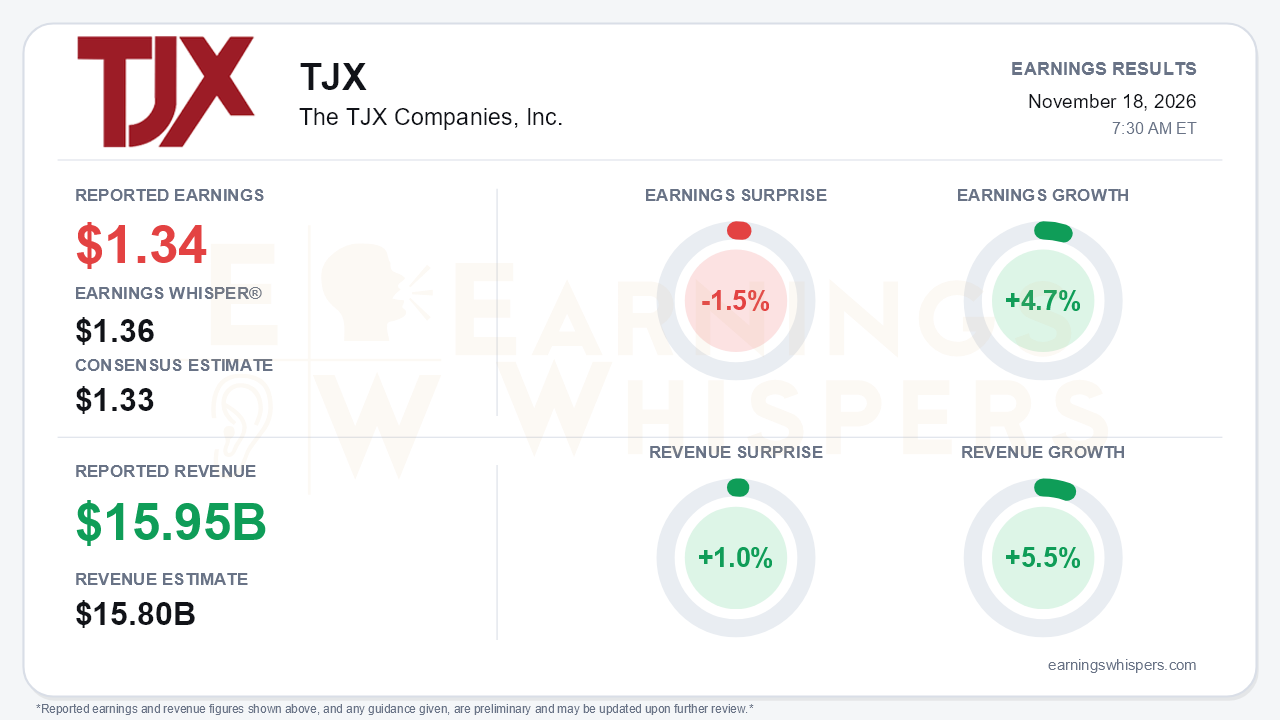
TJX delivered the quarter it promised on the top line, but not the one the most demanding investors wanted on earnings. Adjusted EPS of $1.34 edged past the $1.33 consensus. It fell short of the $1.36 Earnings Whisper, a 1.5% miss against that higher bar. Revenue of $15.95 billion beat the $15.80 billion consensus by 1.0% and grew 5.5% year over year, while adjusted earnings rose 4.7%. The central tension is that demand is improving where it matters most, at Marmaxx, while margins are moving the other way. The fourth-quarter outlook absorbs higher fuel costs that push profit guidance below where it stood three months ago.
The quality of the beat deserves scrutiny. GAAP EPS of $1.39 rose 9%, but that figure includes a $0.05 net benefit from IEEPA tariff refunds. Stripping that out, adjusted pretax margin fell 20 basis points to 12.5%. Adjusted gross margin dropped 50 basis points to 32.1% on higher freight and fuel costs. The offset came from SG&A, which levered 30 basis points largely because of lower incentive compensation accruals and lapping a prior-year TJX Foundation contribution. Neither of those is a durable operating driver.
Growth is also decelerating against the year-to-date pace. Nine-month adjusted EPS is up 14% and sales are up 7%, so the third quarter's mid-single-digit profit growth marks a clear step down. Consolidated comps of 4% also trailed the prior year's 5%, even though they beat the company's 2% to 3% plan.
Beneath the headline, the divisional mix shifted in both directions. Marmaxx comps improved to 2% from 1% in the second quarter, with apparel and home both better sequentially and a stronger finish to the period. Management said execution issues should be largely behind it by year-end and expects further improvement in the fourth quarter. Still, Marmaxx transactions were essentially flat, and its adjusted segment margin fell 110 basis points to 13.8%, hurt by expedited freight.
HomeGoods comps decelerated again, to 5% from 7% in the second quarter and 9% in the first. International was the standout, with comps accelerating to 8% from 7% and 4%. Canada held at 6% with adjusted segment margin up 120 basis points.
Guidance captures the split. Full-year sales guidance rose for a third straight call, to $63.8 billion to $64.0 billion, and the full-year comp outlook firmed to 4%. The adjusted EPS range moved to $5.17 to $5.20, with only the low end rising. Full-year adjusted pretax margin of 12.0% to 12.1% was merely maintained after raises earlier in the year.
Fourth-quarter adjusted EPS guidance of $1.42 to $1.45 sits below the roughly $1.44 to $1.47 implied on the prior call. Adjusted pretax margin guidance of 11.8% to 11.9% is down from about 11.9% to 12.0%, and the outlook was described as below estimates. Management cited additional fuel costs and said freight contracts were renewed at higher rates, with driver shortages possibly carrying pressure into fiscal 2028. Unseasonably warm weather has also held back early holiday demand, and some competitors are cutting prices, prompting TJX to respond.
The bullish counterweights are real. Management described closeout availability as exceptional, saying markets are flooded with goods. It is increasing holiday marketing and reaffirmed 4% annual unit growth toward a 7,500-store long-term target. The balance sheet also remains a source of support: TJX retired a $1.0 billion note, returned $1.5 billion to shareholders in the quarter, and now plans about $3.0 billion in fiscal 2027 buybacks.
Investors had already turned cautious. Earnings Whispers sentiment swung from modestly positive at 0.148 to modestly negative at -0.126, a meaningful shift in tone. Shares are down 9.9% since opening at $144.14 after the August report. At $129.85, they sit 13.6% below the $150.27 200-day moving average and 13.7% beneath the inter-earnings high set on that report day. The stock set a 52-week low of $122.78 in mid-September and has recovered only 5.8% from it. Price and AVWAP trend readings remain negative even as sequential growth reads positive, which fits a market that has been discounting margin risk ahead of the numbers.
The bottom line is that TJX preserved a credible growth story, supported by an improving Marmaxx, accelerating international comps and a third consecutive sales-guidance raise. The earnings side of the story is weakening, however. Adjusted margins are contracting on freight and fuel, SG&A help came from non-recurring sources, and the fourth-quarter profit outlook moved lower. With the stock already well below its 200-day average and sentiment turned negative, the next leg likely depends on whether holiday sales accelerate enough to outrun cost pressure that management itself expects to persist.
Read our earnings preview for The TJX Companies, Inc.: https://www.earningswhispers.com/article/TJX/23132
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 5 hours | |
| 7 hours | |
| 7 hours |
TJ Maxx Parent TJX Raises Annual Sales Outlook as It Bets on Strong Holiday Demand
TJX +8.05%
International Business Times
|
| 8 hours | |
| 8 hours | |
| 9 hours | |
| 10 hours | |
| 11 hours | |
| 11 hours |
TJX Raises Full-Year Outlook, Expects Sales Trends to Accelerate Through Holiday Season
TJX +8.05%
The Wall Street Journal
|
| 11 hours | |
| 13 hours | |
| 14 hours | |
| 14 hours | |
| Nov-17 |
