Buy the Spike in Target (TGT) Stock After Strong Q3 Earnings?
Shares of retail giant Target TGT) have surged as much as 7% in Wednesday's trading session after delivering stronger-than-expected Q3 results and guidance, making the company a bright spot in this week's highly anticipated earnings lineup.
This comes as turmoil around Nvidia's NVDA) leadership transition has overshadowed its impressive quarterly results, while investors await Walmart's WMT) Q3 report on Thursday for further insight into consumer spending trends.
With Target stock gaining momentum and now up 75% year to date, let's examine whether its latest earnings beat and upbeat outlook make TGT a compelling buy.
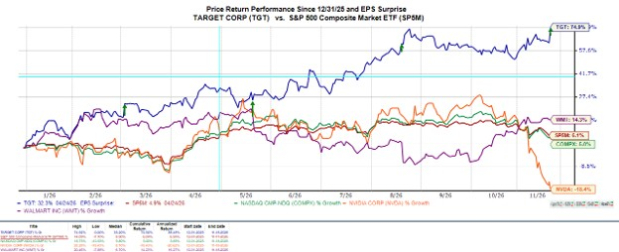
Image Source: Zacks Investment Research
Target's Strong Q3 Results
Target reported Q3 adjusted earnings of $2.65 per share, surging 49% year over year and crushing Wall Street expectations of $2.05 by 29%.
Notably, Q3 earnings benefited from $0.50 per share in tariff refunds, although adjusted EPS still increased 21% YoY to $2.15 excluding this benefit and reflected a nearly 5% earnings surprise.
Quarterly sales rose 7% to $27.07 billion, exceeding estimates of $26.36 billion. Encouragingly, comparable sales increased over 5%, driven by a 5% rise in customer traffic, with digital comparable sales jumping nearly 10%. Strength in electronics, beauty, and food and beverage helped drive broad-based growth.
It’s also noteworthy that Target’s gross margin expanded to 30.5% from 28.2% a year ago, with margins still improving by approximately 120 basis points excluding tariff refunds.
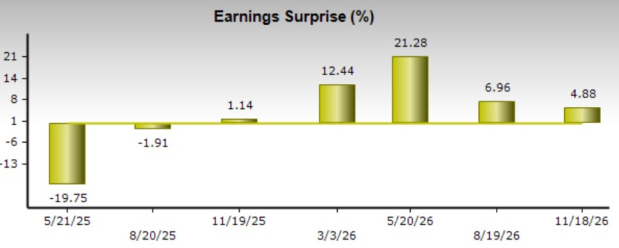
Image Source: Zacks Investment Research
Target Raises FY26 Guidance
More importantly, Target raised its full-year sales growth outlook to approximately 6%, up from its previous forecast of 5%.
Management also increased its adjusted EPS guidance to $10.65-$11.40 (+40% YoY growth), compared with its prior projection of $9.90-$10.90. However, the updated outlook includes approximately $2.14 per share in tariff refund benefits recognized this year.
Looking ahead, Target expects to invest $5-$6 billion in capital expenditures during 2027 to support sustained growth, while improving sales trends heading into the critical holiday shopping season provide additional optimism.
Bottom Line: Is TGT Stock Still a Buy?
Benefiting from a trend of positive earnings estimate revisions that could extend following its impressive Q3 report and raised guidance, Target looks well-positioned to retain its Zacks Rank #2 (Buy).
While the contribution from tariff refunds warrants some caution, Target's strengthening underlying sales trends and improving outlook support its investment appeal even after Wednesday's rally.
Furthermore, TGT remains attractive at a reasonable 15X forward earnings multiple while offering a dividend yield of nearly 3%, making the stock appealing to both value and income investors.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Target Corporation (TGT): Free Stock Analysis Report
Walmart Inc. (WMT): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 24 min | |
| 37 min | |
| 40 min | |
| 47 min |
Wall Street Pledged to Mobilize $500 Billion for Nvidia-But Hasn't Put Up a Dime
NVDA
The Wall Street Journal
|
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours |
