Deere's Fourth Quarter Must Prove Fiscal 2026 Was The Bottom Of The Farm Cycle
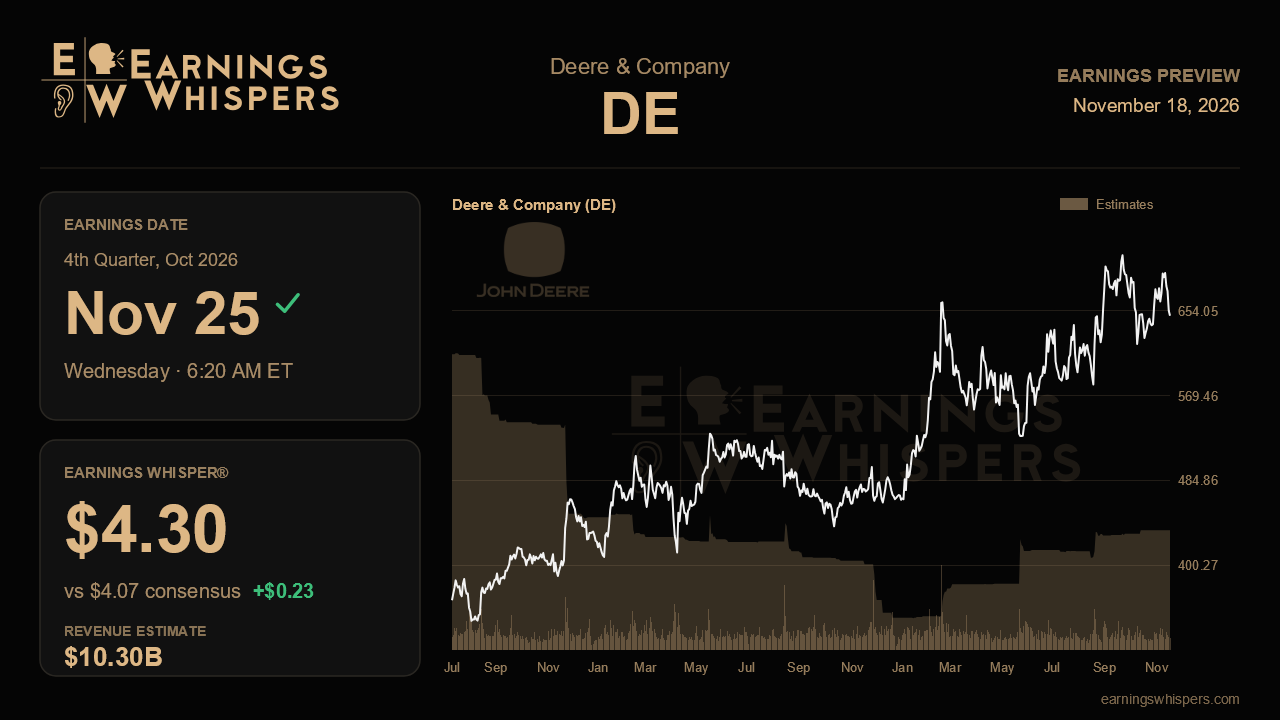
Deere enters its fiscal fourth-quarter report with a claim to defend. Three months ago management raised its full-year profit outlook, pointed to a strong order book across every segment, and offered the first hard evidence that 2026 marks the trough of the agricultural cycle: model year 2027 early orders for large equipment running up by mid-single digits. The November 25 release, due before the open, is where that confidence either becomes a recovery story or gets pushed back another season.
The Street is looking for earnings of $4.07 per share, up 3.6% from $3.93 a year ago, on revenue of about $10.30 billion, a decline of roughly 17%. That split is the crux of the quarter. Analysts expect Deere to grow profits while selling meaningfully less, which leans heavily on pricing, cost discipline and a lighter tariff bill. The whisper number of $4.30 sits noticeably above consensus, a sign that some investors expect another round of execution ahead of the published forecasts. For the full year, management's latest guidance calls for $17.55 to $18.47 per share, and consensus of $18.21 sits in the upper half of that range. The bar is not heroic, but it already assumes Deere finishes strong.
The previous call explained how that could happen. Small agriculture and turf has been the standout, with full-year sales now seen up about 15% and a third-quarter margin of 18.4%, comfortably above the raised 14.5% to 15.5% segment target. Construction and forestry is the other support beam, with North American industry demand lifted to growth of 5% to 10%, third-quarter sales up 18% on eight points of price, and backlogs stretching well into fiscal 2027 on data center, infrastructure and pipeline work. Continued strength in both, alongside a financial services unit whose profit outlook has crept higher every quarter, would validate management's argument that diversification is cushioning the large-ag downturn.
The weak link remains Production and Precision Agriculture. Its sales outlook drifted to the bottom of guidance at roughly down 10%, and its margin range was trimmed to 11% to 12%. South America has been cut at every turn, from flat to now down 15% to 20%, and Europe's arable farmers are showing fresh strain. A further slide there, or a construction margin landing at the low end of its tightened 10.5% to 11.5% band, would challenge the notion that the worst is fully priced in. Tariffs are another swing factor: Deere assumed no additional refunds in the fourth quarter and flagged net tariff costs rising to about $1 billion next year from roughly $750 million, so any commentary on mitigation matters as much as the quarter itself.
The market has already leaned toward the optimistic reading. Shares have gained 6.2% since the last report while the S&P 500 fell 4.4%, a 10.6-point margin of outperformance, and sentiment has warmed modestly to 22.8% bullish from 18.6% heading into the prior quarter. At about $649, the stock trades above its 200-day average near $613 but roughly 10% below its post-earnings high of $721, suggesting investors have bought the bottoming thesis without fully pricing a robust upswing.
That leaves the forward view as the decisive piece. A clean beat helps, but the report will be judged on whether the early order momentum, rising See & Spray adoption and the construction backlog translate into a credible case for growth in fiscal 2027 that can absorb the heavier tariff bill. If management can show large ag stabilizing while small ag and construction hold their gains, the trough narrative stays intact. If South America and Europe keep deteriorating, the recovery timeline slips, and the stock's outperformance becomes harder to justify.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-18 | |
| Nov-18 | |
| Nov-15 | |
| Nov-14 | |
| Nov-11 | |
| Nov-11 | |
| Nov-10 | |
| Nov-06 | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-21 | |
| Oct-16 | |
| Oct-13 |
