Palo Alto Networks Beats And Raises On Accelerating Growth, But The Applied Compute Deal Complicates The Margin Story
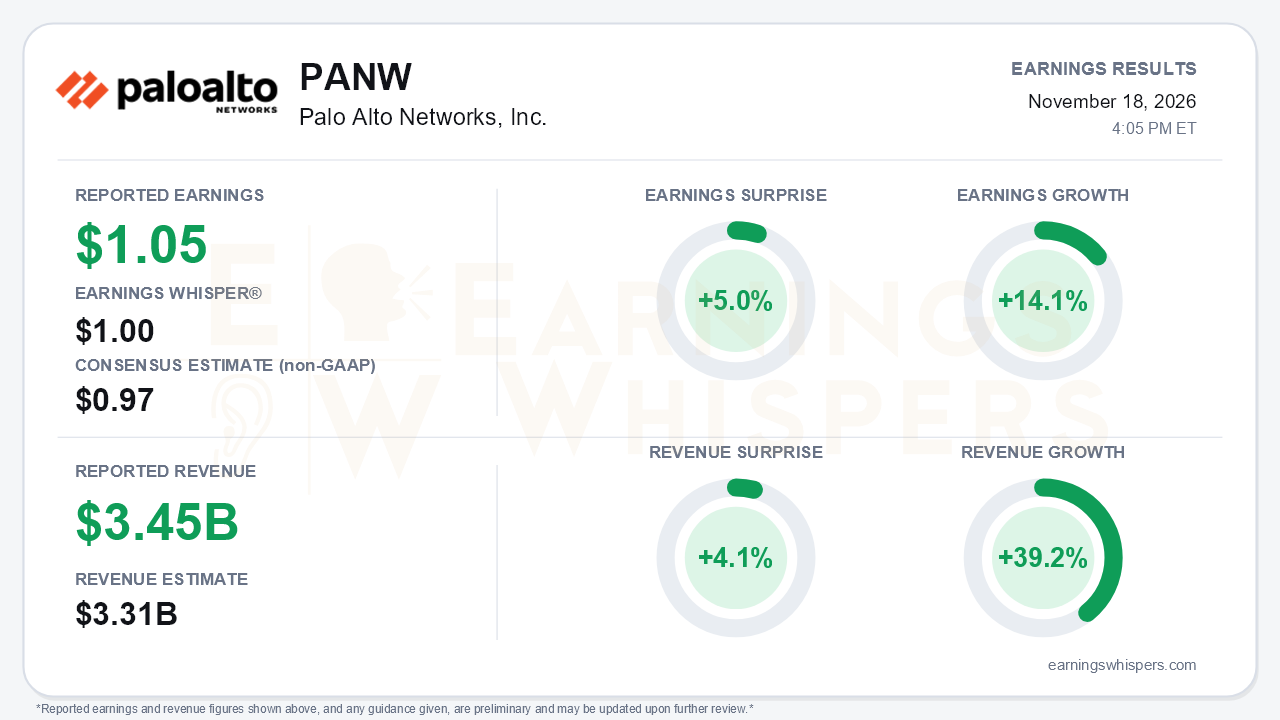
Palo Alto Networks opened fiscal 2027 with a clean beat and a substantial guidance raise. That is the easy part of the story. The harder part is that management paired its strongest growth quarter in years with a $4.5 billion all-stock bet on AI compute, which will dilute margins and requires heavy capital spending. Non-GAAP earnings of $1.05 per share topped the $0.97 consensus by 5.0% and cleared the $1.00 Earnings Whisper number. Revenue of $3.445 billion beat the $3.31 billion consensus by 4.1%. Revenue grew 39.2% year over year, accelerating from 34% in fiscal Q4, 31% in Q3 and 15% in Q2.
The quality of the beat deserves some scrutiny, mainly because of the gap between revenue and earnings growth. Revenue grew 39.2%, but earnings per share grew only 14.1%. The main reason is dilution from the CyberArk deal: diluted share count jumped from 709 million to 838 million. Inorganic contribution also inflates the headline growth rate. Cortex grew 53% as reported but 40% on a pro forma basis.
GAAP results need context too. GAAP operating income fell to $96 million from $309 million, weighed down by $622 million of share-based compensation and $282 million of acquired-intangible amortization. GAAP net income still rose to $482 million, or $0.57 per share, but only because of a $457 million tax benefit tied to a one-time change in a historical tax position.
Gross margin is another soft spot. It slipped to 75.2%, down 170 basis points, on:
- hardware component costs;
- a heavier SaaS mix;
- the Prisma-to-Cortex Cloud migration.
Non-GAAP operating margin still edged up 50 basis points to 30.7%. Adjusted free cash flow of $1.9 billion was strong, although the 56.2% margin was down from 69.2% a year ago.
Beneath the acquisition noise, the operating trends are genuinely strong. Next-Generation Security ARR grew 66% to $9.73 billion, up from 63% in Q4 and 60% in Q3, and net new ARR more than doubled. Remaining performance obligations rose 35% to $21.0 billion. Current RPO of $9.4 billion grew 36%, and both measures accelerated. All three segments outran management's full-year frameworks:
- Network & AI Security grew 20%, against a low-double-digit framework.
- Cortex grew 40% pro forma, against a roughly 30% guide.
- IDERA grew 23% pro forma, against a high-teens-to-20% guide.
Newer platforms are scaling quickly. Prisma AIRS ARR reached about $170 million, up from just over $100 million a quarter earlier. XSIAM approached $800 million in ARR. Software firewall ARR growth accelerated for a third straight quarter, to 34%. The company also logged a record of roughly 170 platformizations.
Management's tone escalated, and it now calls the quarter a "defining inflection point." Management expects elevated patching volumes to persist for 18 months amid a roughly sevenfold surge in critical vulnerabilities. Guidance moved accordingly. Fiscal 2027 revenue is now $14.52 billion to $14.57 billion, up from $14.1 billion to $14.2 billion. Non-GAAP EPS guidance rose to $4.26 to $4.30 from $4.16 to $4.19, and the NGS ARR target climbed to 26% to 27% growth. The 29.5% operating margin and 38% free-cash-flow margin targets were reaffirmed.
The central tension is the Applied Compute acquisition, which is excluded from guidance. It adds only about $100 million of annualized revenue but carries several costs:
- up to 100 basis points of operating-margin dilution in fiscal 2027;
- up to 200 basis points in fiscal 2028;
- under $3 billion of GPU and server capex through fiscal 2030.
Those commitments push Palo Alto away from its capital-light model. Its free-cash-flow commitment is now framed as 38%-plus excluding data-center capex, a softer formulation than the prior 40% fiscal 2028 target. Management is targeting roughly $1 billion of added NGS ARR by fiscal 2029, plus 100-plus megawatts of sovereign inference capacity. That is a credible strategic logic, but it is also execution risk in an unfamiliar business, with possible channel friction among AI partners.
Bears have additional ammunition. Management acknowledged that some hardware demand reflects emergency budgets and buying pulled forward ahead of price increases. That suggests part of the network strength may be cyclical. Q2 guidance also implies modest deceleration, with ARR growth easing to 61% and revenue growth to 36% to 37%.
The market setup is more complicated than the surprise implies. Investor sentiment entered the report only mildly positive at 0.15. The stock had a rough inter-earnings stretch. It opened at $346 after the September report and ran to a 52-week high of $432.33 on October 6. It then slid to an inter-earnings low of $301.28 on November 17, the day before results, giving back roughly 30% from the peak. That low still sat above the 200-day moving average near $279. The Earnings Whispers trend readings are mixed, with momentum positive but AVWAP negative.
The bottom line is that Palo Alto delivered the kind of accelerating, broad-based quarter and raise that bulls wanted, and that should challenge the pre-report pessimism. Investors are now underwriting a different company, however. It is more capital-intensive, carries more dilution, and has margins that will step down before Applied Compute pays off. The core business looks stronger than the stock's slide implied. The debate now centers on whether the AI compute pivot earns its cost.
Read our earnings preview for Palo Alto Networks, Inc.: https://www.earningswhispers.com/article/PANW/23140
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 13 min | |
| 37 min | |
| 53 min | |
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 5 hours | |
| 8 hours | |
| 8 hours | |
| Nov-18 |
