Intuit Beats On QuickBooks Strength, But A Credit Karma-Driven Guidance Cut Defines The Quarter
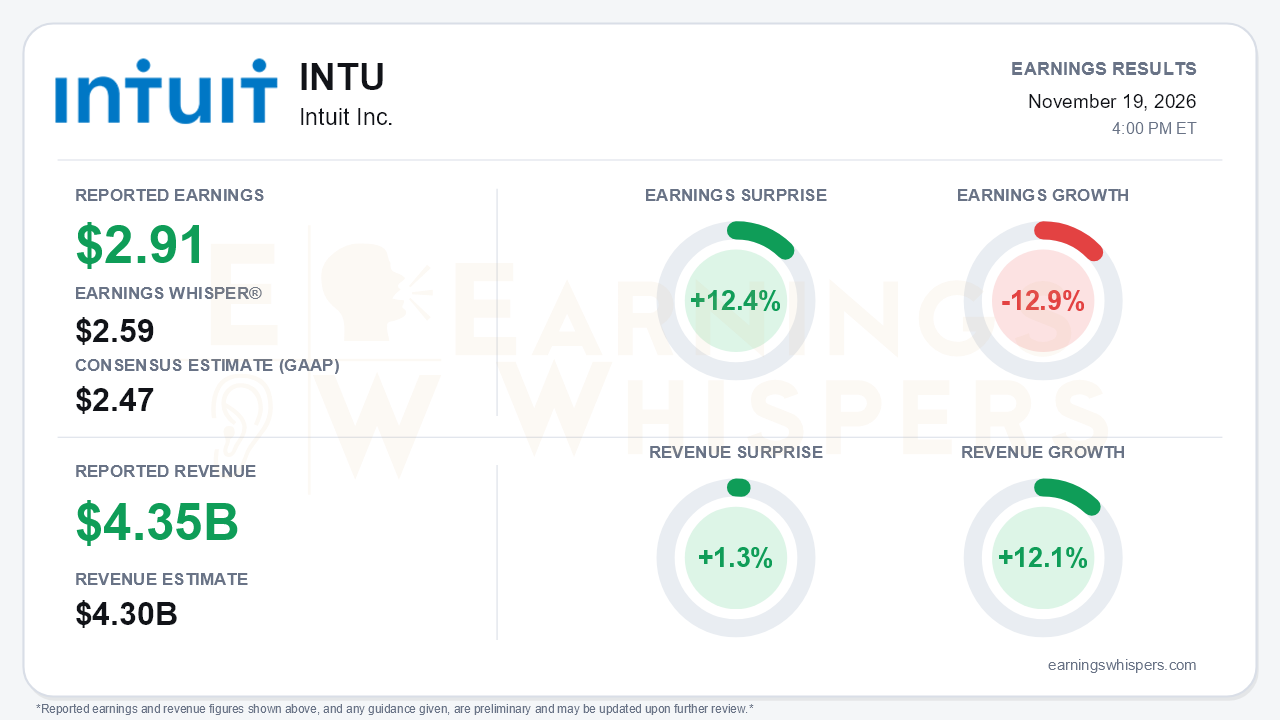
Intuit cleared the bar for its fiscal first quarter, but the more consequential news was a second straight downward reset to the revenue outlook. The company reported earnings of $2.91 per share on revenue of $4.354 billion. That topped the $2.47 consensus by 12.4% and the $2.59 Earnings Whisper number, while revenue beat the $4.30 billion consensus by 1.3% and grew 12.1% year over year. Results landed above the top end of management's guidance. Yet Intuit trimmed full-year fiscal 2027 revenue guidance to $23.08–$23.37 billion (8% to 9% growth) from $23.28–$23.51 billion (9% to 10%). It also guided the second quarter to just 6% to 7% revenue growth. The central tension is a stronger-than-expected small-business engine running alongside a consumer franchise that keeps losing altitude.
The earnings growth figures need careful reading. On Earnings Whispers' basis, earnings fell 12.9% year over year. Intuit's own figures show non-GAAP EPS up 56% to $2.91 and GAAP EPS up 63% to $2.59. The gap reflects a definitional change: starting this quarter, Intuit no longer excludes share-based compensation from its non-GAAP measures, and it restated prior periods on that basis. Under the new definition, the year-ago comparison was $1.87.
Beneath the headline, the quarter showed real cost discipline:
- Research and development fell to $788 million from $843 million.
- General and administrative expense declined to $382 million from $422 million.
- Share-based compensation dropped to $495 million from $543 million.
- Operating cash flow rose to $1.06 billion from $637 million.
GAAP results also got help from $119 million in investment gains, which non-GAAP EPS excludes.
The operating story is cleanly bifurcated. Global Business Solutions revenue grew 15% to $3.1 billion, and Online Ecosystem revenue rose 20%. QuickBooks Online Accounting grew 19%, and Online Services grew 21% on money and payroll. Mid-market momentum is accelerating rather than fading:
- Online ecosystem growth for QuickBooks Online Advanced plus Intuit Enterprise Suite reached 41%, up from 38% last quarter.
- Mid-market customer growth rose to 30% from 28%.
- Intuit Enterprise Suite annualized revenue reached $177 million, up from more than $145 million a quarter earlier.
- Business money total payment volume grew 33%.
The consumer side is where the guidance damage originated:
- Credit Karma grew 9%, down from 16% last quarter and 23% two quarters earlier.
- Management said Credit Karma fell short of internal plans on both revenue and engagement. It blamed higher interest rates and a faster-than-expected shift of consumer discovery toward AI and large-language-model tools.
- The full-year Credit Karma outlook was cut to 3% to 7% growth from 11% to 13%, and Consumer segment guidance fell to 2% to 4% from 4% to 6%.
- Gross margin stepped down sequentially and came in below Street expectations.
The AI explanation is the more troubling of the two, because it points to a structural threat to Credit Karma's acquisition funnel, not just a cyclical one.
The second-quarter guide sharpens that concern:
- Consumer revenue is expected to decline mid-single digits.
- TurboTax is expected to be down year over year, partly because roughly $30 million of refund-transfer revenue shifts into the third quarter.
- Desktop revenue is expected to flatten.
- A price-competitive DIY tax strategy is weighing on revenue per customer.
The result is a back-half-weighted plan that now depends heavily on tax-season execution. Management did reiterate full-year non-GAAP EPS guidance of $22.88 to $23.12, along with the GBS outlook of 13% to 14% growth. However, lower share-based compensation is part of what offsets the Credit Karma shortfall, so the earnings guidance holds partly through cost rather than revenue. The catalyst list is genuine but mostly longer-dated:
- AI distribution partnerships with Meta, Microsoft and SpaceX
- A QuickBooks connector already above a $1 billion payment-volume run rate
- The launch of Credit Karma Tax
- Intuit Accountant Suite growth to 430,000 accountants from 150,000
The Mailchimp sale to Bending Spoons for about $3.68 billion is the main structural change. Intuit will receive $3.31 billion in cash and the rest in Bending Spoons stock. The deal removes a business that shrank 1% this quarter and sharpens the focus on QuickBooks. Intuit plans to use the cash to buy back shares within fiscal 2027 after the deal closes. That would add to an already aggressive pace: Intuit repurchased $1.5 billion of stock this quarter, up 73% from a year earlier. Current guidance excludes the deal, so a revision is coming when it closes in early calendar 2027, assuming regulatory approval.
Investors were not leaning optimistic going in. Earnings Whispers sentiment slipped modestly further into negative territory, to -0.30 from -0.26. Shares entered the report at $313.24, down 3.2% from the open after the August report and about 10% below the 200-day moving average. The stock had rallied from a September 28 low of $262.32 to a November 4 high of $366.47, then given back roughly 14.5% of that peak before the print. Momentum and AVWAP readings remain negative, consistent with a stock that has struggled to hold rallies.
The bottom line is that Intuit delivered a clean beat and a genuinely improving mid-market business, but bears have legitimate ammunition. A second consecutive cut to revenue guidance, a Credit Karma slowdown tied partly to AI-driven disruption, and a soft consumer-heavy second quarter mean the growth story increasingly rests on QuickBooks, tax-season execution and buybacks.
Read our earnings preview for Intuit Inc.: https://www.earningswhispers.com/article/INTU/23180
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours |
Intuit Beats Fiscal Q1 Goals, Gives Soft Outlook, Sells Mailchimp
INTU INTU -9.77% AH
Investor's Business Daily
|
| 5 hours | |
| 9 hours | |
| 15 hours | |
| 16 hours | |
| 17 hours | |
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-17 |
