Reasons to Include Curtiss-Wright Stock in Your Portfolio Right Now
Curtiss-Wright Corp. CW benefits from rising commercial nuclear aftermarket sales and consistent shareholder-focused initiatives that have played a pivotal role in strengthening the company’s overall performance. Given its significant growth, CW is a good investment opportunity in the Zacks Aerospace Defense Equipment industry.
Let us focus on the factors that make this Zacks Rank #2 (Buy) company a strong investment pick at the moment.
Growth Outlook & Surprise History of CW
The Zacks Consensus Estimate for CW’s 2025 earnings per share (EPS) has increased 1.8% to $12.86 per share over the past 30 days.
The Zacks Consensus Estimate for Curtiss-Wright’s 2025 revenues stands at $3.42 billion, which indicates growth of 9.5%.
The company’s long-term (three to five years) earnings growth rate is 12.5%. CW surpassed expectations in the last four reported quarters and delivered an average earnings surprise of 9.34%.
Curtiss-Wright’s Return on Equity
Return on equity (ROE) indicates how efficiently a company utilizes funds to generate higher returns. Currently, Curtiss-Wright’s ROE is 18.34%, higher than the industry average of 8.29%. This indicates that the company has been utilizing funds more constructively than its peers in the aerospace defense equipment industry.
CW’s Shareholder-Friendly Actions
CW has been increasing its shareholder value through regular dividend payments. Currently, the company’s quarterly dividend is 24 cents per share, resulting in an annualized dividend of 96 cents. The company’s current dividend yield is 0.20%, better than the industry's average of 0.16%.
Debt Structure of CW
Currently, Curtiss-Wright’s total debt to capital is 26.11%, much better than the industry’s average of 51.51%.
CW’s times interest earned ratio (TIE) at the end of the second quarter of 2025 was 14.2. The ratio, being greater than one, reflects the company’s ability to meet future interest obligations without difficulties.
CW’s Nuclear Operations Remain Strong
The United States continues to be a key market for Curtiss-Wright’s nuclear power growth. In the second quarter of 2025, the company saw a sharp increase in commercial nuclear aftermarket sales.
CW is actively working with designers of reactors exceeding 300 megawatts to secure roles in developing essential systems and equipment, positioning itself for sustained growth in both the U.S. and global nuclear markets.
CW Stock Price Performance
In the past six months, Curtiss-Wright stock has rallied 44.8% compared with the industry’s growth of 22%.
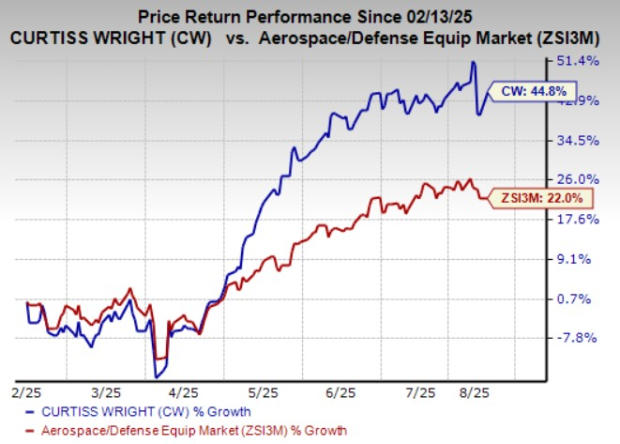
Image Source: Zacks Investment Research
Other Stocks to Consider
A few other top-ranked stocks from the same industry are Sky Harbour Group SKYH, Woodward, Inc. WWD and Moog Inc. (MOG.A), each carrying a Zacks Rank #2 at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
SKYH delivered an average earnings surprise of 7.41% in the past four quarters. The Zacks Consensus Estimate for the company’s total revenues for 2025 stands at $31.1 million, which indicates year-over-year growth of 110.5%.
Woodward’s long-term earnings growth rate is 13.9%. The Zacks Consensus Estimate for WWD’s fiscal 2025 sales is pegged at $3.48 billion, which implies an improvement of 4.8%.
Moog delivered an average earnings surprise of 12.20% in the past four quarters. The Zacks Consensus Estimate for the company’s total revenues for fiscal 2025 stands at $3.78 billion, which suggests year-over-year growth of 4.8%.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Curtiss-Wright Corporation (CW): Free Stock Analysis Report
Woodward, Inc. (WWD): Free Stock Analysis Report
Moog Inc. (MOG.A): Free Stock Analysis Report
Sky Harbour Group Corporation (SKYH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| Sep-21 | |
| Sep-16 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-10 | |
| Sep-09 | |
| Sep-08 | |
| Sep-02 | |
| Sep-02 | |
| Sep-01 | |
| Aug-31 | |
| Aug-26 | |
| Aug-19 | |
| Aug-18 |
