3 Reasons TFSL is Risky and 1 Stock to Buy Instead
TFS Financial trades at $13.89 and has moved in lockstep with the market. Its shares have returned 6% over the last six months while the S&P 500 has gained 8.1%.
Is there a buying opportunity in TFS Financial, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think TFS Financial Will Underperform?
We're cautious about TFS Financial. Here are three reasons you should be careful with TFSL and a stock we'd rather own.
1. Net Interest Income Points to Soft Demand
While bank generate revenue from multiple sources, investors view net interest income as a cornerstone - its predictable, recurring characteristics stand in sharp contrast to the volatility of one-time fees.
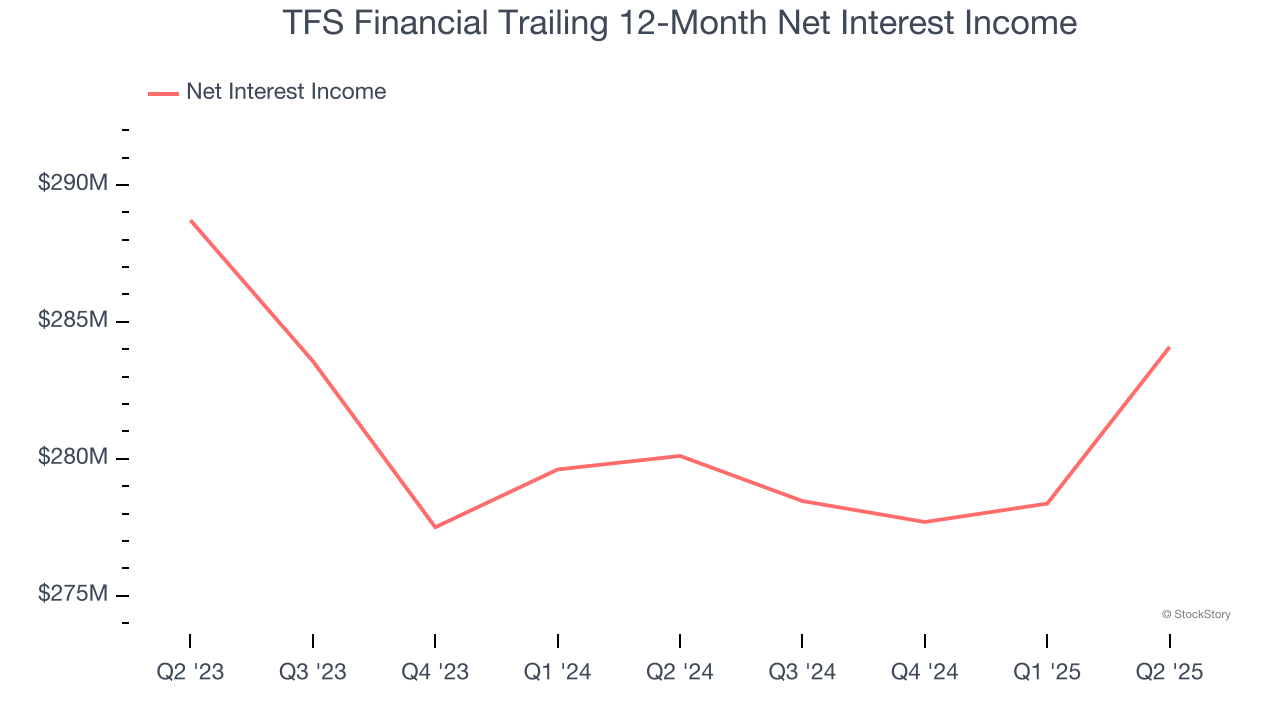
TFS Financial’s net interest income has grown at a 2.8% annualized rate over the last five years, much worse than the broader banking industry. Its growth was driven by both an increase in its outstanding loans and net interest margin, which represents how much a bank earns in relation to its outstanding loan book.
2. Low Net Interest Margin Reveals Weak Loan Book Profitability
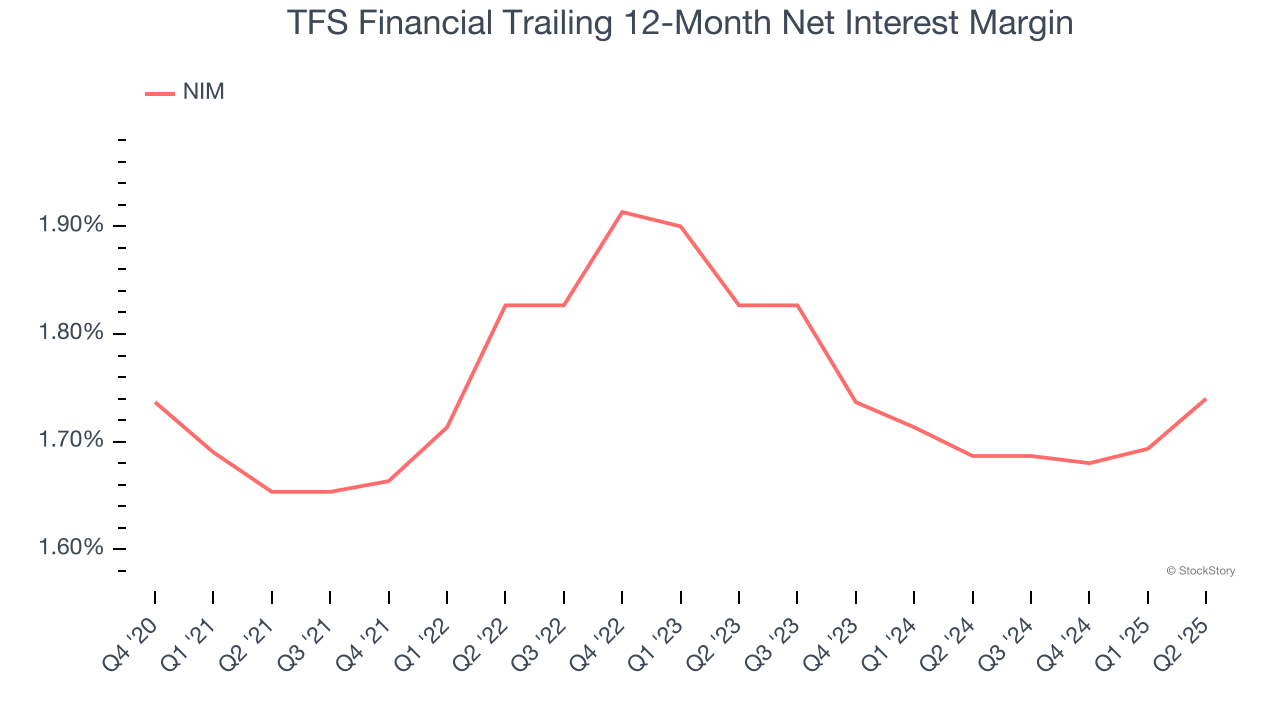
Net interest margin (NIM) represents how much a bank earns in relation to its outstanding loans. It's one of the most important metrics to track because it shows how a bank's loans are performing and whether it has the ability to command higher premiums for its services.
Over the past two years, we can see that TFS Financial’s net interest margin averaged a poor 1.7%, meaning it must compensate for lower profitability through increased loan originations.
3. TBVPS Has Plateaued, Reflecting Stagnating Assets
In the banking industry, tangible book value per share (TBVPS) provides the clearest picture of shareholder value, as it focuses on concrete assets while excluding intangible items that may not hold value during challenging times.
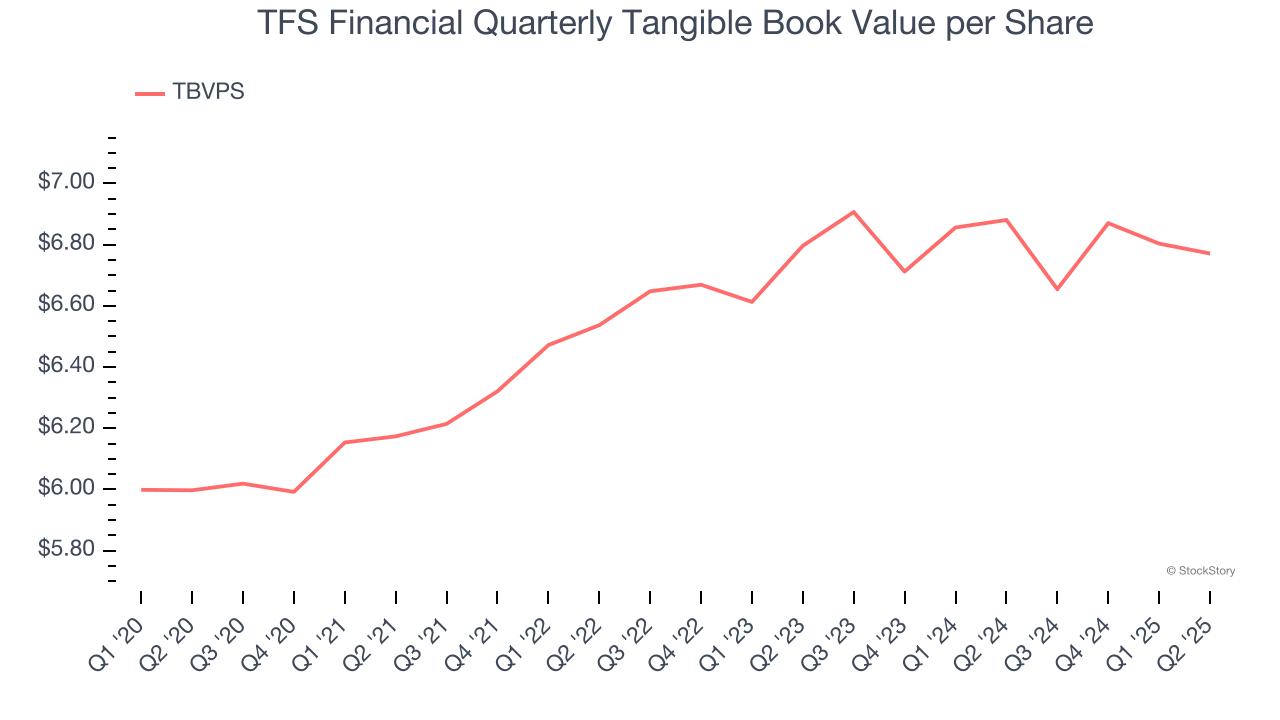
TFS Financial’s TBVPS increased by a meager 2.5% annually over the last five years, and its recent performance paints an even worse picture as growth has stalled over the past two years, with TBVPS stuck at roughly $6.77 per share.
Final Judgment
We cheer for all companies supporting the economy, but in the case of TFS Financial, we’ll be cheering from the sidelines. That said, the stock currently trades at 2× forward P/B (or $13.89 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - we think there are better stocks to buy right now. Let us point you toward one of our all-time favorite software stocks.
High-Quality Stocks for All Market Conditions
When Trump unveiled his aggressive tariff plan in April 2025, markets tanked as investors feared a full-blown trade war. But those who panicked and sold missed the subsequent rebound that’s already erased most losses.
Don’t let fear keep you from great opportunities and take a look at Top 5 Strong Momentum Stocks for this week. This is a curated list of our High Quality stocks that have generated a market-beating return of 183% over the last five years (as of March 31st 2025).
Stocks that made our list in 2020 include now familiar names such as Nvidia (+1,545% between March 2020 and March 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,754% five-year return). Find your next big winner with StockStory today.
StockStory is growing and hiring equity analyst and marketing roles. Are you a 0 to 1 builder passionate about the markets and AI? See the open roles here.
Mentioned In This Article
Latest News
| Sep-09 | |
| Aug-27 | |
| Jul-30 | |
| Jul-30 | |
| Jun-22 | |
| May-28 | |
| May-26 | |
| Apr-30 | |
| Apr-30 | |
| Apr-02 | |
| Mar-25 | |
| Mar-10 | |
| Mar-03 | |
| Feb-26 | |
| Feb-18 |
