Altria Oral Tobacco Margins Hit 69%: Pricing Power or Mix Shift?
Altria Group, Inc.’s (MO) oral tobacco business delivered a standout margin performance in the third quarter of 2025, with adjusted operating company income margins rising 2.4 percentage points to 69.2%. That lift came even as segment revenues declined and overall shipment volumes fell 9.6%, reflecting retail share pressure, calendar timing and trade inventory dynamics. The key question is what drove this margin expansion: pricing power or mix?
The data points more to pricing decisions than product mix. Altria increased prices, which helped offset the impact of selling more on!, its oral nicotine pouch brand. While many brands in the pouch category lowered prices through heavy promotions, Altria exhibited strong pricing discipline, with on!'s average retail price actually increasing slightly.
Management noted that the quarter included a “mix change,” with a higher percentage of on! relative to moist smokeless tobacco. Despite that shift, the segment still delivered margin expansion, supported by higher pricing and lower costs. In other words, the margin lift came from execution, pricing discipline and cost control, rather than from the mix of products alone.
Overall, Altria’s 69% oral tobacco margin reflects effective pricing and cost control in a competitive environment. While the continued shift toward pouches bears watching, the quarter demonstrated that the company is currently able to sustain profitability through disciplined execution.
Where PM and TPB Stand Next to Altria in Oral Nicotine
Philip Morris International Inc. (PM) reported strong momentum in its modern oral portfolio in the third quarter of 2025, driven primarily by ZYN’s continued volume growth. The company noted that retail share gains were supported by distribution expansion and increased brand visibility. At the same time, Philip Morris highlighted ongoing investments in capacity and commercialization, which remain necessary to support category growth. These efforts helped reinforce Philip Morris’ positioning in the fast-growing oral nicotine segment.
Turning Point Brands, Inc. (TPB) continued to scale its modern oral portfolio, reporting nearly eightfold year-over-year growth in modern oral revenues to $30.1 million in the second quarter of 2025. The expansion was driven by the FRE pouch line and supported by stronger contributions from the Stoker’s segment. Despite elevated marketing and distribution investments, Turning Point Brands maintained cost discipline and margin focus. As a result, Turning Point Brands remains positioned for steady category participation and improving profitability.
Altria’s Price Performance, Valuation & Estimates
Shares of Altria have lost 12.5% in the past month compared with the industry’s decline of 5.7%.
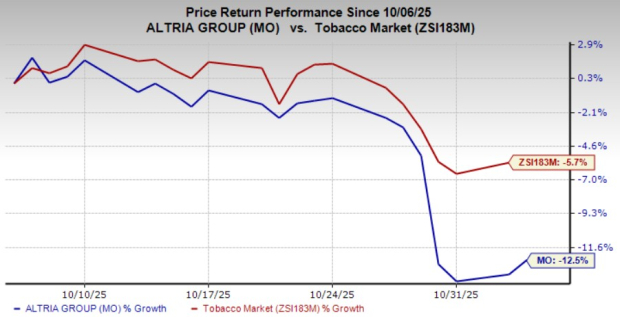
Image Source: Zacks Investment Research
From a valuation standpoint, MO trades at a forward price-to-earnings ratio of 10.33X, down from the industry’s average of 13.44X.
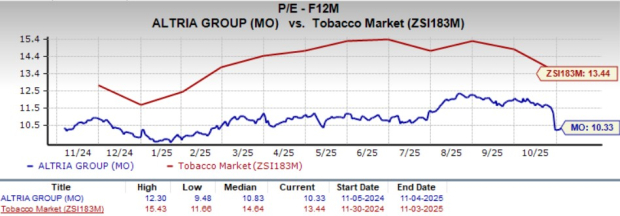
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for MO’s 2025 and 2026 earnings implies year-over-year growth of 6.1% and 2.5%, respectively.
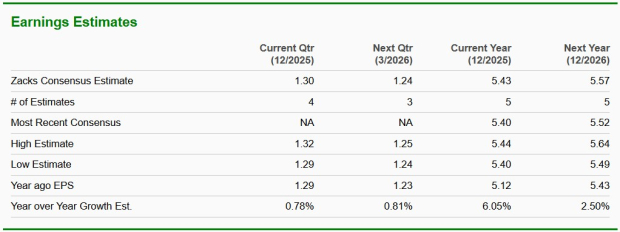
Image Source: Zacks Investment Research
Altria currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Altria Group, Inc. (MO): Free Stock Analysis Report
Philip Morris International Inc. (PM): Free Stock Analysis Report
Turning Point Brands, Inc. (TPB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Sep-09 |
Philip Morris Expands Zyn Nicotine Pouch Lineup, Adds More Pouches Per Can
PM
The Wall Street Journal
|
| Sep-08 | |
| Sep-04 | |
| Sep-04 | |
| Sep-03 | |
| Sep-01 | |
| Aug-31 | |
| Aug-28 | |
| Aug-27 | |
| Aug-26 | |
| Aug-25 | |
| Aug-24 |
