Coursera (COUR): Buy, Sell, or Hold Post Q3 Earnings?
Coursera currently trades at $8.09 per share and has shown little upside over the past six months, posting a small loss of 2.1%. The stock also fell short of the S&P 500’s 14.4% gain during that period.
Is now the time to buy Coursera, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free for active Edge members.
Why Is Coursera Not Exciting?
We don't have much confidence in Coursera. Here are three reasons we avoid COUR and a stock we'd rather own.
1. Customer Spending Decreases, Engagement Falling?
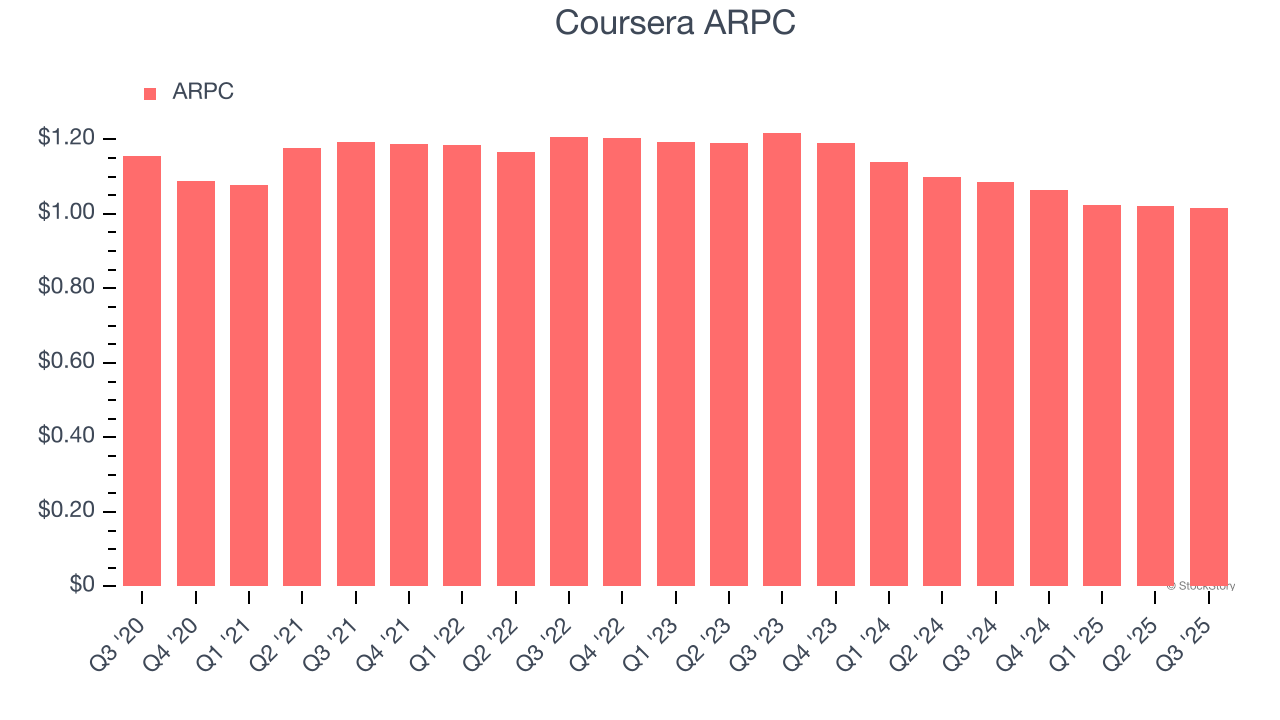
Average revenue per customer (ARPC) is a critical metric to track because it measures how much the average customer spends. ARPC is also a key indicator of how valuable its customers are (and can be over time).
Coursera’s ARPC fell over the last two years, averaging 7.3% annual declines. This isn’t great, but the increase in paying users is more relevant for assessing long-term business potential. We’ll monitor the situation closely; if Coursera tries boosting ARPC by taking a more aggressive approach to monetization, it’s unclear whether customers can continue growing at the current pace.
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Coursera’s revenue to rise by 6%, a deceleration versus This projection doesn't excite us and implies its products and services will see some demand headwinds.
3. Poor Marketing Efficiency Drains Profits
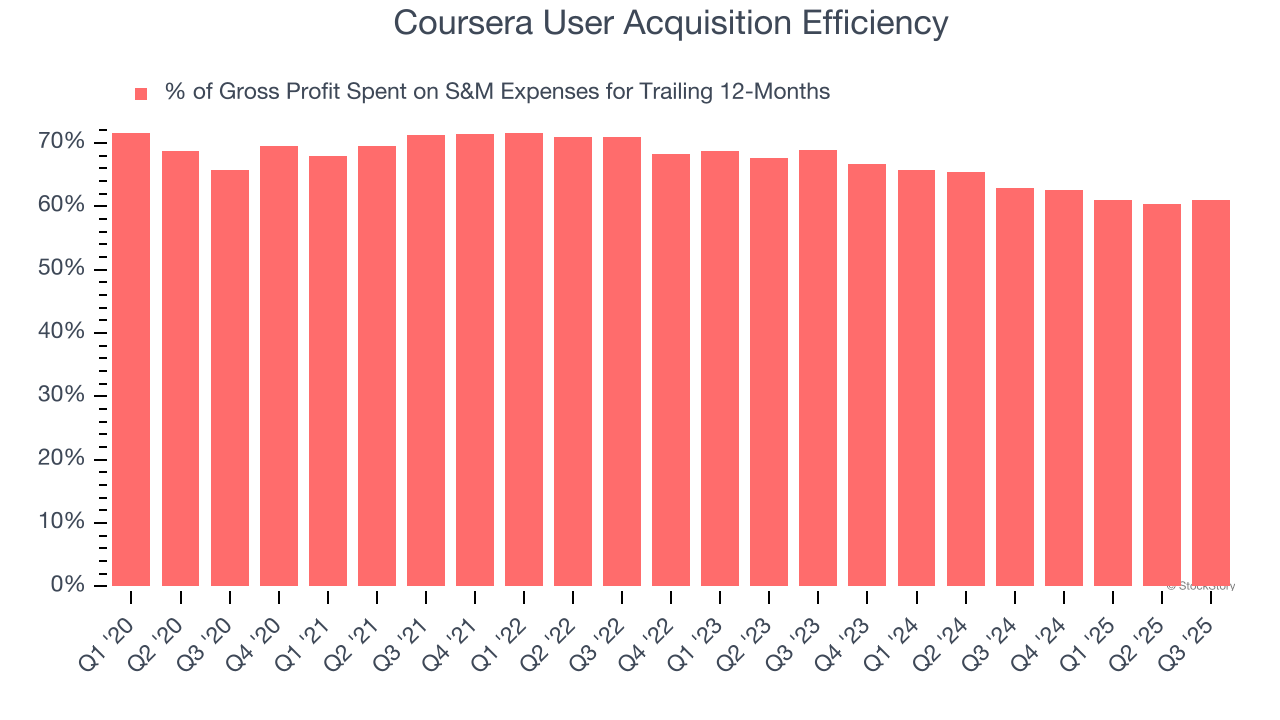
Consumer internet businesses like Coursera grow from a combination of product virality, paid advertisement, and incentives (unlike enterprise software products, which are often sold by dedicated sales teams).
It’s very expensive for Coursera to acquire new users as the company has spent 61% of its gross profit on sales and marketing expenses over the last year. This inefficiency indicates a highly competitive environment with little differentiation between Coursera and its peers.
Final Judgment
Coursera isn’t a terrible business, but it doesn’t pass our bar. With its shares lagging the market recently, the stock trades at 19.9× forward EV/EBITDA (or $8.09 per share). This multiple tells us a lot of good news is priced in - you can find more timely opportunities elsewhere. Let us point you toward one of our top digital advertising picks.
Stocks We Would Buy Instead of Coursera
Your portfolio can’t afford to be based on yesterday’s story. The risk in a handful of heavily crowded stocks is rising daily.
The names generating the next wave of massive growth are right here in our Top 6 Stocks for this week. This is a curated list of our High Quality stocks that have generated a market-beating return of 244% over the last five years (as of June 30, 2025).
Stocks that have made our list include now familiar names such as Nvidia (+1,326% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+354% five-year return). Find your next big winner with StockStory today.
StockStory is growing and hiring equity analyst and marketing roles. Are you a 0 to 1 builder passionate about the markets and AI? See the open roles here.
Mentioned In This Article
Latest News
| Sep-18 | |
| Sep-09 | |
| Sep-06 | |
| Aug-06 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-15 | |
| Jul-14 | |
| Jun-23 | |
| Jun-11 |
