Coursera's First Full Udemy Quarter Puts Synergies Against Stalled Organic Growth
Coursera's third-quarter report will be the first to include a full three months of Udemy, and that matters for more than accounting reasons. The headline numbers will look spectacular, with revenue roughly doubling from a year ago. The real question is whether the combined company is anything more than a cost-cutting exercise bolted onto two learning platforms whose underlying demand has gone flat.
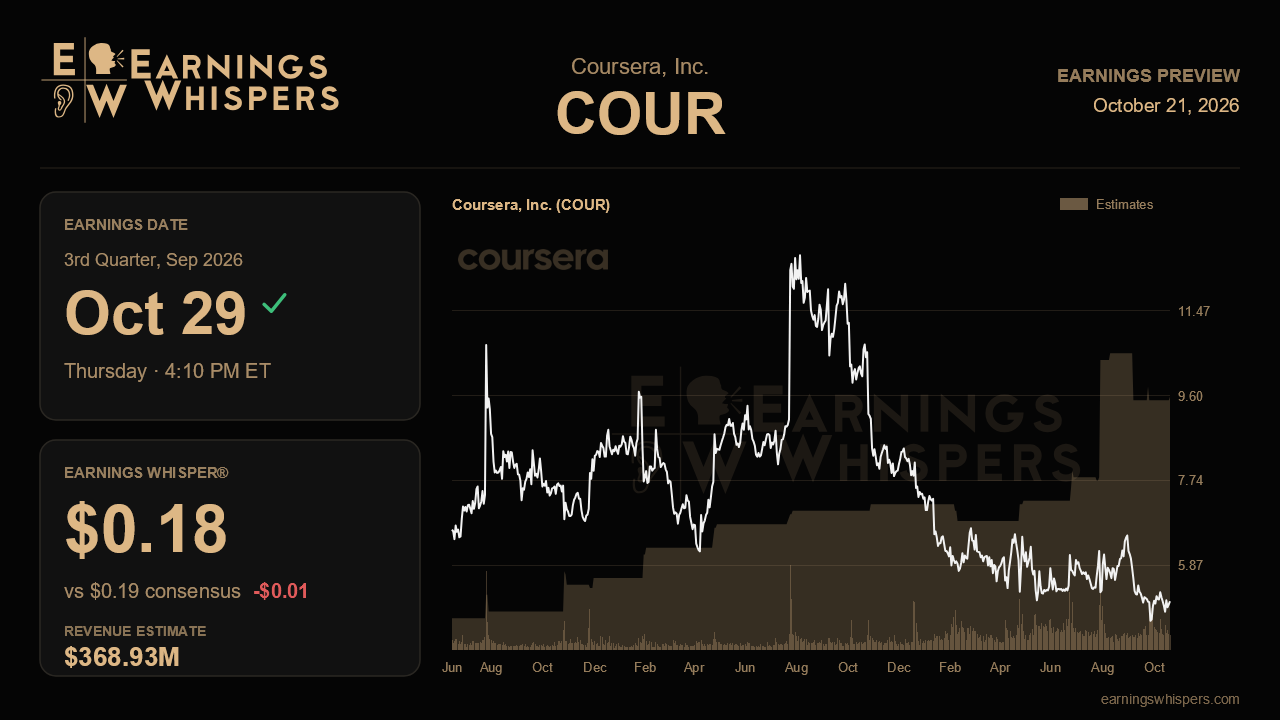
Wall Street expects non-GAAP earnings of $0.19 a share on revenue of about $368.9 million, up roughly 90% from the $194.2 million Coursera posted a year earlier. That compares with a loss of four cents in the year-ago quarter and a three-cent profit last quarter. Management guided to revenue of $364 million to $372 million, so the consensus sits comfortably in the middle of the range rather than reaching for the top. The Earnings Whisper of $0.18 is a penny below consensus, a small gap but a sign that the more skeptical crowd is not counting on upside. Taken together, the bar looks reasonable rather than heroic.
The prior call was a tale of two scorecards. On profitability, management kept raising targets. The full-year adjusted EBITDA margin goal moved up to roughly 14% from 13% set in June, the fourth-quarter exit margin is expected above 16%, and run-rate net synergies by year-end were lifted to at least $85 million on the way to $150 million. Paid subscribers grew 44% to more than 1.65 million, and over 85% of revenue is now recurring. Yet on a normalized basis, which treats the two companies as if they had always been combined, revenue fell 1%, with consumer down 5% and enterprise up just 3%. Enterprise net revenue retention came in at 91%, well short of the above-100% level management wants. This quarter needs to show that the margin story is holding while the organic picture at least stops deteriorating.
A validating report would deliver EBITDA margins tracking toward that 14% annual pace, synergy progress at or ahead of plan, and normalized growth that inches back toward positive territory. Enterprise retention is the metric to scrutinize. The sales teams were combined only about three weeks before the last call, and roughly a fifth of combined enterprise annual recurring revenue overlaps, which creates real risk that customers consolidate contracts and shrink spend. If retention slips back toward 89% or 90%, the synergy gains start to look like they are partly offset by revenue leakage. Consumer trends also bear watching, since management is deliberately restraining paid marketing while transactional and individual program sales stay weak. Free cash flow is another test after a $33 million outflow in the second quarter driven by roughly $57 million of acquisition and integration costs.
The market has not been generous. Shares have slipped 4.5% since the last report while the S&P 500 gained 4.5%, a nine-point gap. At $5.07, the stock trades below its 200-day moving average of $5.79 and sits much closer to the post-earnings low of $4.53 than the $6.64 high. Sentiment remains bearish but has improved from the prior quarter, suggesting fatigue more than fresh alarm. The roughly $140 million already spent on buybacks shows management sees value at these levels.
The longer-term catalysts, including the AI-native unified platform targeted for early 2027 and the $100 million LearnVector stake alongside Andrew Ng, will not show up in this quarter's numbers, and the related-party nature of LearnVector may draw questions. What will decide the reaction is whether Coursera can pair another clean execution on margins and synergies with credible evidence that combined demand, especially enterprise retention, has found a floor. Without that, investors are likely to keep valuing the deal as a cost story rather than a growth one.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-15 | |
| Sep-29 | |
| Sep-23 | |
| Sep-21 | |
| Sep-18 | |
| Sep-09 | |
| Sep-06 | |
| Aug-06 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 |
