Dow, Nasdaq Futures Plummet as AI Spending Weighs
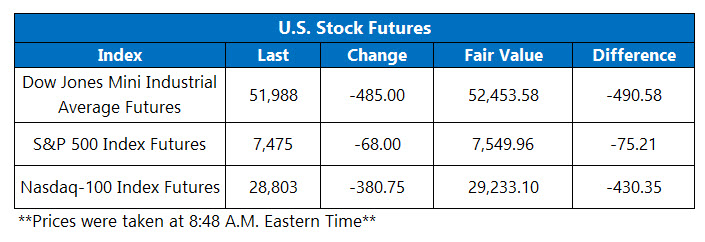
Futures on both the Dow Jones Industrial Average (DJI) and Nasdaq-100 Index (NDX) are down triple digits, as investors weigh lackluster corporate reports from Alphabet (GOOGL) and Tesla (TSLA). Capex spending plagued both reports, with AI demand driving the former. Crude prices are extending yesterdays surge, with front-month crude up 4.9% and near $90/barrel. And if that's not enough, Middle East tensions are boiling over, after Tehran's Houthi group said the U.S. attacked two Saudi Arabian tankers.
The 10-year Treasury yield is rising in response, eclipsing 4.7% and tapping its highest level since January 2025. Meanwhile, weekly jobless claims came in at 187,000, falling from last week by 22,000 and missing expectations of 210,000.
Continue reading for more on today's market, including:
- These psychologically significant levels are not green lights.
- Signal says buy the dip in Applied Materials stock.
- Plus, three tech leaders suffering a post-earnings slump.
5 Things You Need to Know Today
- The Cboe Option Exchange saw roughly 2 million call contracts and 1.3 million put contracts traded on Wednesday. The single-session equity put/call ratio rose to 0.67, while the 21-day moving average remained at 0.58.
- Alphabet Inc (NASDAQ:GOOGL) stock is sinking 4.8% in electronic trading, after the tech behemoth increased its capital expenditures outlook to boost AI backing. The news is overshadowing a Q2 earnings and revenue beat and is set to send the shares to their fifth loss in six sessions.
- Shares of IBM (NYSE:IBM) are 2% lower before the bell, extending their pullback on the charts after posting a second-quarter earnings and revenue miss. Mere days off last week's worst daily drop ever, IBM sports a 2026 deficit of 30%.
- Chipmaker Texas Instruments Inc (NASDAQ:TXN) is 3.9% lower ahead of the open, brushing off a second-quarter earnings and revenue beat. Should these losses hold, TXN will be once again testing support at $280.
- Everything slated to close out this week.

Asian Markets Stay Strong as Europe Unpacks ECB Decision
Asian markets finished higher as traders digested an interest rate hike decision from the Bank of Japan (BoJ). The Nikkei index gained 0.5%, while the Hang Seng added 1.3%, and China’s Shanghai climbed 0.3%. Elsewhere, the South Korean Kospi led regional gains and jumped 4.4% after its second-quarter GDP expanded 0.6%.
European bourses are lower as traders shrug off energy sector gains and brace for the European Central Bank’s (ECB) policy decision. Meanwhile, higher oil prices are driving weakness in precious metal miners. At last glance, London’s FTSE is off 0.1%, while Germany’s DAX is down 0.6%, and France’s CAC is 1.1% lower.
Mentioned In This Article
Latest News
| 59 min | |
| 2 hours | |
| 2 hours | |
| Sep-18 | |
| Sep-18 | |
| Sep-18 | |
| Sep-18 | |
| Sep-18 | |
| Sep-18 | |
| Sep-18 | |
| Sep-18 | |
| Sep-18 | |
| Sep-18 | |
| Sep-18 | |
| Sep-18 |
