Stock Futures Mixed as Crude Continues Lower
Stock futures are mixed this morning following yesterday's market rally, with futures on the Dow Jones Industrial Average (DJI) up 211 points. The S&P 500 Index (SPX) modestly higher before the open, while the Nasdaq-100 Index (NDX) hovers just below breakeven. The 10-year Treasury yield is holding below 5% at 4.951%, while oil prices continue to retreat following reports that Iran offered to reopen the Strait of Hormuz within seven days.
Investors are also looking ahead to this week's meeting between U.S. President Donald Trump and Chinese President Xi Jinping, with AI, tariffs, the Iran war, and rare earth metals expected to be among the topics discussed.
Continue reading for more on today's market, including:
- The S&P 500 is holding above a key support level, per Schaeffer's Senior V.P. of Research Todd Salamone.
- Options favorite Micron stock is staging a bounce.
- Plus, BABA unveils latest AI growth plans; ONON surges after Investor Day; and VKTX is becoming a serious weight-loss drug contender.
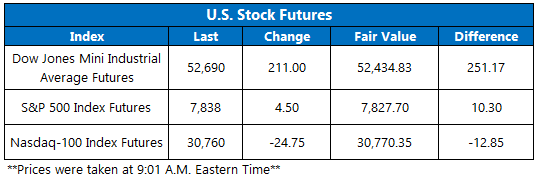
5 Things You Need to Know Today
- The Cboe Option Exchange saw roughly 3.1 million call contracts and 1.6 million put contracts traded on Monday. The single-session equity put/call ratio fell to 0.53, while the 21-day moving average remained at 0.59.
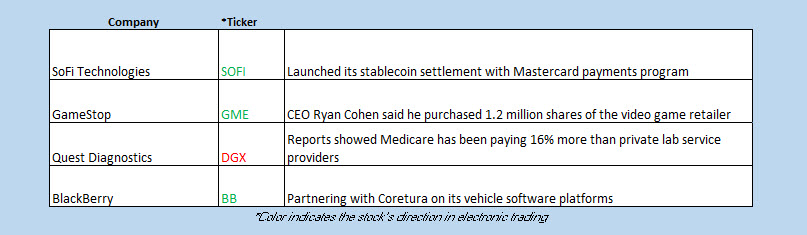
- Alibaba Group Holding Ltd (NYSE:BABA) is up 3.1% premarket, after the tech giant launched the new Zhenwu V900 chip, which offers three times the performance of its predecessor. He also laid out plans to operate more than 20 gigawatts of global data center capacity by 2032. Should these gains hold, BABA will notch its fourth-straight gain. The shares are coming into today with a 21% year-to-date deficit.
- ON Holding AG (NYSE:ONON) is up 7.9% before the bell, after the company set new midterm financial targets at its Investor Day, including gross profit margin of 65% by 2029, and reiterated its full-year guidance. ONON is looking to move away from this month's two-year lows, now down 41.2% in 2026.
- Viking Therapeutics Inc (NASDAQ:VKTX) is up 29.6% in electronic trading, after the biotech company posted strong data for its weight-loss drug, VK2735. Should this price action hold, the stock will erase its 14.4% year-to-date deficit.
- A handful of economic data is due out this week, including PMI readings.
Markets Broadly Higher Overseas
Markets across Asia moved modestly higher today, as investors awaited this week’s meeting between President Trump and President Xi. Alibaba (BABA) is in focus, after the China-based tech conglomerate revealed new plans for AI expansion, as mentioned above. Hong Kong’s Hang Seng and South Korea’s Kospi both tacked on 0.2%, while China’s Shanghai Composite inched 0.06% higher. Japanese stocks remained closed for holiday.
European stocks sport comfortable gains as investors monitor fresh economic data. In the U.K., the Office for National Statistics said net borrowing saw a reading of £18.3 billion, significantly higher than the estimated £15.5 billion deficit. Bond yields are back on the move following Monday’s brief pullback. At last glance, London’s FTSE 100 is up 0.07%, France’s CAC 40 is 0.4% higher, and Germany’s DAX has added 0.5%.
Mentioned In This Article
Latest News
| 8 hours | |
| Sep-21 | |
| Sep-18 | |
| Sep-17 | |
| Sep-16 | |
| Sep-15 | |
| Sep-14 | |
| Sep-11 | |
| Sep-10 | |
| Sep-10 | |
| Sep-09 | |
| Sep-08 | |
| Sep-04 | |
| Sep-03 | |
| Sep-02 |
