Bear of the Day: MasterCraft Boat (MCFT)
MasterCraft Boat Holdings, Inc. MCFT is trying to come back from several years of declining earnings. This Zacks Rank #5 (Strong Sell) is expected to see earnings grow 5.7% this fiscal year.
MasterCraft Boat is a designer, manufacturer, and marketer of recreational powerboats. It has five brands including MasterCraft, Crest, Balise, Chaparral, and Robalo.
It has over 500 global dealer locations.
MasterCraft Has Beat on Earnings Every Quarter for 5 Years
MasterCraft is an earnings all-star. It hasn’t missed on earnings for the last 5 years. That’s impressive for any company.
On Sep 10, 2026, MasterCraft reported its fourth quarter 2026 and full year 2026 results and beat again.
It reported $0.67 versus the Zacks Consensus of $0.61.
In the quarter the company closed on the Marine Products Transaction. But excluding that contribution, net sales in the fourth quarter still rose 21.5%, or $17.1 million, year-over-year.
For the full year, net sales rose 11%, excluding the Marine Products Transaction, to $348.9 million.
“Fiscal 2026 was a defining year for MasterCraft Boat Holdings. Strong execution across our legacy business drove results to significantly outperform expectations despite a challenging retail environment,” said Brad Nelson, Chief Executive Officer.
Analysts Cut Full Year Fiscal 2027 Earnings Estimates
Two estimates were cut in the last 30 days for fiscal 2027. The F2027 Zacks Consensus has fallen to $1.86 from $2.02.
That would normally be the reason as to why MasterCraft Boat is a Zacks Strong Sell. The two analysts are in agreement and cutting earnings estimates.
But MasterCraft is switching from the fiscal year to the calendar year. That means there will be two quarters of this transitional period.
Analysts Bearish on Q1 of the Transition Period
MasterCraft gave an outlook for the transition period including the first quarter, which we’re in right now.
It gave a forecast of adjusted earnings of $0.40. This is now under the Zacks Consensus Estimate, which is at $0.44 with three estimates being revised higher in the last 30 days.
The company also gave a two-quarter transition period guidance of $0.66 to $0.76. But if you add up the current two quarter Zacks Consensus Estimates you get $0.85.
That’s way beyond the company’s guidance range.
Here’s the 5-year price and consensus chart.
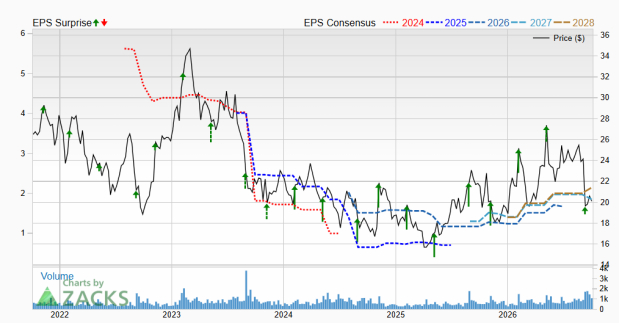
Image Source: Zacks Investment Research
MasterCraft Shares Sold Off Again
MasterCraft is a small cap company with a market cap of just $489 million. That means it’s likely more volatile and we can see that over the last few years.
Shares are down again in the last 3 months, falling 17.4%.
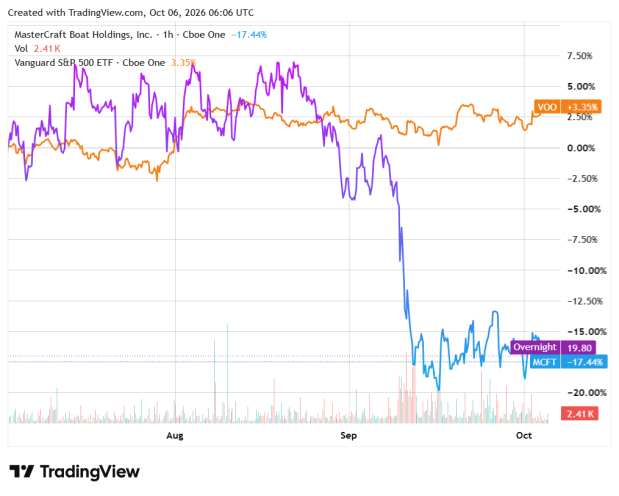
Image Source: Zacks Investment Research
Is MasterCraft cheap?
It trades with a forward price-to-earnings (P/E) of 10.8. A P/E of 10 and under is usually considered dirt cheap and it’s hanging out right near the 10 level.
Like many small cap companies, MasterCraft does not pay dividends.
The earnings estimates are a bit confusing right now as it transitions to a calendar year.
But we do know that earnings were in the red in fiscal 2024 and 2025 before turning around in a big way in fiscal 2026 when they finally popped 91.3%.
Is the worst over?
If I were an investor interested in MasterCraft and its other brands, I would wait on the sidelines for further confirmation about the company’s mergers and acquisitions and the direction of earnings.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
MASTERCRAFT BOAT HOLDINGS, INC. (MCFT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| Oct-06 | |
| Sep-30 | |
| Sep-12 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Aug-24 | |
| Aug-04 | |
| Jun-29 | |
| May-15 | |
| May-07 | |
| May-07 | |
| May-07 | |
| May-06 |
