Stride Beats On Revenue, Misses The Whisper As Enrollment Declines And A New CEO Starts A Reset
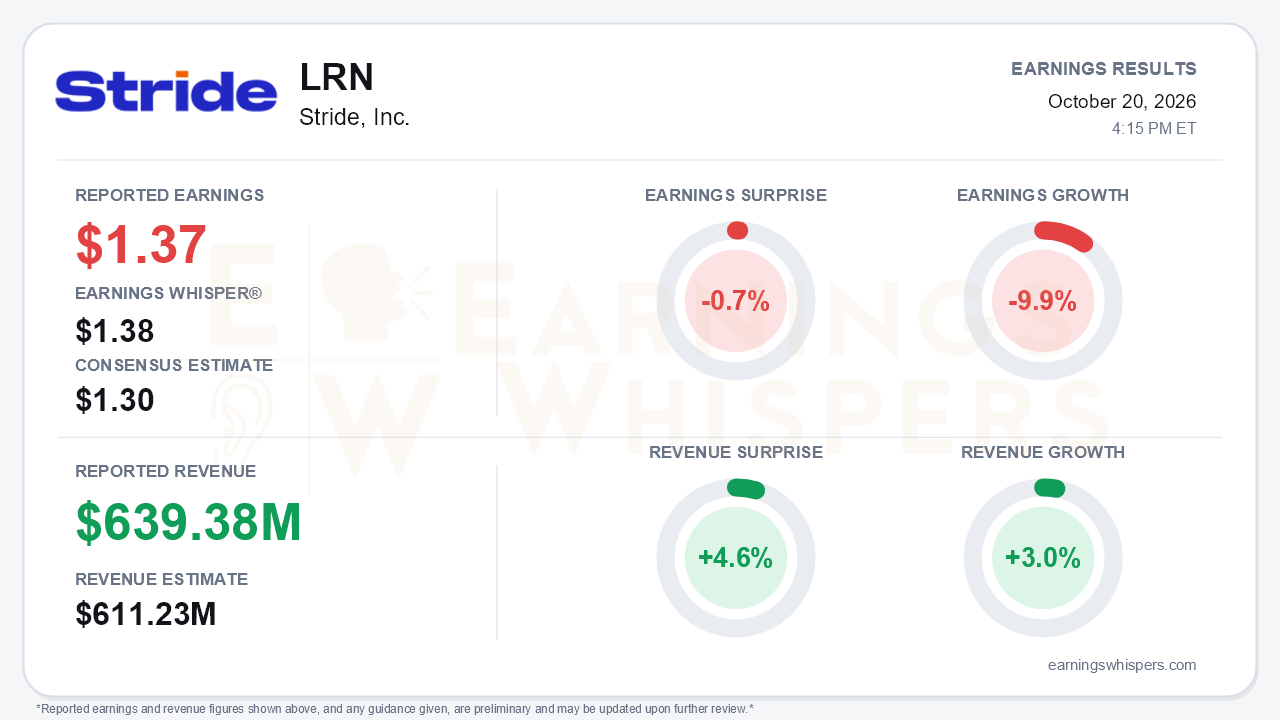
Stride's fiscal first-quarter headline looks better than the business beneath it. The company reported adjusted earnings of $1.37 per share, above the $1.30 consensus but a penny short of the $1.38 Earnings Whisper number, a 0.7% miss against the expectation that mattered most. Revenue of $639.38 million beat consensus by 4.6% and grew 3.0% year over year. Adjusted earnings fell 9.9%, however. The central tension is that pricing and mix carried the top line while the core volume engine, enrollment, went backward for the first time in this recent stretch.
The quality of the quarter deserves scrutiny. GAAP income from operations jumped 22.2% to $84.3 million, and diluted GAAP EPS rose to $1.45 from $1.40. Much of that came from accounting and share-count effects rather than operating strength. Stock-based compensation was a $7.4 million credit, compared with a $10.2 million expense a year earlier, because leadership turnover triggered award forfeitures. That swing explains most of the decline in reported SG&A. Diluted shares also fell to 44.8 million from 49.2 million. Strip out the forfeiture benefit, as Stride's own non-GAAP measures do, and adjusted operating income slipped to $78.6 million from $81.1 million. Gross margin compressed to 37.7% from 39.0%, as instructional costs grew faster than revenue.
The revenue mix tells the same story. Average enrollments fell 2.5% to 241.4K, a sharp reversal from 7.8% growth two quarters earlier and 1.8% growth last quarter. General Education revenue declined 1.8%. Career Learning enrollments rose only 2.0%, a dramatic slowdown from the double-digit pace management had touted. Middle-high school career revenue still rose 12.7%, while Adult revenue dropped 34.4%. Revenue per enrollment climbed 7.0% to $2,556, and that is what produced the revenue beat. However, management guided full-year revenue per enrollment growth to just 1.5% to 2.5%, so this lever cannot keep offsetting volume losses at the same rate.
The call marked a clear change in tone. New CEO Bob Knowling, in the role since late July, called the results disappointing. He launched a strategic reassessment and said the company is halting initiatives without a clear path to value. Management identified several causes of the weak fall season:
- Applications declined.
- Launchpad platform enhancements created friction at school launch, hurting both applications and new-student retention. This was the second consecutive fall with technology problems, after management had expressed confidence earlier in the year that it would not recur.
- The loss of the Lone Star program cost a net of roughly 3,000 students, and Texas capacity remains constrained.
- Changes to Google search and AI tools are reducing the effectiveness of the marketing funnel.
This is a long way from the "strongest pipeline in five years" language of the spring. Bears have legitimate ammunition here.
The forward picture is not broken. Fiscal 2027 guidance calls for revenue of $2.53 billion to $2.61 billion and adjusted operating income of $500 million to $530 million, both above the fiscal 2026 framework, and management reaffirmed its fiscal 2028 targets. SG&A is now expected to fall 10% to 15%, though gross margin is guided down 100 to 200 basis points. Management also cited positive in-year enrollment activity since the September count date, something that did not happen last year. The guidance midpoint assumes that gain holds through year-end. Other supports include:
- a net gain of five school programs;
- restored marketing spend;
- a new CIO consolidating all IT development and operations;
- a new Capital Allocation Committee;
- a buyback authorization extended through October 2027 with $311 million remaining.
The balance sheet adds a wrinkle: the $420 million convertible note maturing in September 2027 is now a current liability and must be settled in cash. That obligation sits against $884.2 million in cash and securities, and the seasonal free cash flow burn improved to -$149.3 million from -$217.5 million.
Investors were not expecting much going in. Earnings Whispers sentiment remained firmly negative but improved modestly, to -0.52 from -0.56. Shares stood at $78.95 at the report, down 9.7% since the open after the August release and 7.6% below the 200-day moving average of $85.45. Price and AVWAP trend readings remain negative, consistent with a stock the market has been steadily marking down.
The bottom line is that Stride delivered a revenue beat built on pricing and mix, not demand. Shrinking enrollment, weaker margins and a whisper miss make the quarter weaker than the consensus comparison suggests. Guidance and the new leadership's reset keep a credible recovery story alive. The burden of proof now rests on whether in-year enrollment gains persist and whether the platform problems are actually fixed before next fall.
Read our earnings preview for Stride, Inc.: https://www.earningswhispers.com/article/LRN/20406
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-20 | |
| Oct-20 | |
| Oct-09 | |
| Oct-07 | |
| Sep-29 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 | |
| Sep-08 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 |
