Karooooo Matches Consensus But Misses The Whisper As Accelerating Subscription Growth Collides With A Cash Squeeze From Memory-Chip Stockpiling
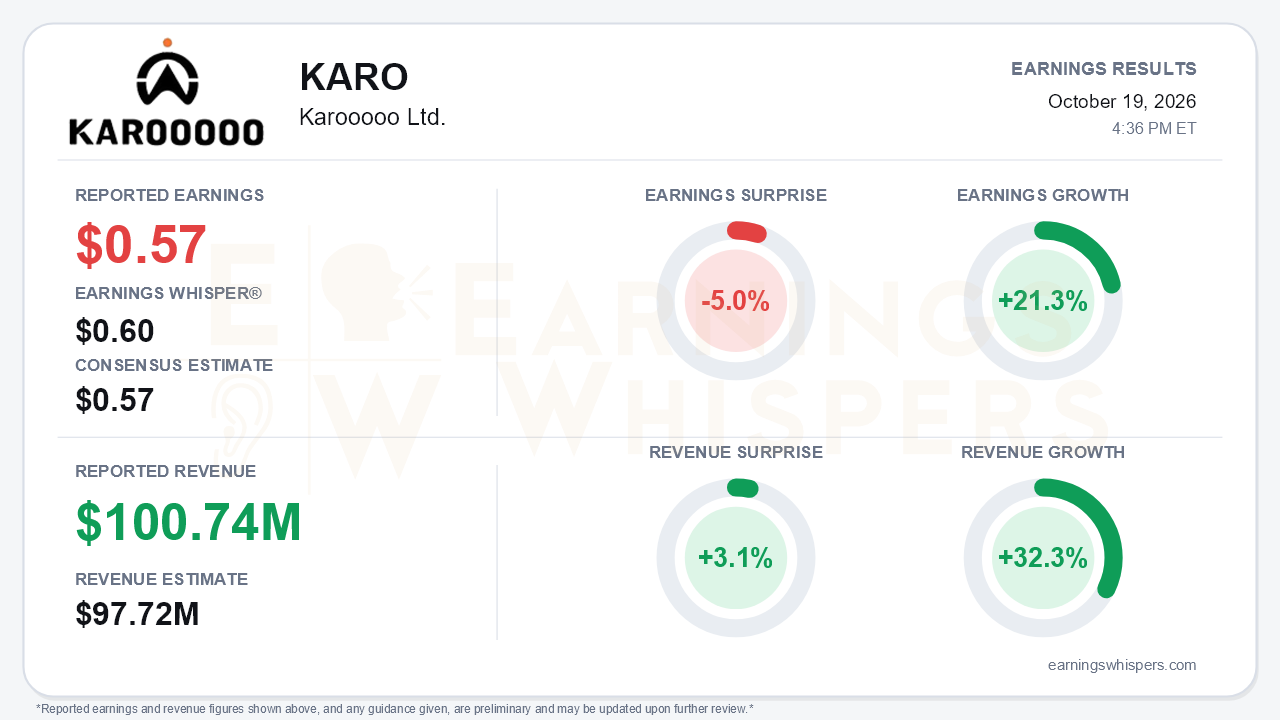
Karooooo (NASDAQ: KARO) delivered another quarter of top-line acceleration in its fiscal second quarter, but the earnings line did not clear the higher bar investors had set. Earnings of $0.57 per share matched the $0.57 consensus estimate and fell 5.0% short of the $0.60 Earnings Whisper number, even as earnings grew 21.3% year over year. Revenue of $100.74 million beat the $97.72 million consensus by 3.1% and grew 32.3% from a year ago. That leaves a split verdict. The growth engine is running faster, but the quarter's profit conversion and especially its cash conversion weakened. That is the central tension.
The quality of the earnings line deserves scrutiny. In rand, the release showed EPS up 18% and Adjusted EPS up only 12%. The release lists both at ZAR9.28, an inconsistency investors may want to reconcile against the full filing. On the call, management attributed the slower adjusted EPS growth to a higher tax rate and higher finance expense, so the pressure came below the operating line. Operating performance itself was solid. Group operating profit reached a record ZAR422 million, up 19% despite a strengthening rand, compared with ZAR410 million in Q1. Cartrack's adjusted EBITDA margin also improved to 46%, from 45% in Q1 and 44% in Q4. Translation helped the dollar figures. Revenue grew 25% in constant currency against 32.3% in USD terms.
The subscription business is where the bull story gained ground. Cartrack subscription revenue rose 20% to ZAR1,415 million, the third straight quarter of improvement after 18% in Q4 and 19% in Q1. Constant-currency growth climbed to 23% from 21%, with acceleration in every region. South Africa improved to 25% growth, and Asia's constant-currency growth jumped to 25% from 17%. Net subscriber additions of 94,516 were a second-quarter record and rose 34%, lifting the base to 2.9 million. USD-equivalent ARR reached $354 million, up from $335 million in Q1. Notably, the acceleration came with less spending. Sales and marketing growth slowed to 16% from 33% in Q1, as the company shifted Cartrack Tag and video from new-customer acquisition toward cross-selling into the installed base. The CEO said Tag is exceeding its FY27 budget. Even so, management reaffirmed rather than raised its FY27 outlook of 18% to 24% constant-currency subscription growth, despite Q2 sitting in the upper end of that range.
The weaker areas are real, and bears have legitimate ammunition:
- **Free cash flow:** It fell to ZAR41 million from ZAR60 million in Q1, a stark contrast with FY26 adjusted free cash flow of ZAR809 million.
- **Inventory build:** First-half investment in IoT devices and memory inventory jumped 86% to ZAR966 million. Management described this as buffering against memory price inflation, with the CEO citing increases of roughly 200% in Q4 FY26.
- **Funding and liquidity:** Short-term bank facilities were expanded, and overdrafts are now classified as financing. Cash fell to ZAR649 million after a ZAR752 million dividend.
- **Margins and credit:** Subscription gross margin slipped to 71% from 73%. Debtor days rose to 33 from 27 at fiscal year-end, and expected credit losses increased.
- **Logistics and Europe:** Logistics revenue growth slowed to 36% from 46%, and its margin narrowed to 6% from 8%. Europe's reported subscription growth slipped to 4%.
- **Macro and opex:** Management acknowledged macro stress in South Africa and fuel-price uncertainty, and declined to commit to further operating leverage. It did guide to stronger second-half free cash flow and a moderately lower tax rate.
Investor sentiment shifted meaningfully. The Earnings Whispers sentiment reading fell from a roughly neutral 0.05 before the prior report to -0.41, a decisive move into negative territory. The stock has nonetheless held up. Shares at $62.10 are 6.0% above the $58.58 opening price after the July report and sit 15.8% above the 200-day moving average of $53.62. The market had been rewarding the growth narrative coming into the quarter, which helps explain why a matched consensus and a missed whisper landed poorly with investors. The Earnings Whispers trend readings lean modestly negative, with price trend neutral and AVWAP negative.
The bottom line is that Karooooo's operating story improved while its financial profile became more strained. Accelerating constant-currency subscription growth, record net adds, rising EBITDA margins and leaner sales spending argue that the cross-sell strategy is working. The fade in free cash flow, the inventory-driven working-capital build and the slip in gross margin explain why the beat-the-whisper crowd was disappointed. With guidance only reaffirmed and shares still well above their 200-day average, the second half now hinges on whether management delivers the stronger cash flow it promised.
Read our earnings preview for Karooooo Ltd.: https://www.earningswhispers.com/article/KARO/20367
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-05 | |
| Jul-16 | |
| Jul-15 | |
| Jul-15 | |
| Jul-14 | |
| Jul-08 | |
| Jun-01 | |
| May-21 | |
| May-14 | |
| May-13 | |
| May-13 |
