John Marshall Bancorp Faces A Sustainability Test As EPS Holds Near $0.50
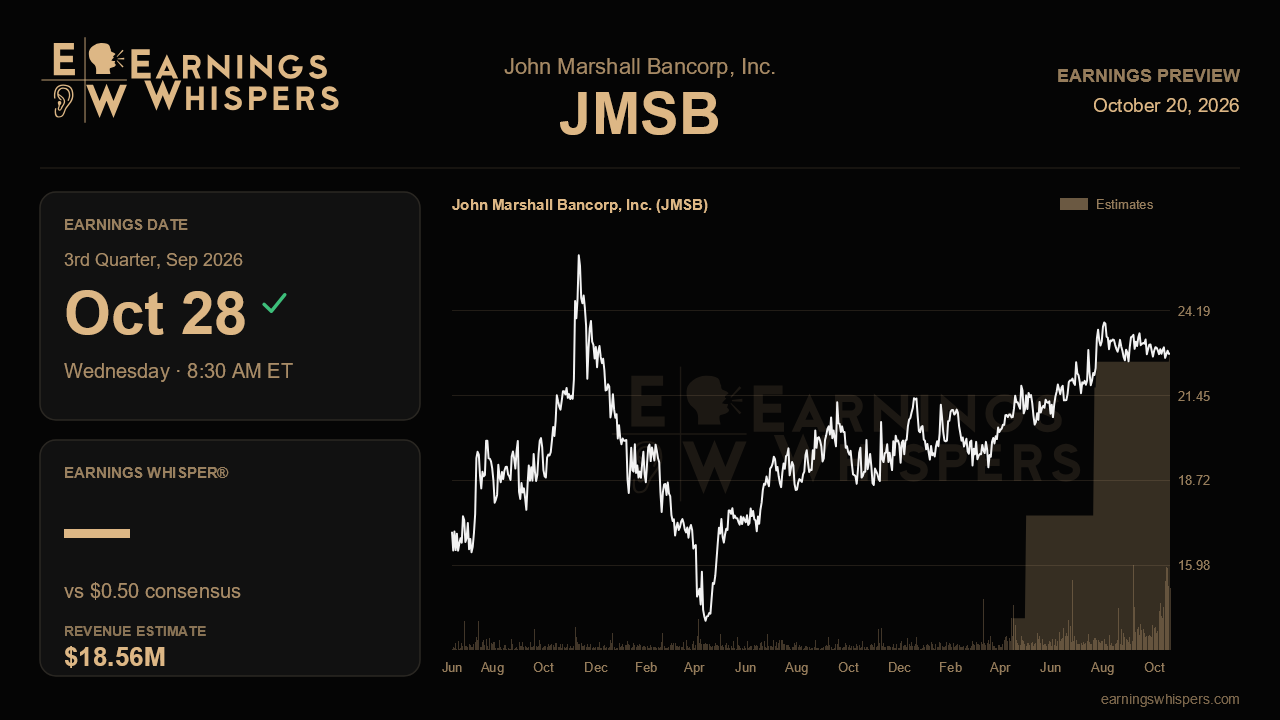
John Marshall Bancorp heads into its third-quarter report with a straightforward question hanging over it: was last quarter's 50-cent profit a new baseline or a high-water mark? Analysts are betting on the former. Consensus calls for earnings of $0.49 per share when the Reston, Virginia lender reports before the open on October 28, essentially flat with the prior quarter but roughly 29% above the $0.38 it earned a year ago. For a community bank, that kind of year-over-year step-up is substantial, and it means the Street is no longer grading the company on improvement alone. It is grading it on durability.
The revenue picture needs a careful reading. Consensus of $18.6 million implies a 37% year-over-year decline and sits well below the $31.2 million reported last quarter. Taken at face value, that would signal a sharp contraction. Yet analysts are projecting EPS growth, not a profit collapse, which suggests the gap more likely reflects differences in how revenue is being measured than a real drop in business. The figure worth focusing on is the bank's core earning power, chiefly net interest income, rather than the headline revenue comparison. A clean match between net revenue and the earnings estimate would reassure investors that the profit forecast rests on solid ground.
With no formal guidance on the table, the report itself has to supply the evidence. For a bank of this size, the 29% earnings gain against a year ago almost certainly depends on how well the spread between loan yields and funding costs has held up. The most useful signals will be whether net interest margin held steady or widened, whether deposit costs kept easing or began creeping back up, and whether loan balances grew without the bank reaching for riskier credits. Holding EPS near $0.50 would validate the view that last year's improvement was structural. A margin that slips or a jump in funding costs would challenge it, even if the headline number lands close to consensus.
Credit and expenses are the other swing factors. A one-penny miss can easily come from a modestly larger loan-loss provision or a bump in operating costs, and for a lender whose earnings have only recently moved into the high-40-cent range, either would invite questions about how much cushion exists. Stable asset quality and disciplined spending would let the margin story carry through to the bottom line.
Sentiment has warmed noticeably. Readings have swung from mildly bearish ahead of the last report to modestly bullish now, a shift that signals growing confidence without tipping into euphoria. The stock has not followed suit. Shares are down 0.4% since the prior report while the S&P 500 gained 2.7%, leaving the stock about three points behind the broader market. At $22.80 it trades comfortably above its 200-day moving average of $21.47 and in the lower half of its post-earnings range of $21.65 to $24.26, roughly 6% below the recent high. That range sits above the prior quarter's band of $20.25 to $23.28, so the longer trend remains constructive even as near-term momentum has stalled.
That combination of improving sentiment and lagging price action sets a reasonable but not trivial bar. The market has not priced in a blowout, yet it does expect the company to show that last quarter's profitability can repeat. The central issue is whether John Marshall can keep its spread income and credit costs steady enough to deliver another quarter near 50 cents. If it does, the case for the higher earnings base strengthens. If margins or provisions slip, the recent gains in profitability may start to look more cyclical than investors had hoped.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-02 | |
| Sep-09 | |
| Sep-09 | |
| Sep-08 | |
| Sep-08 | |
| Aug-19 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-03 | |
| Apr-29 | |
| Apr-29 | |
| Apr-28 | |
| Apr-15 |
