Central Pacific Faces A Loan Growth Reckoning As The Back-Half Promise Comes Due
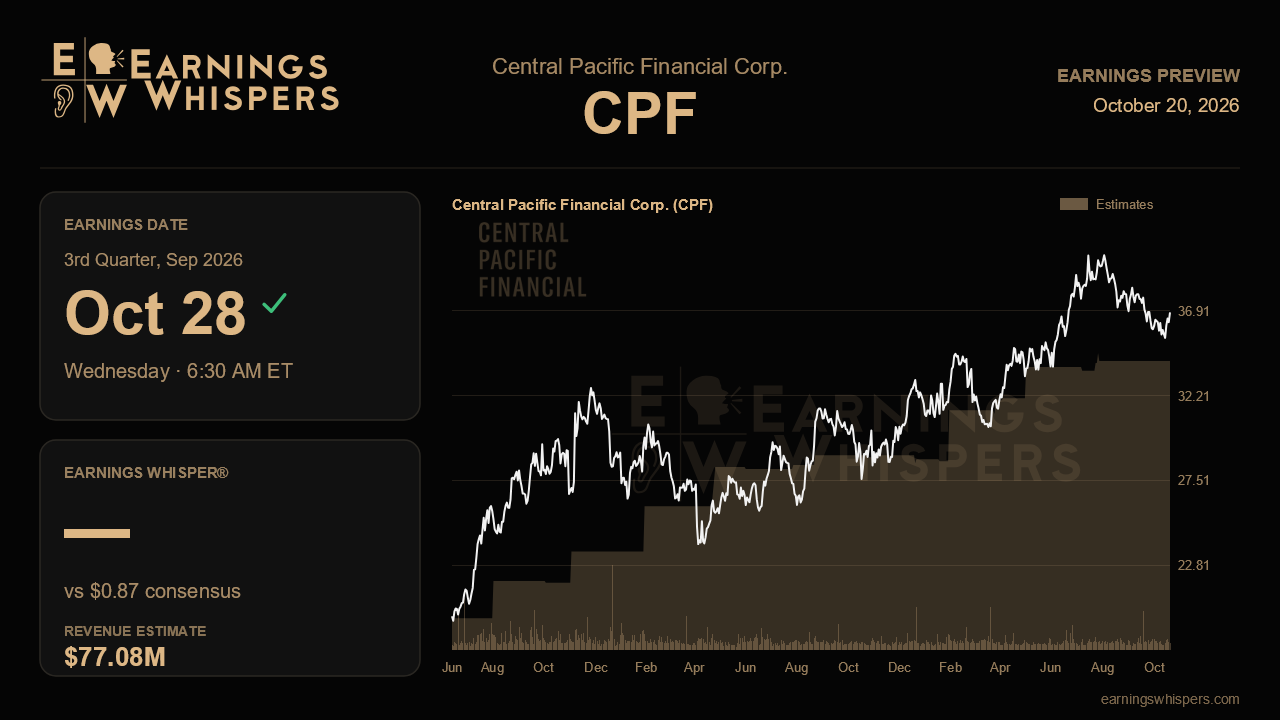
For three straight quarters, Central Pacific Financial has told investors that faster loan growth was coming later in the year. When the Hawaii lender reports third-quarter results before the open on October 28, later will have arrived. That makes this report less about whether the bank can protect its margin, which it has done well, and more about whether the long-promised balance sheet expansion finally shows up while credit stays under control.
The Street is asking for a lot. Consensus calls for earnings of $0.87 a share, up about 19% from $0.73 a year ago and a sizable step up from the $0.80 posted last quarter. Sequential gains of seven cents rarely come from margin alone at a bank this size, so the estimate implicitly assumes some combination of loan growth, a steady or slightly firmer net interest margin, and a lighter provision than the $4.4 million booked in the second quarter. The revenue consensus of $77.1 million implies a 17.5% decline from a year earlier, a figure that sits awkwardly beside quarterly net interest income of $62.8 million and rising margins. That gap more likely reflects differences in how revenue is measured than a shrinking franchise, and it is the earnings line that carries the real test.
Management's full-year framework gives that test some shape. The company reaffirmed rather than raised its outlook for net interest income growth of 4% to 6%, expense growth of 2.5% to 3.5%, and low-single-digit loan and deposit growth. Hitting those targets after loans finished the second quarter flat at $5.3 billion requires real momentum now. The clearest evidence would be funding of roughly $70 million in new mainland multifamily and construction commitments priced in the low 200s over SOFR, along with signs that retail initiatives are slowing runoff in the Hawaii consumer book. If closings slip again and commercial real estate payoffs keep offsetting new business, the lumpy pipeline explanation will start to sound like a structural problem rather than a timing issue.
The margin story has also quietly changed. A year ago the message was outright expansion; last quarter it became relatively steady with a slight upward bias, centered in the high 3.50s, as back-book repricing benefits fade and loan spreads compress. A print around 3.57% to 3.60% would validate that guidance. Anything that dips meaningfully would suggest the repricing tailwind is fading faster than expected, especially with deposit costs already near a low 90 basis points and offering little room to help.
Credit is the swing factor that could overshadow everything else. Criticized loans jumped to 234 basis points of total loans from 135 basis points at the end of last year, driven by a handful of Hawaii credits, including a $20 million real estate loan downgraded over an ownership dispute and guarantor troubles. The allowance was built to 1.4% on more cautious economic assumptions. Stabilization in criticized loans would support the case that this was isolated noise. Further migration, particularly in Hawaii commercial real estate amid a visitor economy described as merely steady, would challenge it.
The market has already leaned skeptical. Shares are down 5.3% since the last report, trailing the S&P 500 by about nine points, and sentiment has swung from essentially neutral to decidedly bearish. At $36.28, the stock sits near the bottom of its post-earnings range of $34.80 to $40.99, though still above its 200-day average of $35.12. A higher dividend and steady buybacks show management's confidence, but the stock needs proof. The central question is simple: does the loan book finally grow without credit slipping further? A yes would make the $0.87 bar look reachable and the recent selloff overdone; another deferral would keep the narrative stuck in waiting mode.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-07 | |
| Jul-24 | |
| Jul-24 | |
| Jul-24 | |
| Jul-24 | |
| Jul-07 | |
| Apr-30 | |
| Apr-30 | |
| Apr-29 | |
| Apr-29 | |
| Apr-08 | |
| Feb-10 | |
| Feb-09 | |
| Jan-29 |
