Cactus Faces A Planned Pressure Control Dip As Spoolable Growth Must Carry The Quarter
Cactus heads into its third-quarter report with an unusual setup: management has already told investors that earnings will come down from last quarter's peak, and the real question is whether the company's fastest-growing business can make that retreat look like a pause rather than a turn. The second quarter was the strongest in the company's recent history, with adjusted EPS of $0.93 and adjusted EBITDA margin expanding to 29.5%. But part of that strength came from Middle East backlog that shipped earlier than planned, and management flagged a payback in the current period.
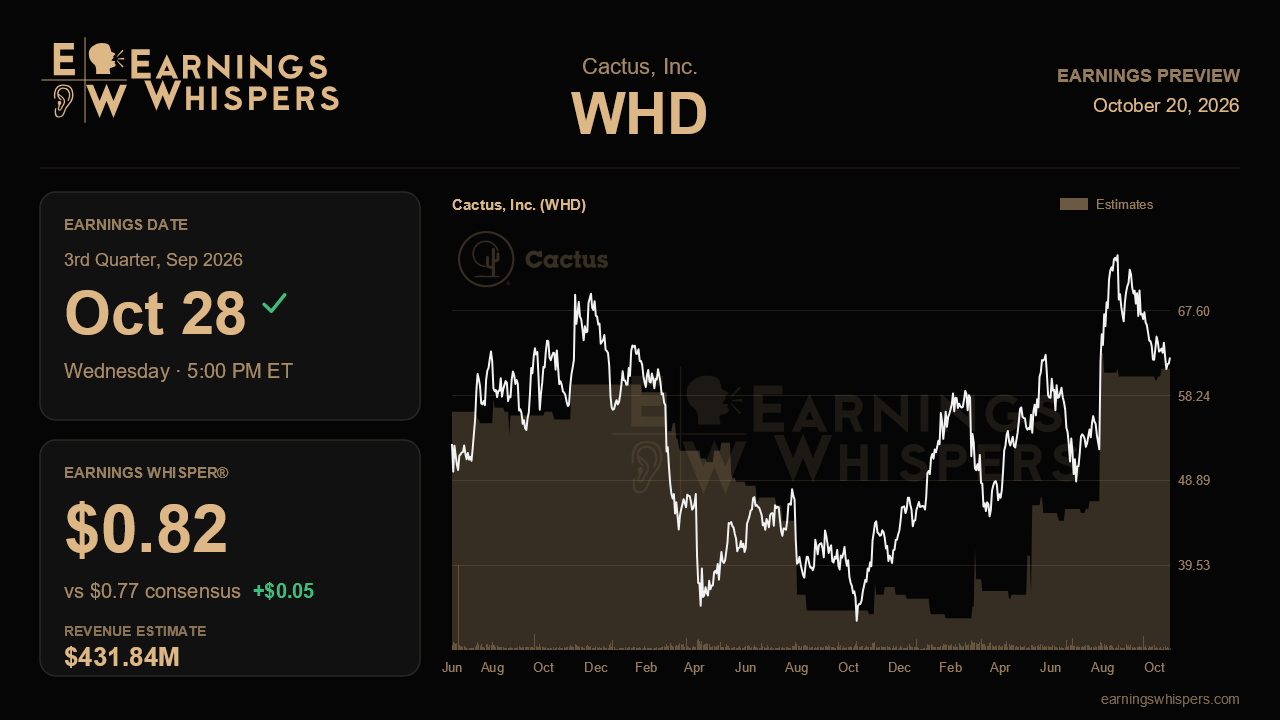
Wall Street has largely taken that message on board. Consensus calls for EPS of $0.77 on revenue of about $431.8 million, a modest sequential decline from $449.5 million but a 63.6% jump from the year-ago quarter, a comparison inflated by the addition of Cactus International. EPS growth of roughly 15% year over year is solid rather than spectacular, a reminder that the acquired business carries thinner margins than the legacy franchise. The Earnings Whisper sits at $0.82, five cents above consensus, suggesting the more engaged crowd expects Cactus to beat the conservative path management laid out, much as it did last quarter.
That path has two moving parts. Pressure control revenue was guided down about 10% sequentially, with segment margin slipping to 22% to 24% from roughly 25.5%, as international aftermarket sales and tariff recovery fade. Spoolable Technologies, meanwhile, was guided up 15% to 20% from $106 million, with margins of 39% to 41%. That margin guide has ratcheted higher on each of the last three calls, from 34% to 36% to the current range, so another quarter inside or above it would confirm that spoolable has become a genuine growth engine rather than a cyclical bright spot. A result at the top of the revenue range would also help justify the decision to lift full-year net capex to $55 million to $65 million to fund a roughly 20% capacity expansion at Baytown and study a possible Eastern Hemisphere plant.
The weak spot remains backlog. It fell to $455.8 million in the second quarter from $537 million a quarter earlier and more than $600 million at the end of 2024, pressured by Middle East logistics disruptions and a contract renegotiation with a large customer. Management has pointed to an order recovery in the second half of 2026 into 2027, so this report is the first real test of that timing. Stabilizing backlog, progress on the customer contract, and evidence that the synergy target, raised twice to $20 million, is flowing into margins would validate the self-help story. Another leg down in backlog would challenge it. Investors should also listen for early commentary on the more than $80 million of international spoolable orders booked in July, which begin shipping in the fourth quarter, along with any further tariff refunds.
Sentiment has cooled noticeably, with the bullish reading falling to 18.7% from 36.3% ahead of last quarter, even though the shares have gained 9.3% since the last report, outpacing the S&P 500 by about 5 percentage points. At $61.77, the stock holds above its 200-day moving average of $57.69 but sits well below its post-earnings high of $74.07, implying it has given back a good portion of its initial enthusiasm.
The central issue is whether the pressure control step-down proves to be the timing reversal management described. If spoolable delivers its guided acceleration and backlog shows signs of bottoming, the dip becomes noise in a strengthening multiyear story. If international order flow keeps slipping, the market may start treating last quarter as the peak rather than the platform.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Aug-20 | |
| Jul-29 | |
| Jul-16 | |
| May-13 | |
| May-12 | |
| May-06 | |
| Apr-15 | |
| Mar-09 | |
| Mar-03 | |
| Mar-01 | |
| Feb-27 | |
| Feb-26 | |
| Feb-26 |
