WEX Needs A Third Straight Guidance Raise As Street Pins Estimates To Top Of Range
WEX heads into its third-quarter report with a problem that most companies would welcome. Management has raised its full-year outlook twice in a row, the balance sheet hit its leverage target early, and buybacks restarted ahead of schedule. The Street has responded by parking its estimates at the very top of the company's own guidance, which means a merely solid quarter may no longer be enough. The real question is whether WEX can keep lifting the bar, and how much of that lift comes from fuel prices rather than operating execution.
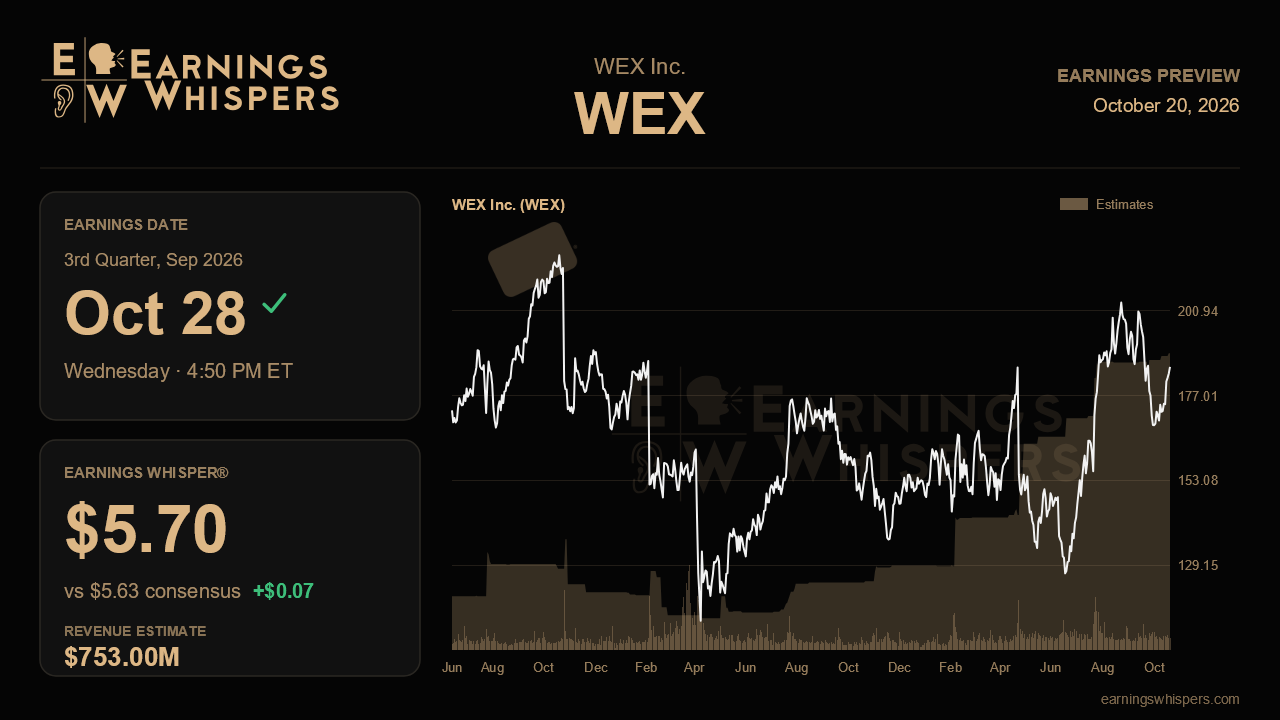
Consensus calls for non-GAAP earnings of $5.63 per share on revenue of $753.0 million when results arrive after the close on October 28. Management guided to $5.45 to $5.65 on revenue of $733 million to $753 million, so analysts sit near the high end on earnings and right at the ceiling on revenue. The whisper number of $5.70 is a little above the top of the guided range, a sign that the informal bar is a clean beat rather than an in-line print. Revenue growth of roughly 9% from $691.8 million a year ago would be healthy, and earnings would be up sharply from $3.77, though the revenue figure would be essentially flat with the second quarter's $753.5 million.
The full-year outlook frames the stakes. Guidance has climbed from $17.25 to $17.85 at the start of the year to $19.68 to $20.08 now. A third raise would confirm that the momentum is durable, while simply holding the range could read as a ceiling. Management promised more than 100 basis points of macro-neutral margin expansion in the back half, and this quarter is the first chance to show that progress in operating margins rather than in fuel-price math. That distinction matters because last quarter's raise leaned partly on higher fuel assumptions, a tailwind that can reverse quickly.
Mobility is the segment most in need of proof. Transactions stabilized in the second quarter, the BP portfolio is now fully migrated, and new pricing actions are expected to contribute about $15 million of revenue in the second half. Evidence that pricing is sticking and that transaction volumes held up would validate the story. Yet trucking demand remains soft, with no recovery in miles driven, and customers paying larger fuel bills earlier have been trimming late-fee income. If that late-fee drag widened, it would challenge the idea that mobility has turned the corner.
In corporate payments, the second quarter's reacceleration in direct accounts payable volume to 20% growth and five basis points of net interchange expansion were bright spots. Sustaining that pace, and seeing purchase volume recover from its timing-driven decline tied to online travel agencies, would strengthen the case. In benefits, SaaS account growth slowed to 2.2%, largely on tough comparisons and prior account closures. Stabilization there would ease concerns about competitive pressure in partner channels, while further slippage would be harder to explain away.
Sentiment has swung from decidedly bearish before the last report to modestly bullish now, and the shares have gained 14.4% since then, beating the S&P 500 by nearly 11 points. The stock trades comfortably above its 200-day moving average near $163, but at $183 it sits about 10% below its post-earnings high of $204, suggesting some enthusiasm has already cooled. That leaves room for a rebound on a strong print, though expectations are clearly richer than they were three months ago.
Ultimately, the narrative holds if WEX delivers at or above the top of its range, raises full-year guidance again, and shows margin expansion and mobility pricing doing the work rather than fuel prices alone. A quarter that meets numbers only because of macro tailwinds would leave the improving story looking more fragile than the rally implies.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-20 | |
| Oct-14 | |
| Sep-30 | |
| Aug-27 | |
| Aug-25 | |
| Aug-13 | |
| Aug-11 | |
| Jul-29 | |
| Jul-29 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-09 |
