VICI Heads Into Q3 With Steady Cash Flow But Tenant Takeover Questions Weighing On Shares
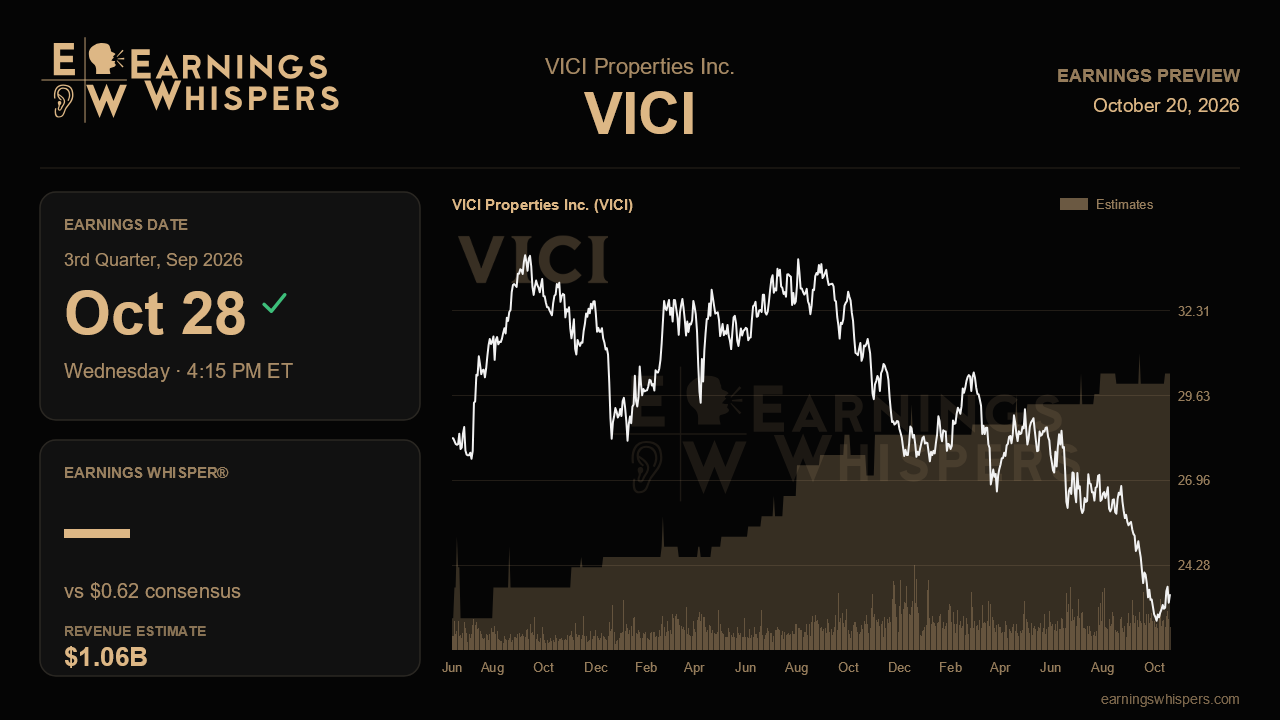
VICI Properties enters its third-quarter report with an unusual disconnect. Its operating business looks about as predictable as a real estate company gets, with management recently tightening its full-year outlook rather than cutting it. Yet the shares have dropped 13% since the last report while the S&P 500 gained about 4%, leaving the stock near $23, close to the bottom of its post-earnings range and well under its 200-day moving average of roughly $27. The quarter itself is unlikely to surprise. The real question is whether management can ease concerns about its two biggest tenants, MGM and Caesars, both of which are now openly in take-private processes.
Wall Street expects per-share earnings of $0.62 on revenue of about $1.06 billion. Both figures match last quarter, and they translate to year-over-year growth of 3.3% on the bottom line and 5.2% on the top. That is modest, steady compounding, not acceleration. It fits a landlord whose leases include built-in escalators and whose growth depends heavily on putting new capital to work. Management's latest guidance calls for 2026 funds from operations of $2.45 to $2.47 per share, an increase at the low end from the earlier $2.44 floor. The consensus of $2.46 sits right at the midpoint. That leaves the Street comfortably inside the range rather than leaning toward another raise. Narrowing the range in October signals confidence, but with only one quarter left, a quarterly result in line with forecasts would mostly confirm what is already priced in.
The more useful information will come from the moving parts management highlighted last time. Deal flow was a clear bright spot. VICI logged back-to-back quarters with more than $1 billion in capital commitments, closed the $1.16 billion Golden Entertainment sale-leaseback, and added Club Med as its 16th tenant. A fresh pipeline update would show that diversification is still moving forward even as the anchor tenants change hands. The same goes for any progress on the possible NBA arena project on the 50 acres VICI owns with Caesars behind the Strip, and on the collegiate sports infrastructure effort, which still seemed early-stage. Management was also upbeat on demand, saying Las Vegas had turned a corner and pointing to strong strip occupancy at MGM. Continued resilience at regional and locals properties would back up that view.
Credit is where the story could weaken. Last quarter brought a $90 million loan modification, roughly 3% of the loan book, with a longer maturity and a lower rate. VICI also increased its CECL reserve after a private tenant issued debt at a weaker implied rating. Neither item was large, but another modification, a non-accrual, or a further reserve increase would suggest a pattern rather than isolated noise. Refinancing is a slower-moving pressure. Roughly $1.75 billion matures in 2026 and about $1.5 billion in early 2027, and new debt in the low-5% range compares with a weighted rate near 4.46%. Commentary on how that cost gap affects 2027 per-share growth may matter more than the third-quarter figure itself.
Sentiment has improved even as the stock has fallen. The reading moved from 28.8% bearish before the last report to 11.3% bearish now. Investors appear less worried about the fundamentals than the share price implies, which points to tenant uncertainty and rate sensitivity rather than earnings as the main source of pressure.
That brings the report back to Caesars and MGM. Management previously described the Caesars regional lease resolution as having no urgency, citing a deal timeline of about a year. If VICI can explain how its master leases, guarantees, and rent escalators hold up under new private ownership, a steady quarter could start to close the gap between the business and the stock. If the commentary stays vague while credit issues accumulate, a solid set of numbers may not be enough.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Sep-30 | |
| Sep-28 | |
| Sep-28 | |
| Sep-22 | |
| Sep-18 | |
| Sep-17 | |
| Sep-10 | |
| Sep-08 | |
| Sep-08 |
