Tenable's AI-Fueled Bookings Story Faces A Revenue Test After A 40% Rally
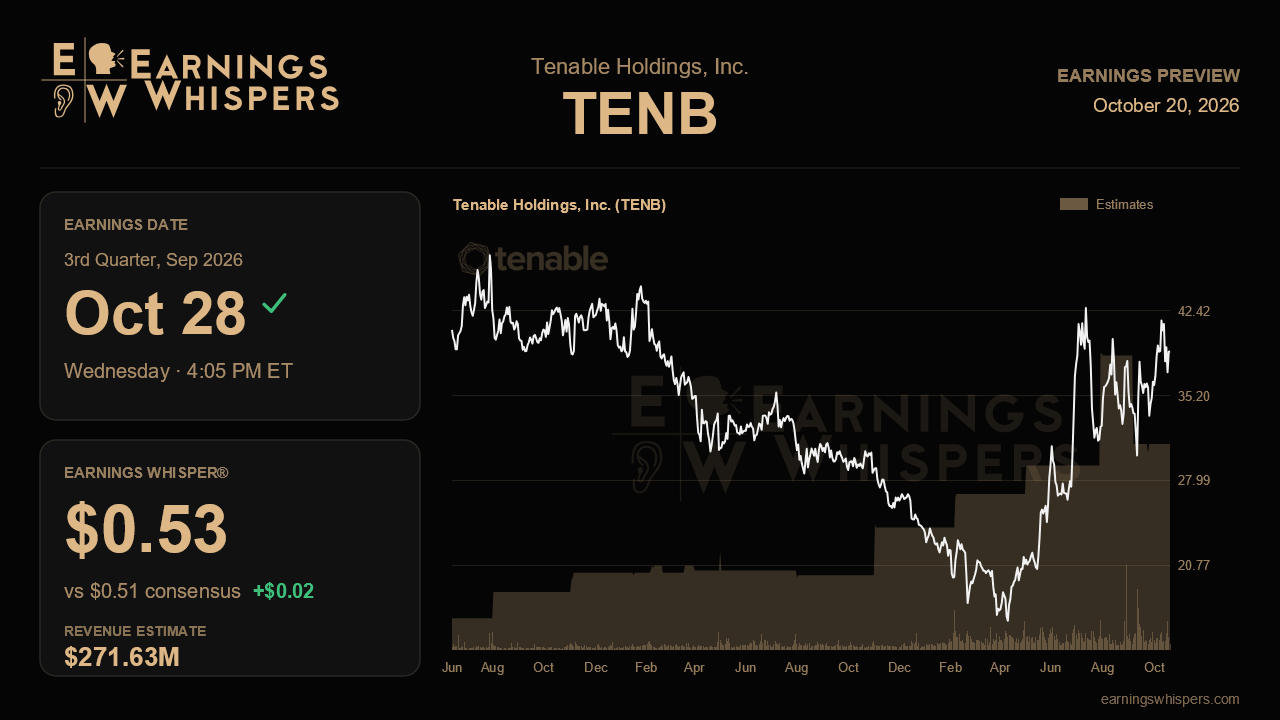
Tenable spent its last earnings call arguing that something fundamental had shifted in its business, and investors bought the argument wholesale. The shares have climbed nearly 40% since that report, while the S&P 500 gained about 4%. The awkward detail is that the revenue line still points the other way. When the cyber exposure specialist reports third-quarter results after the close on October 28, the real question is not whether it clears a modest bar. It is whether the demand management described is finally showing up in numbers that justify the rerating.
The Street expects non-GAAP earnings of $0.51 a share on revenue of $271.6 million. Both sit inside the guidance Tenable issued in July, $0.49 to $0.52 a share on revenue of $270 million to $273 million. Revenue consensus lands almost exactly at the midpoint, while the EPS estimate leans toward the top of the range. The Earnings Whisper of $0.53 sits a penny above both consensus and management's high end. That is not a huge gap, but it signals that a simple in-line print may not be enough. Expected revenue growth of 7.6% would extend a slide that has run from 11.2% a year ago to 8.6% last quarter. Few people will be surprised by that slowdown, and it explains why the debate has moved beyond the headline figures.
Management's case rests on revenue lagging bookings. Last quarter it pointed to several forward indicators. Net dollar expansion rose to 106%, the first sequential improvement since early 2022. Tenable One accounted for a record half of new business, up from about 40% a year earlier. Customers chose the Advanced tier over Foundation by roughly two to one, which lifted deal sizes. Net new seven-figure customers more than doubled. The company also said calculated current billings should come in $8 million to $10 million above its original plan, mostly in the second half. That makes this quarter the first real checkpoint. Billings that track toward that uplift, net dollar expansion holding at 106% or rising, and platform mix staying near 50% would validate the inflection story. A slip in any of those would revive the question one analyst raised last time: why the bullish commentary has not yet moved the revenue line.
The newer catalysts need proof too. HEXA AI went from launch to general availability with hundreds of customers and strong engagement, and Tenable created a token-overage SKU to monetize heavier use. Any early read on that revenue would help. So would progress from FedRAMP High authorization, the deepening work with Anthropic and OpenAI, and the company's plan to add more sales capacity in the second half than in the prior two years combined. That hiring push also makes margins worth watching. Non-GAAP gross margin slipped to 81.4% from 82.7% two quarters earlier, yet full-year operating margin guidance rose to 24.2%. Holding that target while hiring aggressively would show real operating leverage.
Sentiment has warmed, though it remains cautious. The bearish reading has eased to about 27% from 40% before the last report. The stock trades near $39, far above its 200-day average near $28. It also sits roughly 9% below its post-earnings high of $42.69, so it is digesting gains rather than pressing toward a breakout. Competitive risks have not disappeared. Microsoft has a rival vulnerability management program, larger vendors are bundling free tools, and there is a chance the AI-driven surge in remediation spending fades after the first wave.
The verdict likely hinges on the full-year outlook. Revenue guidance of $1.075 billion to $1.081 billion implies fourth-quarter growth below 8%. Another raise, paired with billings that confirm the promised second-half lift, would support the view that growth is near a bottom. A merely reaffirmed outlook, after a 40% run, could leave the market wondering whether the turn was priced in before it arrived.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Sep-14 | |
| Sep-11 | |
| Sep-11 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 |
