Raymond James Must Prove Its Fee Surge Matters As Shares Sink Toward Lows
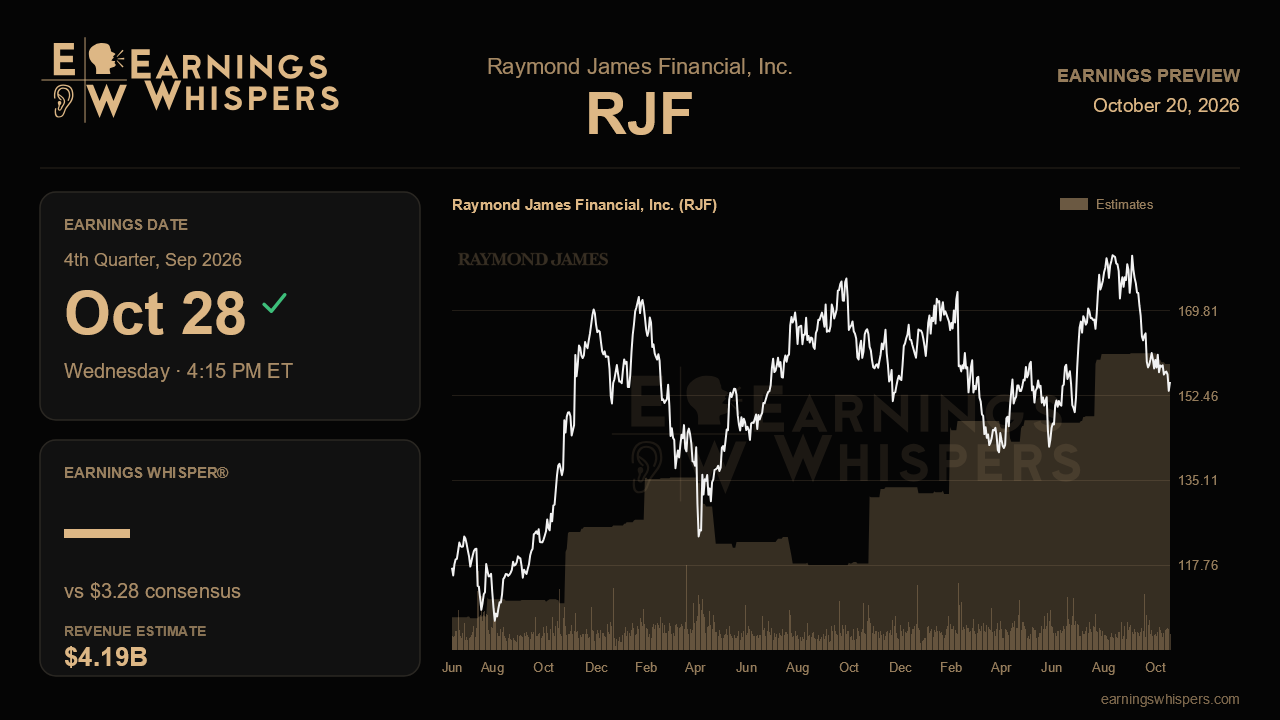
Raymond James heads into its fiscal fourth-quarter report with an odd disconnect. Last quarter brought records almost everywhere, a sharp lift in asset management fee guidance and a noticeably more confident management team. The stock has gone the other way, falling 9.4% since that report while the S&P 500 gained 3.7%. When the company reports after the close on October 28, the question is whether the wealth-management engine can deliver enough visible earnings growth to close that gap.
The Street is looking for earnings of $3.28 a share, up 5.5% from $3.11 a year ago and ahead of last quarter's record $3.14. Revenue is expected at about $4.19 billion, flat with the year-ago period and below the $4.36 billion reported last quarter on the same basis. That revenue bar looks modest given what management signaled. On the prior call, executives guided fourth-quarter asset management fees up roughly 11% sequentially, a dramatic step up from the 1% increases guided in each of the two previous quarters. The reason was mechanical rather than aspirational: fee-based assets in the private client group jumped 11% in the quarter to $1.15 trillion, and those quarter-end balances set the billing base for the period now being reported.
That fee guidance is the cleanest test of the bullish narrative. If asset management fees land near the promised double-digit gain, it confirms that record client assets of $1.86 trillion are translating directly into revenue. It also matters for mix, because fee revenue is recurring and less exposed to market swings than commissions or deal fees. Recruiting is the other pillar. Year-to-date recruited production of $393 million was on pace to top the prior-year record of $407 million, and confirmation of a new high would support the case that the advisor pipeline remains healthy even as the annualized net new asset rate cooled from 8% early in the year to 5.5% last quarter. A further slide in that rate would be the first real crack in the growth story.
The earnings line faces some offsetting pressure. Management guided net interest income plus third-party sweep fees flat sequentially, so the balance sheet is unlikely to add much despite record bank loans of $56.2 billion. Last quarter's bank margin also benefited from a one-time loan-loss reserve release, which will not repeat. Legal and professional costs tied to the putative cash-sweep class action pressured non-compensation expense and were expected to linger at a lower level. Then there is capital markets, the business that never quite arrives. Pre-tax income there was $48 million, roughly flat with the prior quarter, and management softened its description of the investment banking pipeline while citing AI-related weakness in tech, software and fintech deals. Any sign of conversion would be upside; another quarter of waiting is largely priced in.
Sentiment remains mildly bearish and only slightly less so than before the last report, a change too small to signal a real shift. The price action speaks louder. At $153.44, shares sit just above the post-earnings low of $153.19 and below the 200-day moving average of $160.60, after touching $182.73 earlier in the period. The market has effectively discounted last quarter's optimism, which lowers the bar for a positive reaction if results confirm the fee inflection but also suggests skepticism about earnings quality.
The central issue is whether the jump in fee-based assets shows up as a clear acceleration in asset management revenue strong enough to offset the missing reserve release, flat interest income and lingering legal costs. If it does, the stock's slide looks more like misplaced caution than a warning. If fees disappoint or margins slip, the record-run narrative starts to look like it depended on one-time help.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 |
Goldman, Evercore Explore Funds That Would Let PE Firms Hold Assets for 15 Years
RJF
Benzinga Private Markets
|
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-08 | |
| Oct-08 | |
| Oct-05 | |
| Oct-01 | |
| Oct-01 | |
| Sep-29 |
