Raymond James Beats On Investment Banking Rebound And Margin Upside, But Guidance Points To A Quieter Start To Fiscal 2027
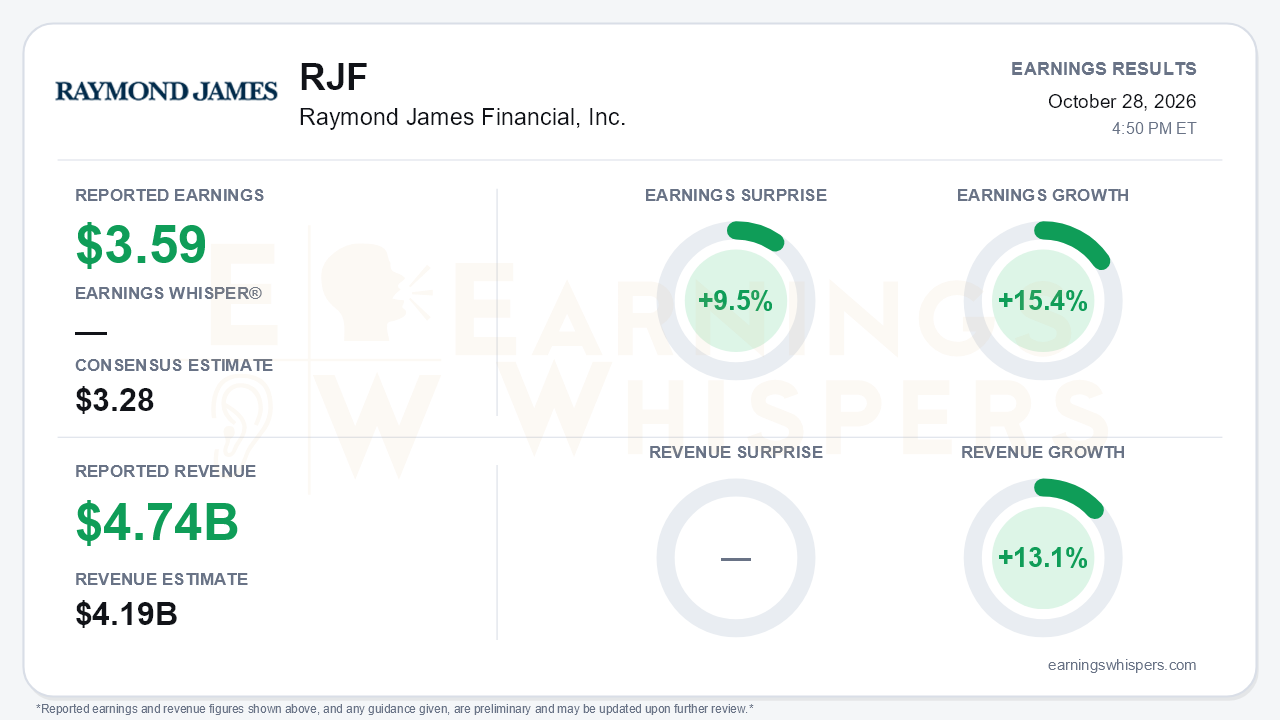
Raymond James closed fiscal 2026 with its strongest quarter on record. Adjusted earnings of $3.59 per share beat the $3.28 consensus by 9.5% and grew 15.4% year over year. Revenue of $4.739 billion topped the $4.19 billion estimate by 13.1% and also grew 13.1%. That normalized revenue figure is on a different basis than the $4.27 billion in net revenues the company highlights, which rose 15% year over year and 9% sequentially. Either way, the top line moved meaningfully higher. GAAP EPS of $3.40 excluded $37 million of after-tax acquisition-related costs. The central takeaway is that two businesses that had lagged, investment banking and margin discipline, finally delivered together. The forward guidance, however, is noticeably more restrained than the quarter itself.
The quality of the beat is better than average because it came from operating leverage, not just market appreciation. Adjusted pre-tax margin reached 21.3%, above management's roughly 20% target. That compares with 19.9% in the third quarter, 19.7% in the second and 20.0% in the first. The adjusted compensation ratio fell to 64.6% from 65.5% in the prior quarter. Capital Markets drove much of the improvement. Investment banking revenue rose 27% sequentially to $361 million, and segment pre-tax income jumped to $106 million from $48 million in the third quarter and just $9 million in the first. Asset management and related administrative fees grew 23% to $2.31 billion, lifting the Asset Management segment to record pre-tax income of $170 million. Adjusted return on tangible common equity climbed to 26.6% from 23.5%.
The call reinforced that demand is improving across the franchise. Management described sponsor re-engagement as "strong," an upgrade from "encouraging" last quarter. Fiscal-year investment banking revenue topped $1.1 billion. Domestic Private Client Group net new assets reached $98 billion for the year, up 88%, and recruited production hit $538 million. Fee-based assets ended at a record $1.16 trillion. The rate backdrop also flipped in Raymond James' favor. Early in the fiscal year, management guided net interest income and bank deposit program fees down 3%. After the September rate hike, it now expects that combined line to rise about 1% in the first quarter of fiscal 2027, versus a flat outlook a quarter ago. Securities-based loans grew 32% to $26.2 billion, and total bank loans reached a record $57.5 billion.
Bears still have legitimate ammunition, and most of it sits in the forward setup:
- **Fees:** Management guided first-quarter asset management fee growth to only about 1%, down from roughly 11% guided for the fourth quarter, because prior market gains are already in the billing base.
- **Bank margin:** Net interest margin fell 11 basis points to 2.60% as higher-cost Enhanced Savings Program deposits weighed on a full quarter. Deposit costs are rising faster than asset yields.
- **Cash balances:** Sweep and savings balances slipped to $58.0 billion from $58.8 billion.
- **Brokerage:** Fixed income brokerage was hit by municipal bond marks amid rising rates and volatility.
- **Expenses and tax:** Fiscal 2027 non-compensation expenses are guided to about $2.5 billion, up 8%, including roughly 100 basis points from acquisitions. The tax rate steps up to about 25%.
- **Wealth margins:** Private Client Group margins fell about 50-60 basis points year over year as recruiting costs and advisor payouts rose. Annual segment pre-tax income grew just 1% on 13% revenue growth.
- **Buybacks:** Repurchases were cut to $50 million from $400 million per quarter while management evaluates an M&A opportunity. That removes near-term per-share support and introduces deal-execution uncertainty.
Investors were not leaning bullish going into the print. Earnings Whispers sentiment stayed negative and edged slightly lower, from -0.15 to -0.18. Shares were $157.42, down 7.0% from the open after the July report and about 1.8% below the 200-day moving average of $160.33. The trend readings are mixed: momentum is positive, while price and AVWAP trends remain negative. That backdrop suggests the market has been discounting Raymond James' record run, likely reflecting concerns about cash sorting, deposit costs and the durability of fee growth. Those are precisely the areas where guidance remains soft.
The market setup is more complicated than the double-digit surprise implies. The quarter answered the biggest operational question, whether the banking pipeline would convert, with a clear yes. Margin and returns are moving in the right direction. Yet the first quarter of fiscal 2027 lacks the fee tailwind that powered the fourth quarter, and rising expenses and taxes will absorb some of the leverage. Capital return is now a function of a pending strategic decision rather than steady buybacks.
The bottom line is that Raymond James delivered a high-quality beat built on investment banking recovery, record advisor recruiting and margin expansion above target. Guidance points to a slower near-term earnings cadence, NIM pressure persists, and the sharp buyback cut leaves investors waiting on an undisclosed acquisition. With sentiment still negative and shares hovering just below their 200-day average, the fundamental story has improved more than the forward numbers alone suggest.
Read our earnings preview for Raymond James Financial, Inc.: https://www.earningswhispers.com/article/RJF/20983
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-23 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 |
Goldman, Evercore Explore Funds That Would Let PE Firms Hold Assets for 15 Years
RJF
Benzinga Private Markets
|
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 |
