Patterson-UTI Must Prove Its Frac Pricing Recovery Is Real After A 24% Rally
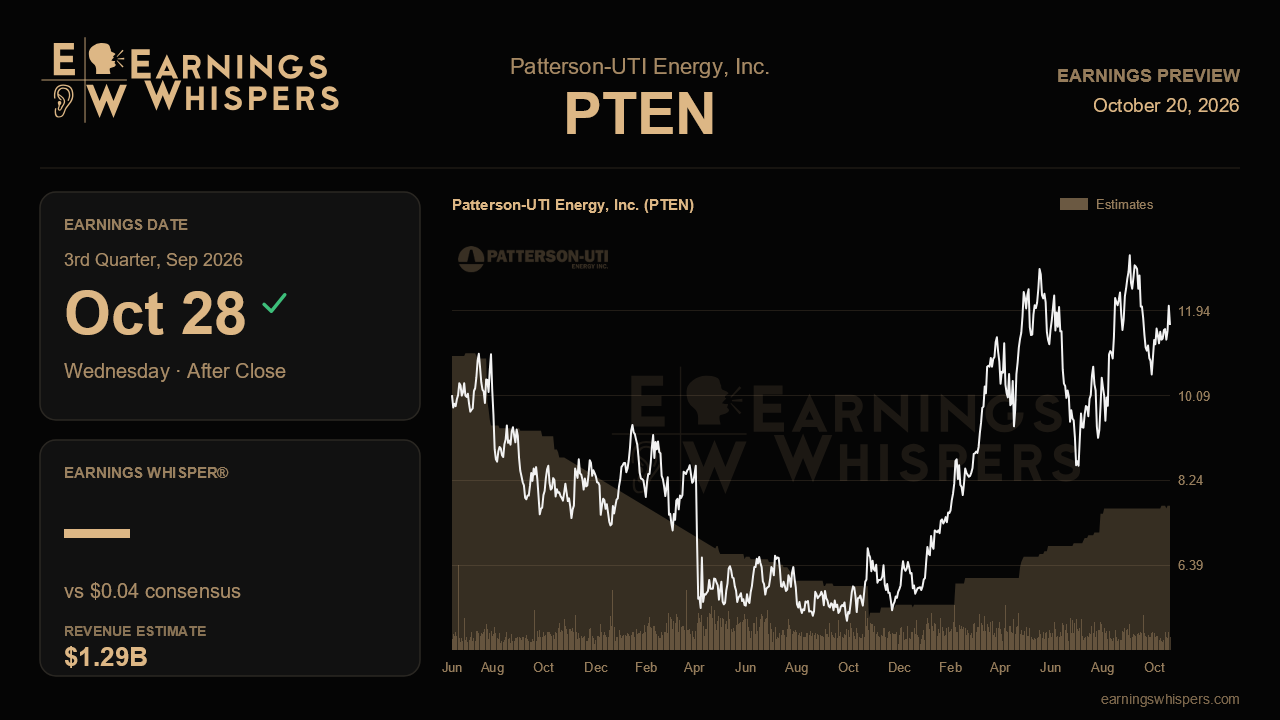
Last quarter Patterson-UTI told investors the oilfield recovery had arrived faster and stronger than even its own raised forecasts. Since then the stock has climbed about 24%, beating the S&P 500 by roughly 20 percentage points. The third-quarter report, due after the close on October 28, is the first real test of whether management's confidence turns into the margin step-up it laid out, or whether the market has paid in advance for a recovery that is still partly a matter of promising customer conversations.
The Street is looking for earnings of $0.04 a share on revenue of about $1.29 billion. That would compare with a loss of $0.06 a year ago and roughly breakeven results last quarter, when charges tied to exiting the aging Colombia drilling business pushed the company to a GAAP loss. Revenue growth of nearly 10% from a year earlier is solid but hardly explosive. The consensus implies only about 5% sequential growth after a 10% jump in the second quarter. That looks like a reasonable bar because management framed this cycle as being driven more by price than by volume. The more telling numbers will sit below the revenue line.
That is where management's segment targets come in. Patterson guided third-quarter adjusted gross profit to roughly $145 million in drilling services, about $140 million in completion services and around $40 million in drilling products. Each figure is a clear step up from second-quarter levels. Completions matter most. Gross profit there went from $98 million in a storm-hit first quarter to $123 million in the second, and management attributed most of that gain to pricing. It estimated frac pricing had fallen about 30% over three years and said it saw room to win back most or all of that decline, with further increases expected in the third and fourth quarters. Hitting or beating $140 million would support that story. Falling short would suggest customers are pushing back harder than the company let on, especially since public E&Ps remain disciplined and private operators have led the rebound.
In drilling, the checkpoints are an average rig count near 100 with a higher exit rate, and evidence that new contracts signed 10% to 15% above first-quarter rates are lifting margins. Commentary on rig upgrades also deserves attention. Management flagged 10 to 15 rigs that could be upgraded at about $2 million each on contracts of six months to more than three years, with paybacks under a year. Signed take-or-pay agreements would give real visibility into 2027. Cash flow is another quiet swing factor. Management blamed heavy first-half working capital use on the fast ramp and a billing delay tied to an ERP system cutover, and promised that drag would reverse in the second half. With 2026 capital spending raised to about $600 million to add gas-powered Emerald frac fleets, a cash inflow from working capital would ease concerns that growth spending is getting ahead of returns.
Sentiment is mildly bearish and essentially unchanged from last quarter, so the rally seems to reflect improving fundamentals more than euphoria. Even so, at $12.05 the stock trades well above its 200-day moving average of $10.30 and about 10% below its post-earnings high of $13.39. A good portion of the recovery is already priced in. Middle East logistics disruption, tungsten cost inflation in the bit business and a softer commodity strip than earlier in the year all remain risks to the outlook.
In the end, the report comes down to completions pricing. If Patterson delivers gross profit near $140 million and indicates fourth-quarter pricing is still moving up, the case that this is a multi-year recovery rather than a brief rebound stays intact. If pricing stalls while the company keeps adding gas-powered horsepower, the rally will be harder to justify.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-09 | |
| Oct-07 | |
| Sep-07 | |
| Aug-14 | |
| Aug-12 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-14 | |
| Jul-09 | |
| Jul-06 | |
| Jun-05 | |
| May-07 |
