Porch Faces Softening Homeowners Market As Street Sets Bar Below Raised Guidance
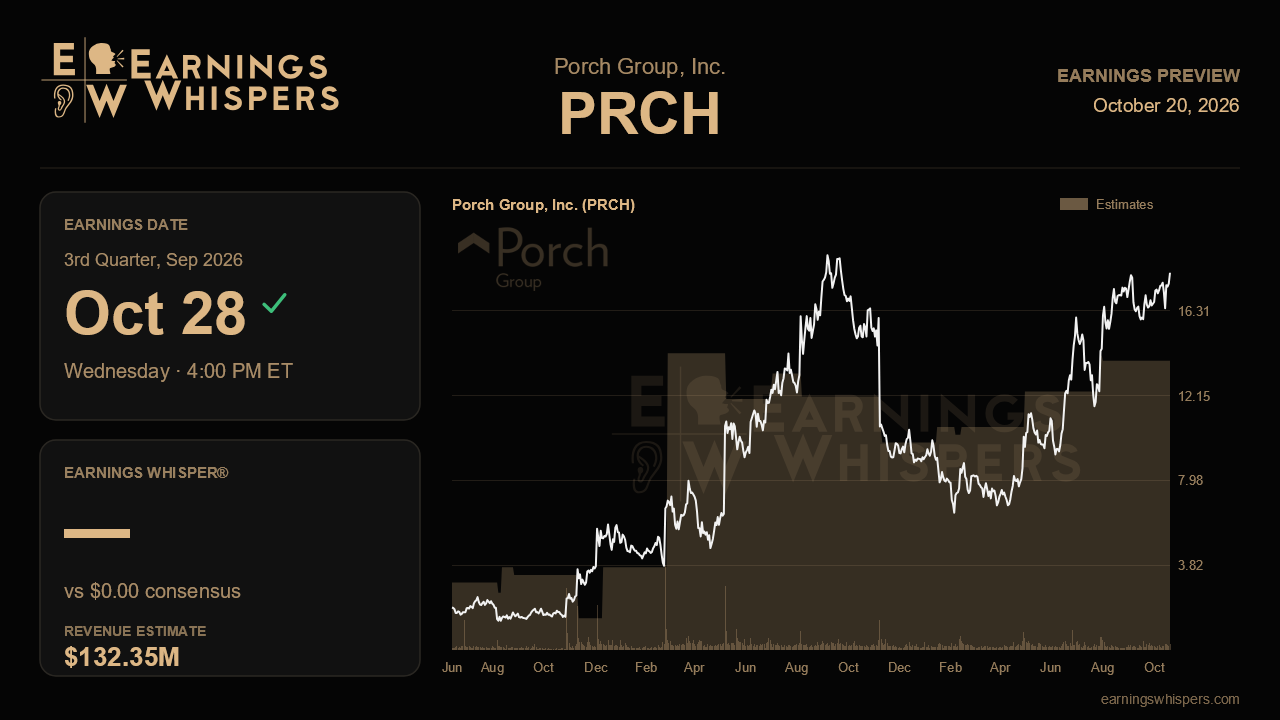
Porch Group heads into its third-quarter report with an unusual mix of momentum and caution. Last quarter brought its cleanest results yet: a first positive net income, a third consecutive increase to its profit outlook and a Rule of 50 milestone. It also brought management's first admission that the homeowners insurance market has softened, with rivals cutting prices. The October 28 release, due after the close, is the first real look at whether Porch can keep growing policies and margins while competitors chase share.
The Street's numbers look conservative. Analysts expect breakeven earnings per share on revenue of about $132.4 million, up roughly 12% from a year ago. That is a solid but unspectacular growth rate, and it implies a sequential step down from the $140.9 million reported last quarter. On profit, management has said it expects positive net income for the full year and from here on, so breakeven is a low hurdle for a company that just earned 5 cents a share. The bigger gap is in the annual numbers. Porch now guides 2026 revenue to $506 million to $517 million, raised from $495 million to $507 million, yet the full-year consensus of about $500.6 million sits below even the bottom of that range. Either analysts doubt the guide or they have not caught up. A quarter that keeps Porch on track for its range would argue for the latter.
The central operating question is premium quality, not just policy volume. Policies written grew 38% last quarter, faster than the 33% pace in the first quarter, but written premium grew only 16%, and premium per new customer fell 4%. Management held its $600 million written premium target for the year while raising nearly everything else, signaling a deliberate choice to favor policy count, fee income and margin over headline premium. If that gap between policy growth and premium growth widens further, the softening market will look less like a manageable headwind and more like a pricing squeeze. Evidence that the targeted pricing that revived conversion in June held up through the summer would support management's narrative.
Margins are the second test. The insurance services segment posted a 48% adjusted EBITDA margin, up from 37% in the first quarter, but roughly $3 million of that came from a one-time expense true-up. Some normalization is reasonable; a sharp reversal would raise questions about the full-year adjusted EBITDA outlook, now centered on $122 million after starting the year near $102 million. Third-quarter weather matters too. Statutory surplus rose to $170 million despite a $14 million storm last quarter, and further surplus growth would underpin the recently placed $100 million catastrophe bond and the balance sheet story behind leverage dropping below 3 times. Meanwhile, the software and data business and consumer services remain flat against a trough housing market, so any sign of stabilization there would be a bonus rather than a requirement.
The market has rewarded the story. Shares are up about 15% since the last report, beating the S&P 500 by roughly 11 points, and at $17.65 they trade far above the 200-day moving average of $11.62 and in the upper part of the post-earnings range, a few percent shy of the $18.37 high. Yet sentiment has drifted more bearish, to 18.5% bearish from 11.5% heading into the prior report, suggesting some investors are skeptical the run can continue as competition intensifies.
That tension frames the report. Porch does not need a dramatic beat on the headline numbers, which look beatable. It needs to show that softer pricing industrywide is not eroding the economics behind its raised guidance. Steady conversion, written premium tracking toward $600 million and insurance margins holding well above first-quarter levels would keep the beat-and-raise narrative intact. Another guidance increase would be welcome, but reaffirming the range amid a softer market might be the more telling signal.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-19 | |
| Oct-13 | |
| Oct-13 | |
| Aug-11 | |
| Jul-30 | |
| Jul-29 | |
| Jul-20 | |
| Jul-13 | |
| Jun-11 | |
| May-20 | |
| May-04 | |
| Apr-29 | |
| Apr-29 | |
| Apr-28 |
