MiMedx Must Show Its Wound Care Rebound Outlasted A Strong June
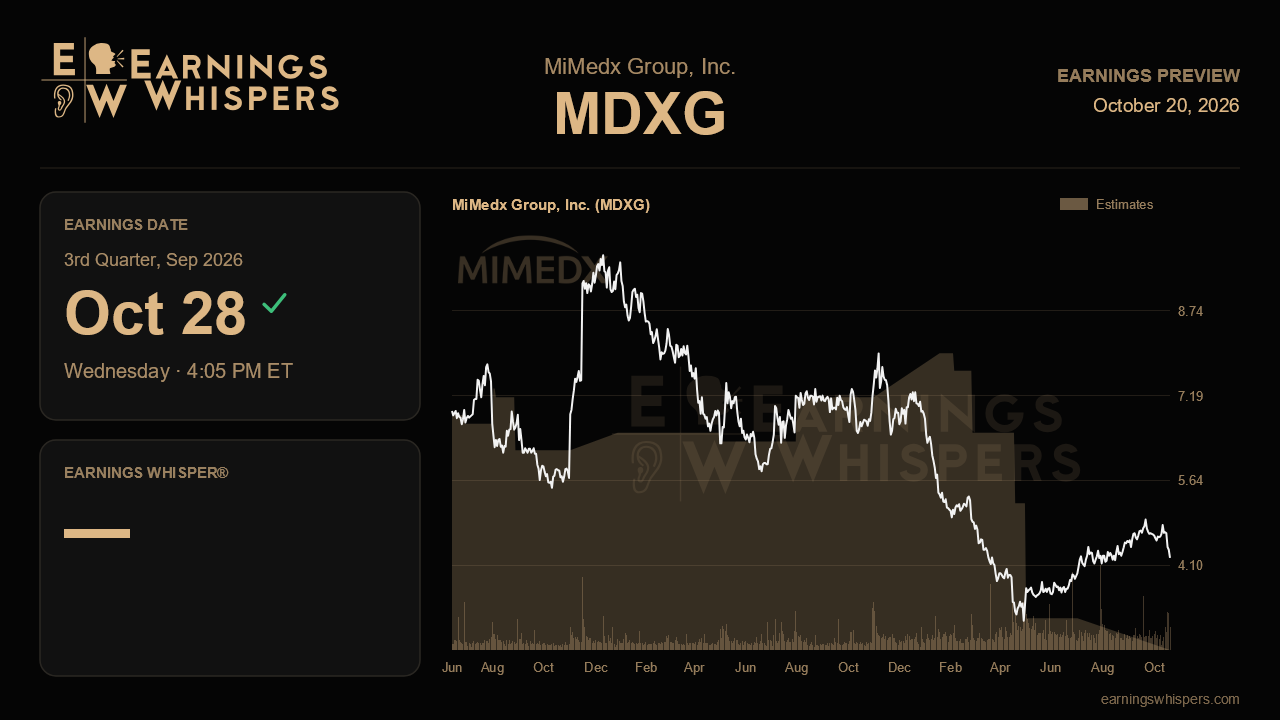
Three months ago, MiMedx finally gave shareholders something they had not heard in a while: good news about wound care. After two calls dominated by a pre-announced miss and then a severe reset, management described a business that had found its footing. Wound volumes were growing again, profitability had returned earlier than promised, and an accretive acquisition was on the table. The third-quarter report, due after the close on October 28, is the first real test of whether that turn was a trend or a single good month.
The Street's published numbers offer little help this time, since no reliable consensus for earnings or revenue is available. The year-ago comparison is unforgiving no matter what. MiMedx earned $0.15 a share on $113.7 million in revenue in the same quarter last year, a level the company will not approach. The more useful yardstick is management's own outlook. Full-year revenue guidance of $260 million to $290 million, cut sharply from $340 million to $360 million earlier in the year, was reaffirmed rather than raised last quarter. With second-quarter revenue of $64.4 million and the first quarter roughly 9% lower, the back half needs to average somewhere in the high $60 millions to the low $80 millions per quarter. Management said June's $24 million already put the company inside that range, which implies a third quarter in the low $70 millions would keep the story on track.
The operating details matter more than the headline figure. Last quarter wound care volumes rose 22% sequentially, and volumes in wound care centers jumped 44% and even grew year over year. That came after a first quarter in which management described flat month-to-month volumes with no pickup at all. Validation this quarter would look like continued sequential growth in wound care, ideally with centers holding their year-over-year gains. A challenge would come if the improvement stalls, particularly since management declined to discuss July trends. The WISER payment model remains a headwind in four states, and Medicare contractor claims processing, audits and payment callbacks are still pressuring customers, so any sign of renewed attrition would undercut the recovery thesis. Surgical, which grew 15% last quarter and has been the steadiest part of the business, needs to keep doing its job.
Profitability is the second pillar. MiMedx reached profitability toward the end of the second quarter on the back of roughly $40 million in cost reductions, ahead of the third-quarter target set earlier. A full quarter at those lower costs should produce a clean profit; a return to a loss, after a $0.05 per share loss last quarter, would raise questions about how durable the savings are. Then there is Sonara, which brings about $100 million in trailing revenue at gross margins above 90% and a $20 million synergy target, mostly from overhead. Investors should look for clarity on closing and timing, early integration progress across Sonara's roughly 1,500 active accounts, and whether management sticks with its framing of more than $400 million in combined 2027 revenue at an EBITDA margin above 20%. Share count also bears watching, since stock issued for the deal more than offset the recent buyback.
The mood has warmed but not turned bullish. Sentiment readings remain negative, though noticeably less so than ahead of the last report, and the stock has gained about 12% since then, outpacing the S&P 500 by roughly 8 percentage points. At $4.38, shares sit essentially on their 200-day moving average and in the middle of a post-earnings range of $3.76 to $4.99, a sign the market has given partial credit for the turnaround without fully buying it.
Ultimately this report hinges on whether wound care volumes kept climbing after June. If they did, the reaffirmed guidance starts to look conservative and the 2027 targets gain credibility. If they did not, the improved tone of last quarter will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-16 | |
| Oct-14 | |
| Sep-23 | |
| Sep-08 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-28 | |
| Jul-20 | |
| Jun-02 | |
| May-21 | |
| May-08 |
