MediaAlpha's Q3 Test: Can Carrier Broadening And Margin Recovery Offset Slowing Growth?
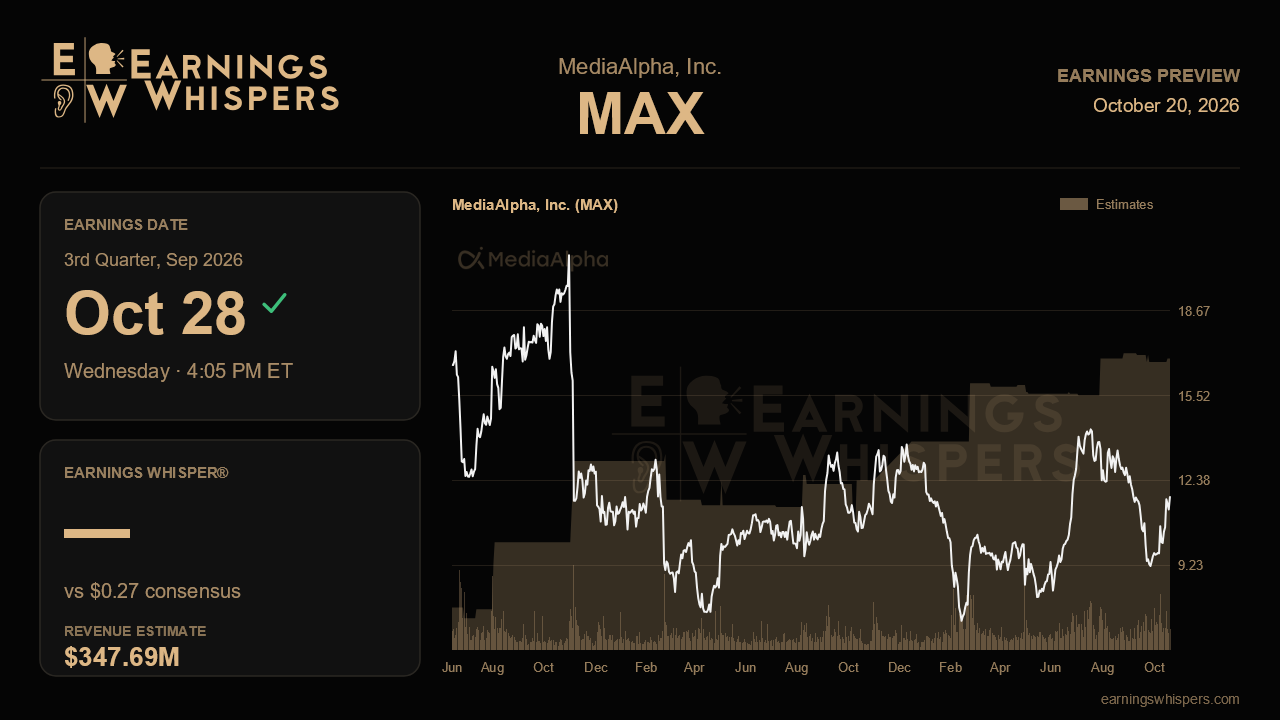
MediaAlpha heads into its third-quarter report with a puzzle that the market has not been kind to. Management left the last call sounding more confident than it has in a year, beating its own revenue range for a second straight quarter, lifting every line of its outlook and offering fresh proof that demand is spreading beyond its two biggest insurance carriers. Yet the stock has fallen about 16% since then, trailing the S&P 500 by roughly 20 percentage points. The October 28 release, due after the close, will show whether that skepticism was justified or premature.
The Street expects earnings of $0.27 a share on revenue of $347.7 million. That implies sales growth of about 13% from a year ago and per-share earnings growth of only about 4%. That is a sharp step down from the 26% revenue growth posted in the second quarter, but management telegraphed it. Executives had already warned of a more normalized growth environment and tougher comparisons in the back half. Their guidance of $330 million to $355 million centers on $342.5 million, so consensus sits a few million above the midpoint, in the upper half of the range. Given two consecutive quarters of results above the high end, that bar looks reasonable rather than heroic. Still, a landing near the midpoint would read as a break in the pattern. Note too that the prior quarter's $0.65 in earnings likely benefited from the $38 million gain on the tax receivable agreement repurchase, so the sequential drop in EPS says little about the core business.
The more revealing figures sit below the top line. In the second quarter, contribution grew just 18% while revenue grew 26%, because take rates dipped mid-quarter as MediaAlpha invested in specific partners. Management said the dip reversed by quarter end, and the guidance backs that up. The contribution forecast of $51.5 million to $54.5 million implies a margin of roughly 15.5% at the midpoint, up from about 14.9% last quarter. Adjusted EBITDA guidance of $32 million to $35 million also points to improving operating leverage. If revenue arrives near consensus but contribution slips toward the bottom of its range, the take-rate wobble starts to look less like noise and more like the cost of keeping partners engaged.
The demand-broadening story deserves equal attention. Management said the third-, fourth- and fifth-largest carriers nearly quadrupled their spending in the first half compared with a year earlier. That matters because it lowers the concentration risk that has long hung over the stock. Evidence that the momentum carried into the third quarter would support the bull case, as would further signs that ex-health revenue keeps growing well above the consolidated rate. Executives also upgraded their view of AI, describing traffic referred from large language models as now roughly equal to Google organic in volume and better in quality. A quantified update there would help turn an intriguing narrative into a measurable driver.
The balance sheet adds a quieter swing factor. After funding the TRA deal and an aggressive buyback, MediaAlpha ended June with only $23.7 million in cash and $30 million drawn on its revolver. Management has repeatedly reaffirmed its full-year free cash flow target of $90 million to $100 million. Strong third-quarter cash generation would ease liquidity concerns and keep open the option to retire the roughly $55 million of TRA liability that remains.
Sentiment has improved modestly, with readings less bearish than before the last report, and the shares sit above their 200-day moving average at $11.30, near the lower middle of their post-earnings range. The central question is whether MediaAlpha can show that slower growth comes with cleaner margins and broader customer demand. If contribution margin recovers as guided and carrier diversification holds, the recent selloff will look overdone. If take rates slip again, the market's doubts will gain credibility.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Sep-03 | |
| Jul-30 | |
| Jul-29 | |
| Jul-28 | |
| Jul-08 | |
| May-18 | |
| May-18 | |
| Apr-30 | |
| Apr-30 | |
| Apr-29 | |
| Apr-28 | |
| Apr-24 | |
| Apr-15 |
