MAA Must Prove Its Promised Third-Quarter Leasing Pickup As Shares Sink Near Lows
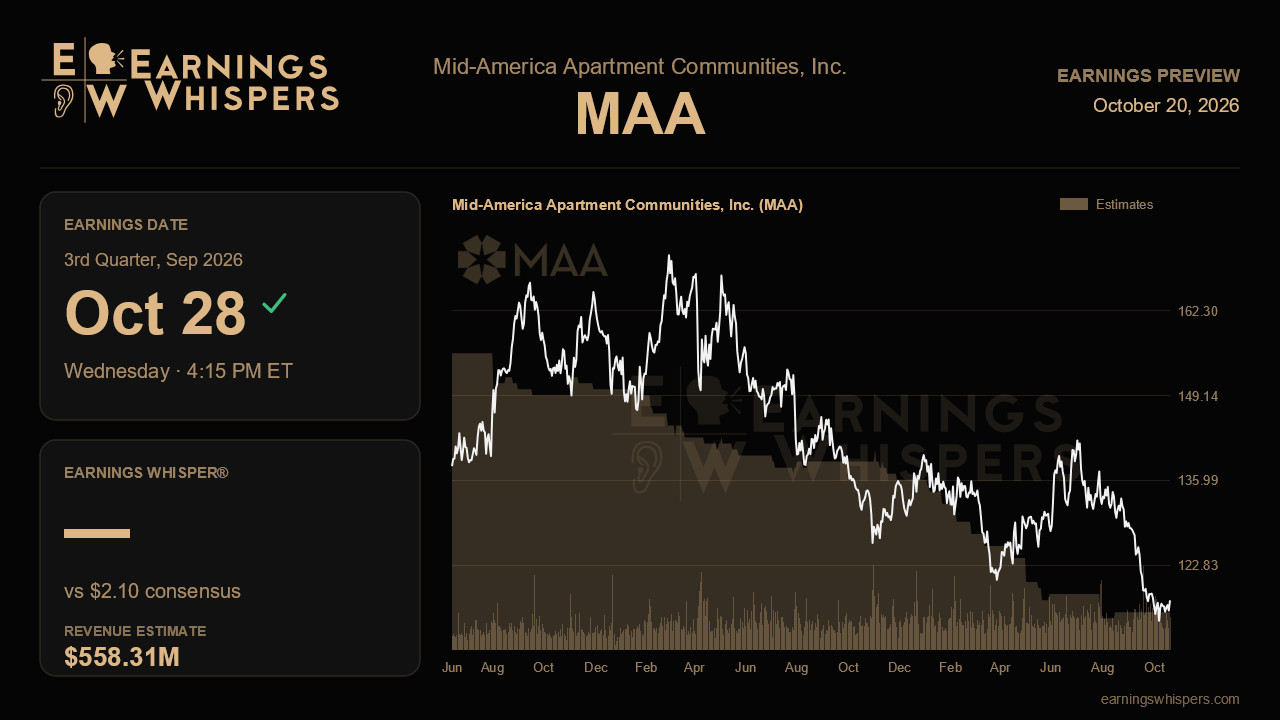
Mid-America Apartment Communities enters its third-quarter report with a promise to keep and a skeptical market to win back. Last quarter, management made an unusual call: blended lease growth in the third quarter would beat the second, a pattern the Sunbelt apartment landlord had not delivered in the prior four years. Since then the stock has fallen 13.8% while the S&P 500 gained 4.1%, so the market is not giving that forecast much credit. This release will show whether the extended leasing season management described actually happened.
The Street expects core FFO of $2.10 per share on revenue of $558.3 million. That would be a small gain from the $2.08 reported last quarter but a 2.8% decline from the year-ago $2.16. Revenue is projected to grow just 0.7%. In plain terms, this is a flat-to-slightly-down quarter, and nobody is pricing in a turnaround yet. Management recently narrowed its full-year FFO range to $8.41 to $8.65 per share, keeping the $8.53 midpoint it has now held through four straight calls. Consensus of $8.51 sits comfortably inside that range and just below the midpoint, which suggests analysts accept the outlook but are leaving a little room for disappointment.
How MAA has held that midpoint matters more than the number. Last quarter the revenue outlook weakened again. Blended lease growth for the year is now tracking about 0.5%, well short of the 1.0% to 1.5% management first guided to, and both effective rent growth and average occupancy were trimmed. Cost savings filled the gap. Same-store operating expense growth was cut to roughly 1.75% from a 2.65% midpoint, helped by a 12% drop in insurance premiums at the July renewal. Lease-up properties also contributed, with more than $25 million in added NOI expected this year. That is a respectable result, but expense relief has a limit, and property taxes could rise as valuations recover into 2027. At some point revenue has to carry the load.
That makes new-lease pricing the main thing to watch. Management pointed to signs of firming demand: in-migration to its properties jumped to about 13% from 10%, absorption ran at 1.8 times new deliveries, and leads and visits rose 10% to 15%. Renewals held at 5.2% with record-low turnover. A third-quarter blended figure clearly above the second quarter, along with occupancy holding steady, would support the view that demand is finally showing up in pricing. A flat or weaker blend would fit a frustrating pattern of new-lease shortfalls going back to last year's guidance cut. Updates on Charlotte, where lease-ups still offer eight to ten weeks of concessions, and on supply-heavy Phoenix, Raleigh, Savannah and Nashville will help show how broad any recovery is.
Smaller growth drivers deserve a look too. Renovations are earning 25% cash-on-cash returns against a 19% target, Wi-Fi revenue rose from $500,000 to $850,000 between the first and second quarters, and the development pipeline is moving toward roughly $1 billion. None of these will change the quarter on its own, but continued progress would show earnings drivers beyond pure rent growth.
Sentiment has soured, with bearish readings rising to 48.7% from 42.8% before the last report. The stock trades at $115.80, barely above its post-earnings low of $113.95 and far below its 200-day average near $130. The entire current trading range sits below the prior quarter's $125 floor. The bar is therefore low, but the central question is narrow. If MAA shows that third-quarter leasing truly accelerated, the steady $8.53 midpoint starts to look like it rests on revenue rather than cost cuts. If the blend stalls again, investors will likely conclude that savings are hiding a recovery that keeps getting pushed out.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-19 | |
| Oct-07 | |
| Sep-22 | |
| Sep-10 | |
| Aug-28 | |
| Aug-06 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-01 | |
| Jun-01 | |
| Jun-01 | |
| May-19 |
