Houlihan Lokey Must Show Its Corporate Finance Slump Was A Delay, Not A Downturn
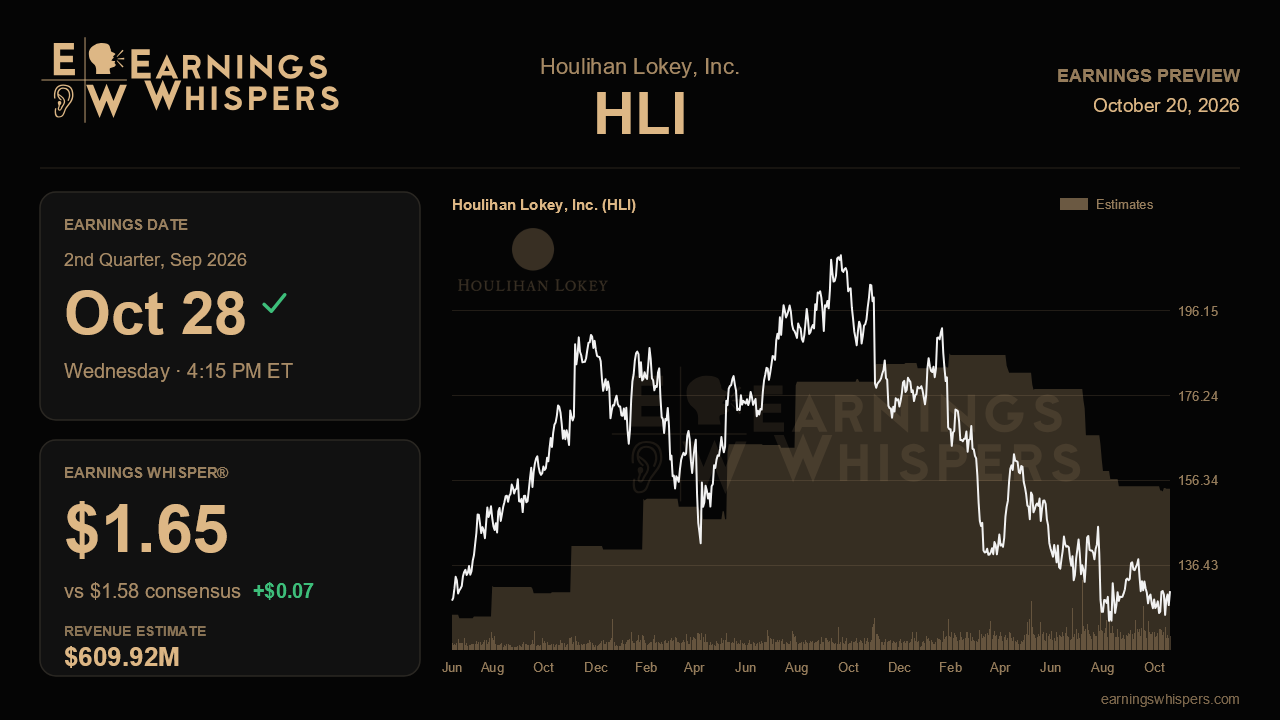
Last quarter Houlihan Lokey asked investors for patience. Corporate Finance revenue fell 24% from a year earlier to $303 million, larger-fee deals slipped into later periods, and management described the quarter as a weather delay rather than a change in the season. The fiscal second-quarter report on October 28 is where that argument gets tested. If the delayed deals were truly only postponed, some of them should start closing now, and the numbers should show it.
Wall Street is positioned for a partial recovery. Consensus calls for earnings of $1.58 per share on revenue of $609.9 million. That would still be a contraction from a year ago, with EPS down about 14% and revenue down roughly 7.5%. Against last quarter's $1.35 and $511 million, however, it implies a sequential rebound of nearly 20% in revenue. The Earnings Whisper of $1.65 sits modestly above consensus, which suggests the more engaged part of the market expects a little more catch-up than the published estimates. That is a meaningful nudge, but not a demand for a blowout. The company did not offer formal quarterly guidance, so management's qualitative claims carry the burden of proof.
The most important figure will be the average Corporate Finance fee, more than the deal count. Last quarter's transaction volume held flat at 127, and the damage came almost entirely from smaller average fees as big mandates stretched out. A rebound in average fee size would be the cleanest evidence that the pipeline is converting. Management also said backlog and new business activity were at record levels, up 13% year over year, and that deals going dead or on hold had not risen meaningfully. If backlog stays near those highs while revenue recovers, the delay framing holds. If revenue stays depressed and backlog quietly slips, the market will start to suspect the deals are slipping away rather than slipping later.
Two specific weak spots deserve attention. Technology and software revenue collapsed by more than half last quarter as AI-related disruption forced buyers and sellers to rethink valuations. Even partial stabilization there would help, because software has been a large fee pool. Europe, which had been a source of strength, has lagged the U.S. since late fiscal 2026, and any sign of improvement would broaden the recovery case. Middle East volatility is another variable, since management cited it as a drag earlier in the year and flagged the risk of renewed disruption.
The offsets give the company some room. Financial restructuring has been running at elevated levels, helped by energy volatility, private credit strains and stress among software borrowers, and management kept that outlook intact. Financial and Valuation Advisory grew across all three service lines with fee events up 9%. The Intrepid Financial acquisition, which adds 32 energy-focused bankers, was expected to close by the end of this quarter, so confirmation of the deal and early commentary on its contribution would show the firm is still investing through the soft patch. Management also held firm on its 61.5% compensation ratio, and keeping that line on a still-reduced revenue base would show cost discipline rather than margin erosion.
Investor mood has barely moved. Sentiment remains mildly bearish and essentially unchanged from before last quarter's report. The stock has gained 5.8% since then, slightly ahead of the S&P 500, but at about $127 it sits in the middle of its post-earnings range and well below its 200-day moving average near $147. The entire trading range has shifted lower than the prior quarter's, so the market has stabilized without fully forgiving the miss. The central question is whether Corporate Finance fees start to recover in step with the record backlog. A sequential rebound led by larger deals would restore the long-term story, while another quarter of shrinking fees would make the delay explanation much harder to accept.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-08 | |
| Oct-07 | |
| Oct-05 | |
| Sep-30 | |
| Sep-28 | |
| Sep-22 | |
| Sep-17 | |
| Sep-16 | |
| Sep-15 | |
| Sep-15 | |
| Sep-10 | |
| Sep-08 | |
| Sep-02 | |
| Aug-10 |
