Houlihan Lokey Rebounds From Its 'Rain Delay' Quarter As Corporate Finance Fees Drive A Large Beat, But Flat EPS Growth And Thinner Deal Counts Temper The Recovery
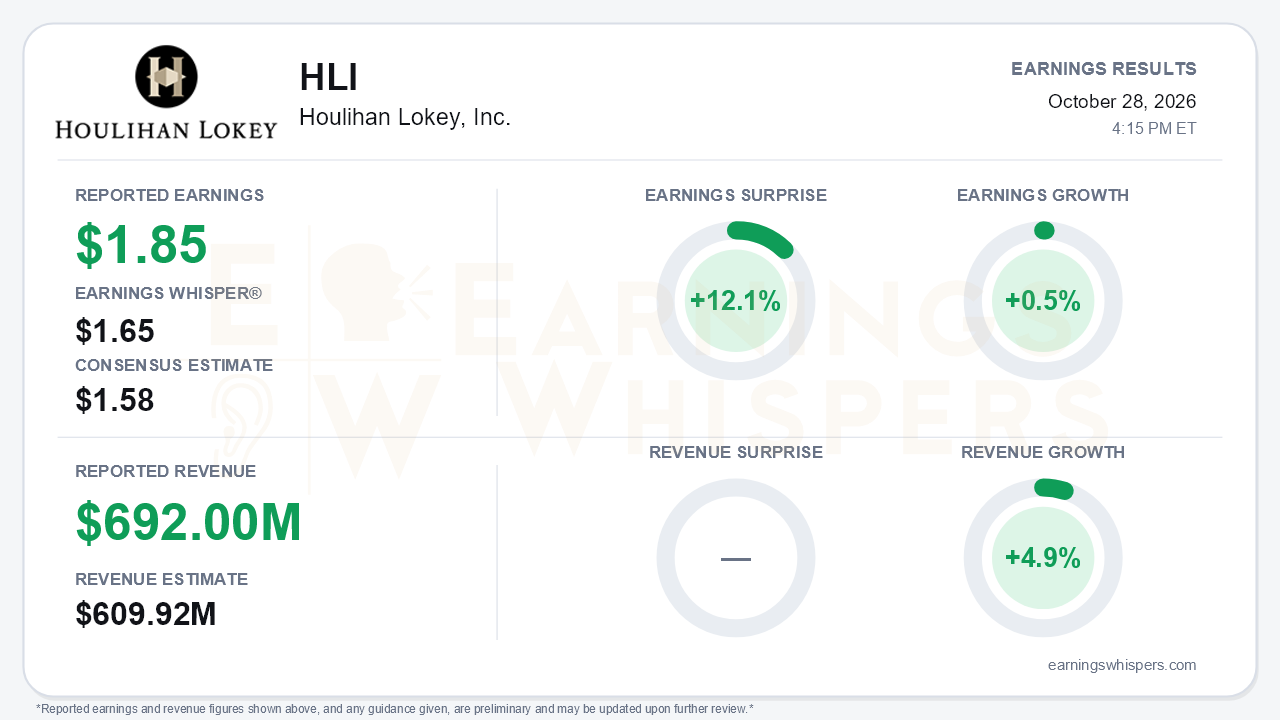
Houlihan Lokey delivered the rebound its weak fiscal first quarter had put in doubt. Adjusted earnings of $1.85 per share beat the $1.58 consensus by 12.1% and cleared the $1.65 Earnings Whisper number. Revenue of $692.0 million topped the $609.92 million estimate by 13.5%. The trajectory change is the real story. Revenue grew 4.9% year over year after a steep first-quarter decline, when sales were just $511 million and Corporate Finance fell 24%. Adjusted EPS jumped from $1.35 in Q1. Year-over-year earnings growth, however, was only 0.5%. That is the central tension: the expectations beat was decisive, but the earnings power is recovering to last year's level rather than exceeding it.
The quality of the beat deserves scrutiny. Corporate Finance revenue rose 10% to $481 million, yet closed transactions fell to 142 from 171. Management attributed the gain to higher average fees, citing transaction mix and better M&A and capital markets conditions. Fewer, larger deals can be a sign of selectivity and improving deal sizes. They also make revenue lumpier. Year to date, Corporate Finance revenue is still down about 6% and deal count about 9%.
Below the revenue line, little leverage reached the bottom line. The adjusted compensation ratio held at 61.5%. The adjusted non-compensation ratio climbed to 13.3% from 12.5% on higher rent and operating costs. Other income fell to $5 million from $9 million. Adjusted operating income edged up only to $175 million from $171 million. A lower diluted share count of 67.0 million, versus 68.9 million, did some of the work in keeping EPS above last year. On a GAAP basis, EPS was $1.64 versus $1.63.
The segment mix also shifted. Financial Restructuring revenue fell 12% to $118 million as closings dropped to 27 from 37, which the company attributed to timing. The call analysis cites a +7% year-over-year figure for restructuring that conflicts with the release's $134 million prior-year comparison. The release figures are the more reliable reference. On either basis, restructuring was essentially flat with Q1's $119 million and well below the $156 million peak in fiscal Q3 2026. Financial and Valuation Advisory grew 7% to $93 million on non-cyclical portfolio valuation work, even though fee events were roughly flat.
The call preserved a credible growth story, and management's forward language improved across almost every dimension:
- **Second half:** Management guided to an "unseasonably" strong second half. The CFO called the $481 million Corporate Finance quarter a "good solid base to grow off of."
- **Backlog:** It points to growth across all three businesses and every industry group except technology/software and healthcare.
- **Europe:** After lagging in Q1, Europe is expected to match U.S. growth by year-end.
- **Restructuring outlook:** This shifted the most. A year ago management was flagging revenue pressure for fiscal 2027. It now expects a stronger second half and elevated activity through fiscal 2028. Management sized a coming software-sector restructuring wave as larger than the fiscal 2017 oil and gas cycle, with revenue expected in calendar 2027-2028.
- **Talent:** The Intrepid Financial Partners acquisition closed in September, contributing 8 of 12 new managing directors. Corporate Finance MD headcount reached 267 versus 242 a year ago.
Bears have legitimate ammunition. Software, a key part of the bullish restructuring narrative, is still a drag on Corporate Finance. Management repeatedly said it needs "cooperation in the markets" amid higher rates and geopolitical volatility. Cash and investments fell to $888 million from roughly $1.4 billion at fiscal year-end. That decline came alongside seasonal bonus payouts, about $50 million of buybacks, and the Intrepid deal. Guidance for a 61.5% comp ratio, a 26%-28% tax rate, and similar non-comp growth was unchanged, so margin expansion is not part of the near-term pitch.
The market setup is more complicated than the surprise implies. Investor sentiment improved modestly ahead of the report, from -0.14 to -0.10, but remains negative. Shares entered the print at $132.35, up 10.2% since the open after the July report. That July open came on the same day the stock set a 52-week low of $112.83. The stock is still about 9% below its 200-day moving average of $145.46 and 6.2% below its September inter-earnings high of $141.08. The Earnings Whispers trend readings are mixed: sequential growth and AVWAP are positive, while momentum remains negative. That mix fits a stock that has bounced but has not yet regained longer-term favor.
The bottom line is that Houlihan Lokey's quarter decisively reset the near-term narrative. Corporate Finance came back, restructuring visibility now extends into fiscal 2028, and management is guiding to a better-than-seasonal second half. Even so, flat year-over-year EPS, shrinking deal counts, and a rising non-comp ratio show the recovery is still being carried by fee size and outlook rather than broad-based volume. With sentiment still slightly negative and shares below their long-term average, investors appear willing to believe the rebound but have not fully priced the restructuring and second-half story management laid out.
Read our earnings preview for Houlihan Lokey, Inc.: https://www.earningswhispers.com/article/HLI/20946
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 |
Goldman Sachs and Houlihan Lokey lead North American M&A financial advisers in Q1Q3 2026
HLI
Private Banker International
|
| Oct-23 |
Goldman Sachs and Houlihan Lokey lead M&A adviser rankings for Q1-Q3 2026
HLI
Private Banker International
|
| Oct-20 | |
| Oct-08 | |
| Oct-07 | |
| Oct-05 | |
| Sep-30 | |
| Sep-28 | |
| Sep-22 | |
| Sep-17 |
