GBank Must Prove Credit Costs Have Peaked As Card Volumes Shrink And Axis Deal Ramps
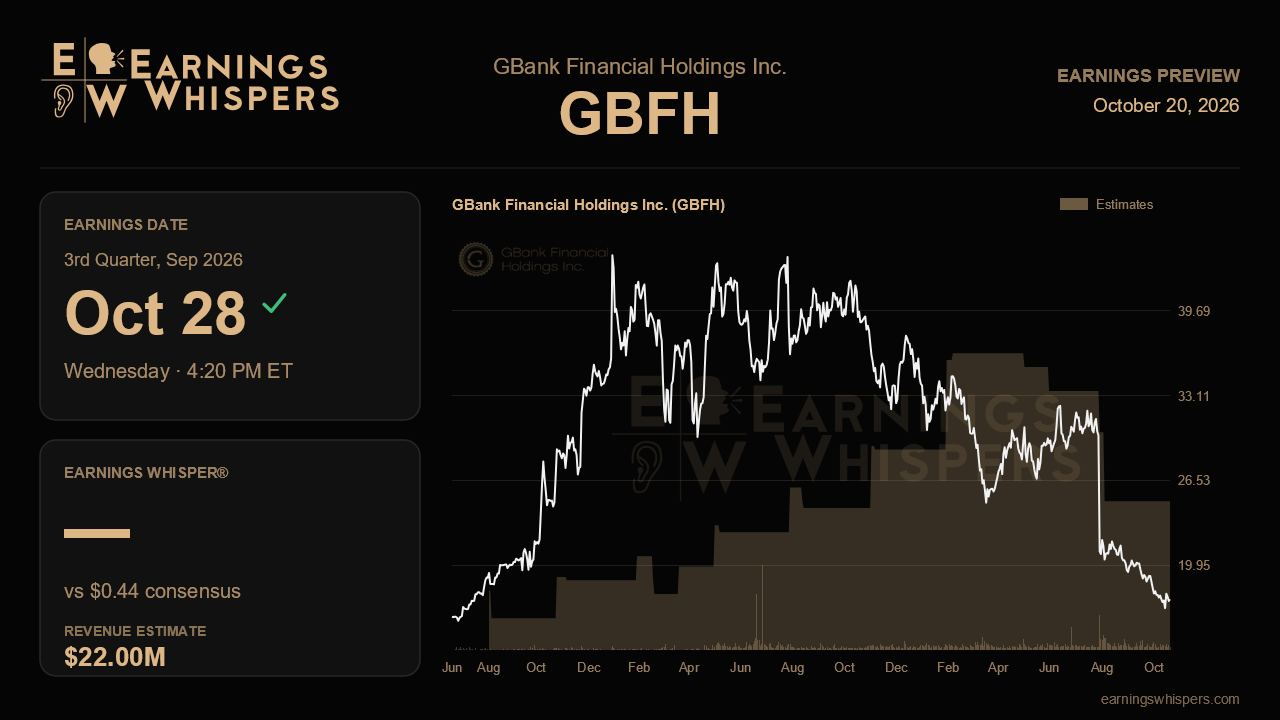
GBank Financial Holdings heads into its third-quarter report with a stock that has lost nearly 40% since its last update and a story that has split in two. The long-term pitch, built on a high-margin SBA lending franchise and a growing gaming-payments platform, arguably got stronger last quarter. The near-term numbers got worse, with a shrinking net interest margin, a jump in problem loans and a credit-card business still losing volume. When the Las Vegas lender reports after the close on October 28, the question is whether the deterioration has stabilized or is still compounding.
The Street is looking for earnings of $0.44 a share, flat with a year ago and up from the $0.38 GBank earned last quarter. Revenue is expected at $22.0 million, down 23.6% from the year-ago $28.8 million and well below the prior quarter's $31.9 million. That combination is unusual. Analysts are effectively betting that a much smaller top line can still produce better per-share profit, which implies lighter provisions, tighter expenses or both. Management did not provide formal guidance, so the call commentary is the best guide to whether that math holds up.
Credit is the swing factor. Reported nonperforming assets climbed to about $60 million last quarter, with the at-risk portion rising to roughly $23 million from $13.2 million a quarter earlier. Provision expense rose to $2.8 million, partly because retail cardholder delinquencies added about $771,000. Management tied much of the stress to a maturing hotel and SBA portfolio and said it was doubling down on special assets. The report validates that approach if at-risk balances hold steady or shrink and provisions ease. Another step up in nonperformers would undercut the earnings estimate and suggest the problem loans are a trend, not a single bad quarter.
Margin and card volume are the other two pressure points. Net interest margin slid from 4.33% for fiscal 2025 to 3.78% last quarter, and management brought in an outside consultant to help improve it. Even a modest stabilization would be encouraging. Card transaction volume has collapsed from a peak near $330 million to $84.2 million after major sportsbooks stopped accepting credit-card loads, and management warned of further shrinkage into late in the fourth quarter. Another decline is expected. The real question is whether the shortfall lands roughly as signaled or worse.
The offsets are real. SBA gain-on-sale income nearly doubled in the first half to $9.3 million, with margins running above management's 4% target and originations of $131.4 million last quarter. Continued production at that pace would show the core engine is intact. The newer catalyst, the Axis AI and Bankroll white-label agreement covering 67 gaming operators in 12 states, needs early proof: progress integrating the first operator and its roughly 3,000 slots, movement on the Terribles rollout after its Nevada approval, and a firm timeline for the Visa prepaid card planned for the fourth quarter. These are still deposit and fee stories for later periods, but signs of traction would matter. Leadership is also a concern. With the CFO not returning, the COO's role unfilled and a new bank CEO settling in, any clarity on a permanent finance chief would help.
The market has clearly braced for trouble. Bearish sentiment has deepened from last quarter, and the shares, at $17.17, sit far below the 200-day average of $27.12 and only a few percent above their post-report low of $16.51. That low bar cuts both ways. Results showing credit costs topping out and the SBA business carrying the quarter could ease the pressure. But a stock this close to its lows can still fall further if nonperforming assets rise again. Above all, this report needs to show that GBank's credit problems are contained, so the gaming and SBA growth story can again outweigh the near-term damage.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-19 | |
| Sep-22 | |
| Jul-30 | |
| Jul-29 | |
| Jul-23 | |
| Jul-20 | |
| May-19 | |
| Apr-29 | |
| Apr-28 | |
| Apr-20 | |
| Jan-29 | |
| Jan-28 | |
| Jan-28 | |
| Jan-27 |
