Franklin BSP Must Prove Its Dividend Coverage Survives Shrinking Loans And Stalled Agency Volume
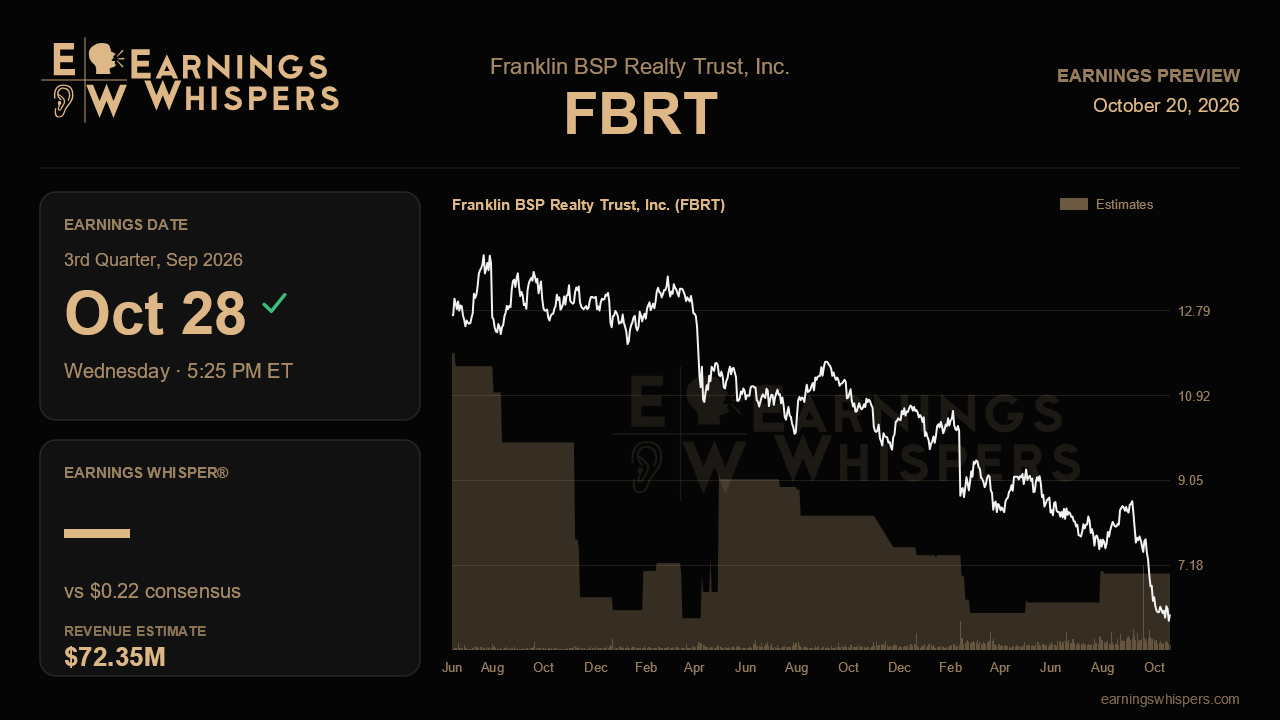
Franklin BSP Realty Trust heads into its third-quarter report with a striking disconnect. Last quarter, management described a business that was quietly getting healthier: the dividend was covered for a second straight quarter, book value per share edged up to $14.24, and the share of legacy, pre-rate-hike loans fell to roughly 23% of the book. The market has responded by knocking the stock down about 25% since that report, a gap of nearly 30 percentage points versus the S&P 500. At $5.95, the shares trade near 0.42 times last reported book value. Either investors are anticipating trouble that management has not yet acknowledged, or the report has a real opportunity to reset the conversation.
The Street is looking for earnings of $0.22 per share on revenue of $72.4 million. That EPS figure would be up about 29% from $0.17 a year ago and from $0.17 last quarter, while revenue is expected to fall roughly 19% from $89.5 million a year earlier, though it would improve on the $65.3 million booked last quarter. The combination says a lot: analysts expect earnings quality to keep improving even as the top line contracts. A $0.22 result would also clear the $0.20 dividend, which matters more than the headline beat or miss for a REIT priced like this one. No updated company outlook is available to anchor that estimate, so the bar rests on the trajectory management laid out last time.
That trajectory has a soft spot. Distributable earnings before realized losses jumped to $0.28 last quarter from $0.22, but a meaningful piece came from an outsized conduit contribution that management itself did not frame as repeatable. Realized losses also fell sharply, to about $1.9 million from $12.3 million. If both tailwinds fade at once, the step-up could prove temporary. Evidence that recurring sources, particularly the roughly $60 billion servicing book that has been growing steadily, are carrying more of the load would validate the improving narrative. Another quarter dependent on one-time items would weaken it.
The revenue engines are the bigger worry. NewPoint agency originations slid to about $399 million from $2.2 billion a year earlier, and management effectively conceded that its $4.5 billion to $5.5 billion full-year target is out of reach. The core loan book shrank to about $4.3 billion as repayments of $458 million swamped $167 million of new loans, moving away from the $5 billion to $5.5 billion goal rather than toward it. With about $800 million of liquidity and net leverage of just 2.6 times, the company has room to redeploy. The question is whether a stubborn rate backdrop, which management flagged as now pressuring earnings, lets it do so profitably. Any stabilization in agency volume or net portfolio growth would be meaningful. The first CMBS B-piece purchase in years is worth tracking as a sign of where capital is heading.
Credit is the swing factor behind the selloff. Last quarter brought a $5.2 million CECL provision tied to macro deterioration, a watch list that grew to 12 loans, a 2025-vintage Houston loan returning to REO for a second time, and roughly $250 million of equity still tied up in underperformers. Sentiment has turned decisively, with bearish readings near 60% compared with about 22% ahead of the last report. The stock sits just above its post-earnings low of $5.90 and far below its 200-day average of $8.53, so the market is clearly bracing for bad credit news.
Ultimately, this report will be judged on whether the dividend remains covered without help from one-off gains while the watch list and reserves hold steady. Management bought back stock near $8.70, well above today's price, and further repurchases at this discount would signal real conviction. If credit holds and earnings clear $0.20, the deep discount to book looks overdone. If provisions climb and the loan book keeps shrinking, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-07 | |
| Sep-17 | |
| Sep-10 | |
| Sep-04 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| Jun-17 | |
| Apr-30 | |
| Apr-29 | |
| Apr-29 | |
| Apr-15 |
