Eldorado Gold's Q3 Test: Can Scouries And MacBay Turn Milestones Into Cash Flow?
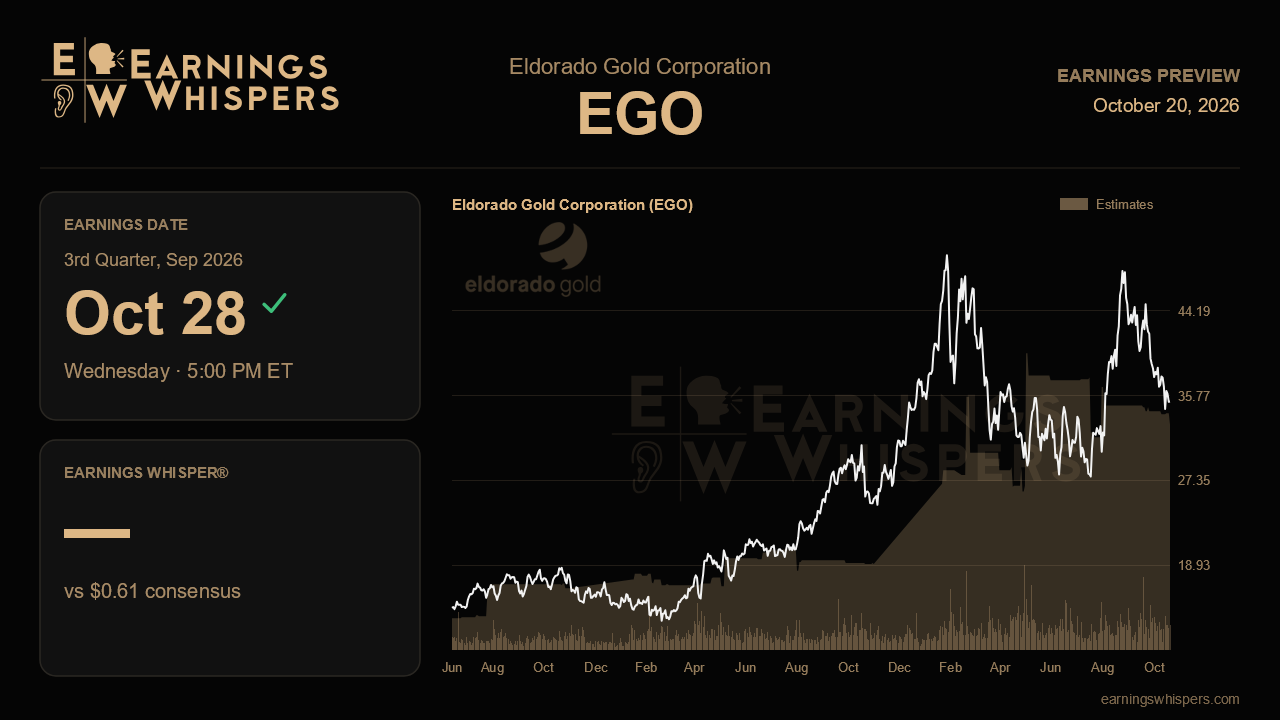
For two years the Eldorado Gold story was about budgets that kept rising and schedules that kept slipping. Last quarter that changed. MacBay shipped its first copper and zinc concentrate, Scouries crushed its first ore, and management spoke with noticeably more conviction about reaching commercial production at both. The third-quarter report, due after the close on October 28, is the first real chance to see whether those milestones were a turning point or simply a good press cycle.
The Street is leaning toward the former. Consensus calls for earnings of $0.66 per share, up about 61% from $0.41 a year ago and a solid step above the $0.54 posted last quarter. Revenue reached $487.5 million in the second quarter versus $434.7 million in the year-ago third quarter, with a realized gold price near $4,379 an ounce doing much of the lifting. That matters because gold output actually fell to 105,000 ounces in the second quarter on planned lower grades at Kisladag and Efemcukuru. In other words, the earnings growth so far has been price-driven. A quarter in which new production starts to contribute, rather than just bullion prices, would be a higher-quality beat.
The operational checklist is unusually concrete. Management targeted MacBay commercial production in the third quarter, with the mill running at roughly 70% of design throughput when operating, so evidence of steadier run time and a formal commercial declaration would validate the narrative. At Scouries, the company was confident of first concentrate during the quarter and commercial production in the fourth, backed by about 4 million tonnes of stockpiled ore and 36 megawatts of gensets to cover any delay in the grid connection expected by late August. Confirmation that power is connected and concentrate is flowing would go a long way. Any new slip, or another revision to the $1.315 billion Scouries capital estimate that held steady last quarter, would revive the old story quickly.
There is an accounting wrinkle worth understanding. The timing of commercial production determines when ramp-up costs stop being capitalized and start hitting the income statement. A clean declaration is good news operationally, but early-stage unit costs at a new mine are rarely flattering, so a near-term earnings drag would not by itself signal trouble. More telling will be cash. Free cash flow was negative $334 million last quarter at peak growth spending, total debt sits around $1.75 billion, and project debt servicing begins at the end of 2026. Management expects both projects to inflect to positive free cash flow by year-end, so a visibly narrowing burn this quarter is the evidence that matters most. Labor tightness around Flin Flon, a heavy stripping year at Kisladag, and a CEO handoff from George Burns to Christian Milau mid-ramp are the secondary risks to monitor.
Sentiment has swung sharply. Heading into last quarter's report, readings were about 68% bearish; they now sit modestly bullish at roughly 17%. The stock has gained 12.5% since the last report, beating the S&P 500 by nearly 10 percentage points, yet the path was volatile. Shares ran as high as $48.37 before sliding back to $35.15, below the 200-day moving average of $37.03 and closer to the bottom of the post-earnings range than the top. That retreat suggests some enthusiasm has already been wrung out, leaving room for a reassuring report to rebuild momentum.
Ultimately, this quarter is about whether Eldorado has truly moved from builder to producer. If MacBay is declared commercial, Scouries is producing concentrate on schedule, capital costs hold, and cash burn eases toward the promised year-end inflection, the de-risking thesis stays intact even if headline earnings are noisy. Another delay or cost increase would tell investors that the balance sheet is carrying more risk than the improving tone implied.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-09 | |
| Sep-28 | |
| Sep-22 | |
| Sep-21 | |
| Sep-15 | |
| Sep-09 | |
| Sep-08 | |
| Aug-21 | |
| Aug-14 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
