Everforth's 56% Rally Leaves Little Room For Error As Flat Sales Must Deliver Fatter Profits
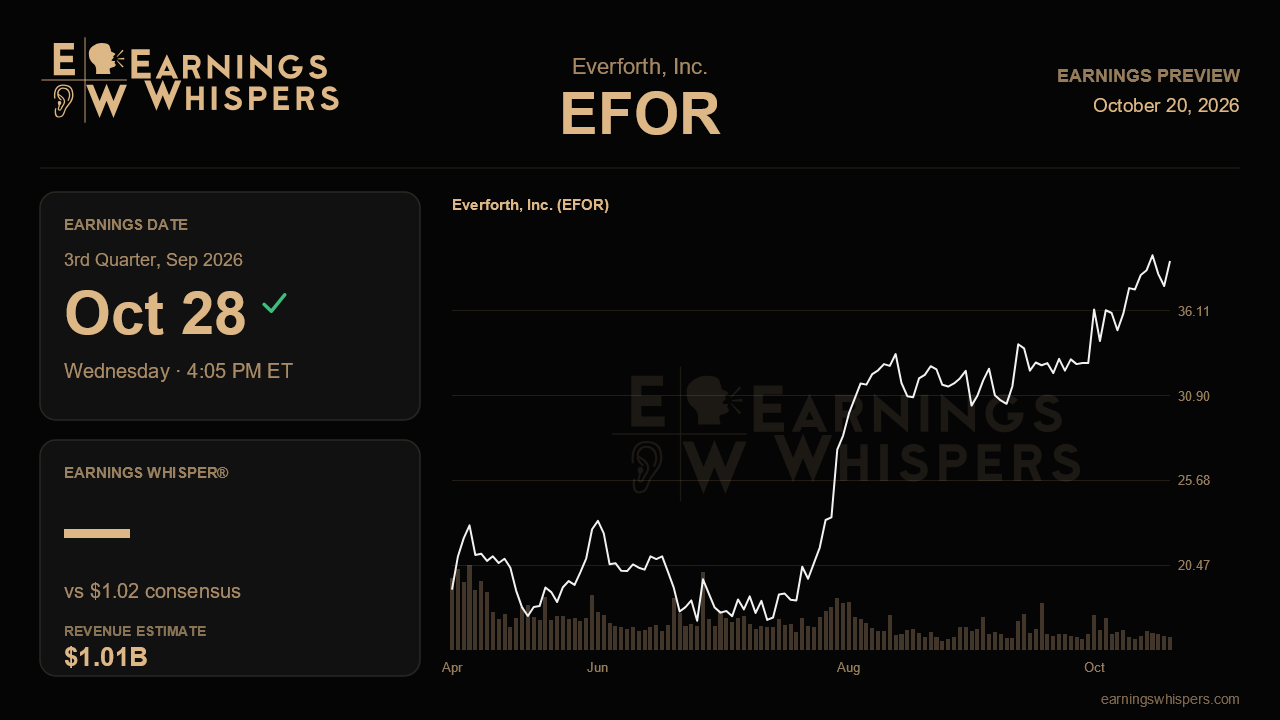
Everforth heads into its September-quarter report with the market having already rendered a verdict. Since its last earnings release, the stock has climbed nearly 56%, while the S&P 500 managed about 4%. A move of that size in an IT services company is rarely about one quarter's numbers. It usually reflects a belief that the business has turned a corner. The October 28 report, due after the close, is the first real chance to test whether that belief rests on operating results or mostly on hope.
The Street's math points squarely at profitability rather than growth. Consensus calls for earnings of $1.02 per share on revenue of roughly $1.01 billion. That revenue figure is essentially identical to the $1.01 billion the company posted last quarter, yet the earnings estimate sits about 12% above the prior quarter's $0.91. In other words, analysts are not counting on a demand surge. They are counting on Everforth wringing considerably more profit out of a steady top line. That puts the spotlight on gross margin, the mix of higher-value consulting and solutions work versus commodity staffing, and how tightly the company is managing overhead. Absent fresh company guidance to anchor these numbers, the consensus effectively serves as the benchmark, and it already assumes meaningful operating leverage.
The company's two segments matter here because they carry different risk profiles. The Commercial business, which serves Fortune 1000 and large enterprise clients, tends to reflect corporate appetite for discretionary technology projects. Any sign that clients are restarting delayed initiatives, particularly around AI, cloud and digital transformation, would support the idea that the rally is anticipating a genuine recovery in spending. The Federal Government segment, which sells cloud, cybersecurity and AI/ML capabilities to agencies, is more about contract timing, award flow and funding stability. A quarter in which commercial demand firms up while federal work holds steady would validate the bullish case. A quarter in which revenue is merely flat because one segment is offsetting weakness in the other would make the earnings target harder to reach and the valuation harder to defend.
Beyond the headline figures, the forward-looking details will likely move the stock more than the quarter itself. Commentary on bookings, pipeline conversion and the fourth-quarter outlook will tell investors whether flat sequential revenue is a resting point before growth or a ceiling. If margin improvement comes from durable mix shifts and pricing discipline, the higher earnings run rate looks sustainable. If it comes from one-time cost cuts or lower headcount that could constrain future capacity, the market may treat the beat with skepticism.
Sentiment has shifted noticeably. Bullish readings climbed to about 33% from just 6% heading into the last report, consistent with a crowd that has grown far more comfortable owning the shares. That optimism, together with the price action, raises the bar. The stock trades at $37.63, well above its 200-day moving average near $23 and roughly 7% below its post-earnings high of $40.33, after rebounding from a low near $24. It is not pressing against a breakout, but it is sitting in the upper part of a range that has been carved almost entirely by enthusiasm.
The central question is whether Everforth can show that profit growth no longer depends on revenue growth. Hitting $1.02 on flat sales, with credible signs that demand is stabilizing in Commercial and holding in Federal, would justify much of the rerating. Matching the numbers without a convincing outlook could leave a stock priced for improvement struggling to explain why it rallied so far.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Sep-24 | |
| Sep-22 | |
| Aug-11 | |
| Aug-04 | |
| Jul-29 | |
| Jul-29 | |
| Jul-28 | |
| Jul-14 | |
| Jul-09 | |
| Jul-07 | |
| Jul-03 | |
| Jun-15 | |
| May-27 |
